Bailey Presses Fiscal Credibility as Gilts Steady
46.10 S&P Global Construction0 Lloyds House Price Index0 Lloyds House Price Index-32 RICS House Price Balance
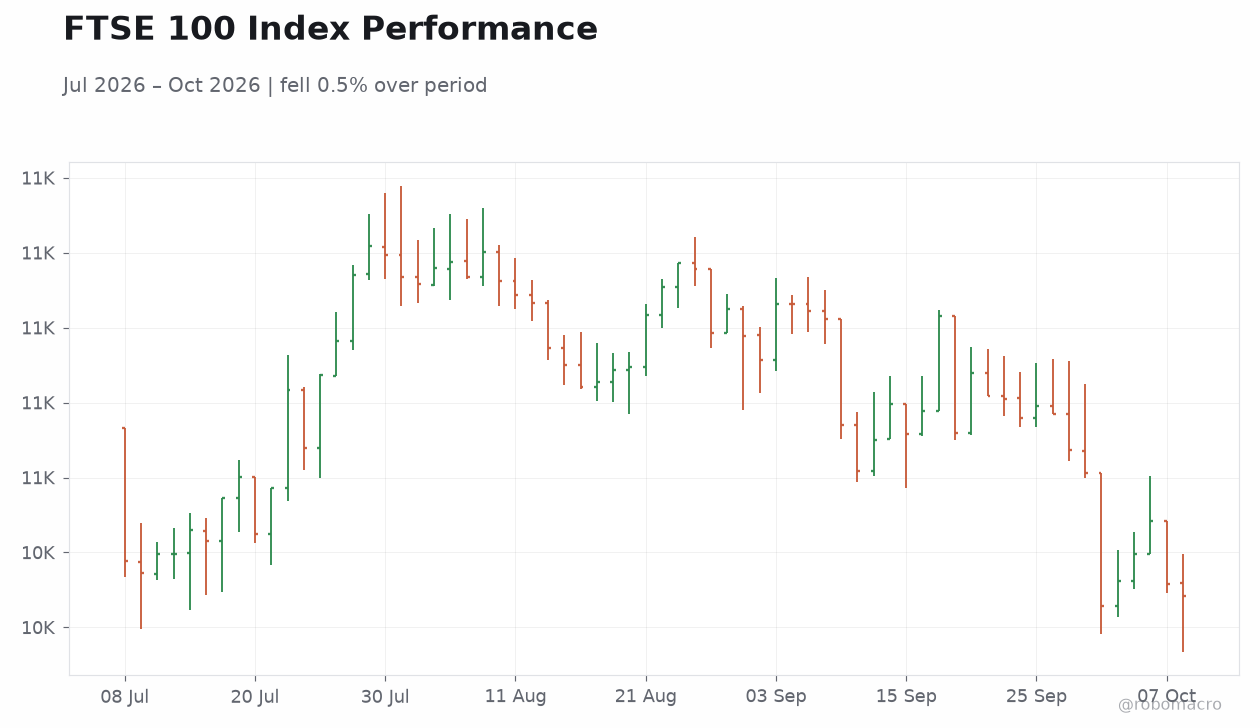
FTSE 10010,448.90-0.09%
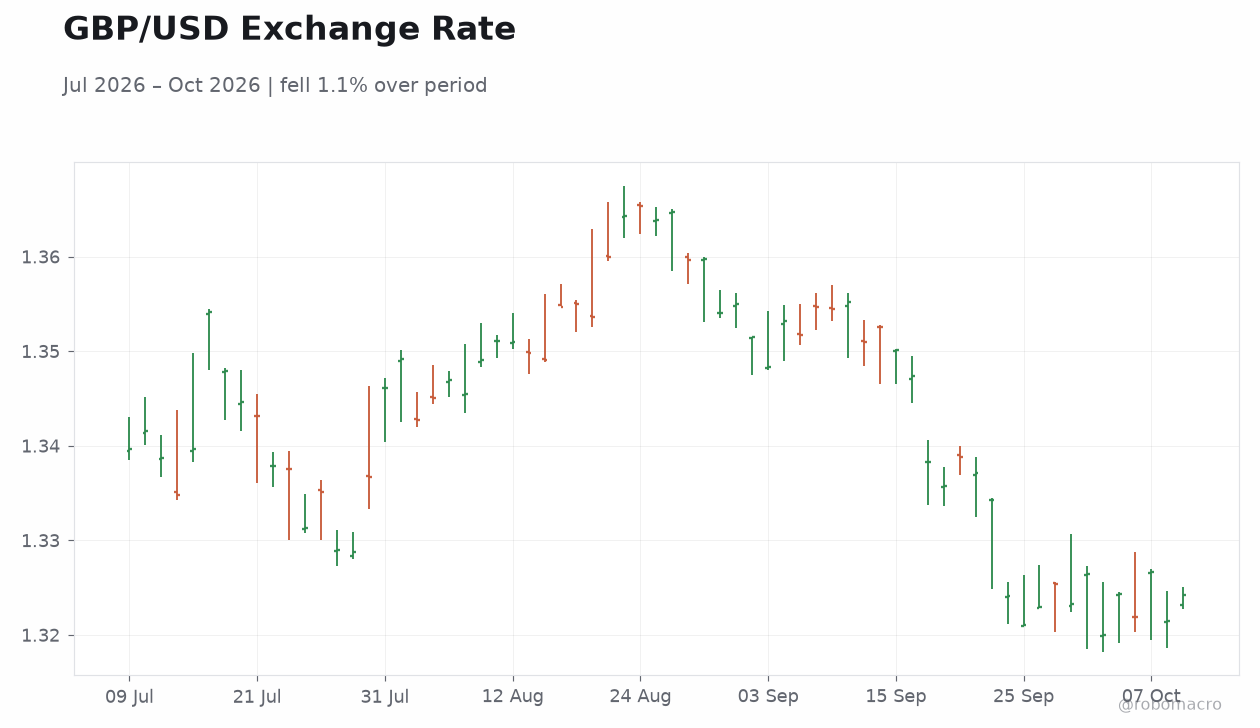
GBP/USD1.32+0.21%
UK 10Y Gilt5.37%-5 bp
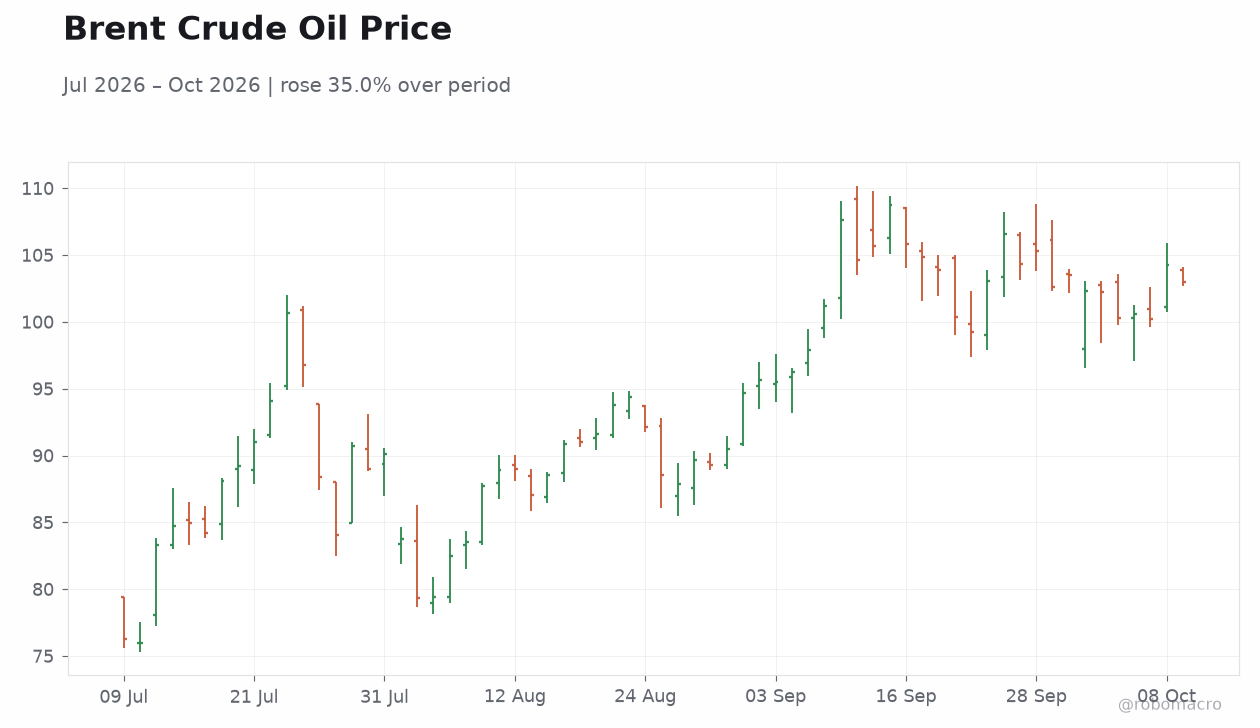
Brent Crude102.83-1.39%
Market Snapshot
| Asset | Level | Change |
|---|
| FTSE 100 | 10,448.90 | -0.09% |
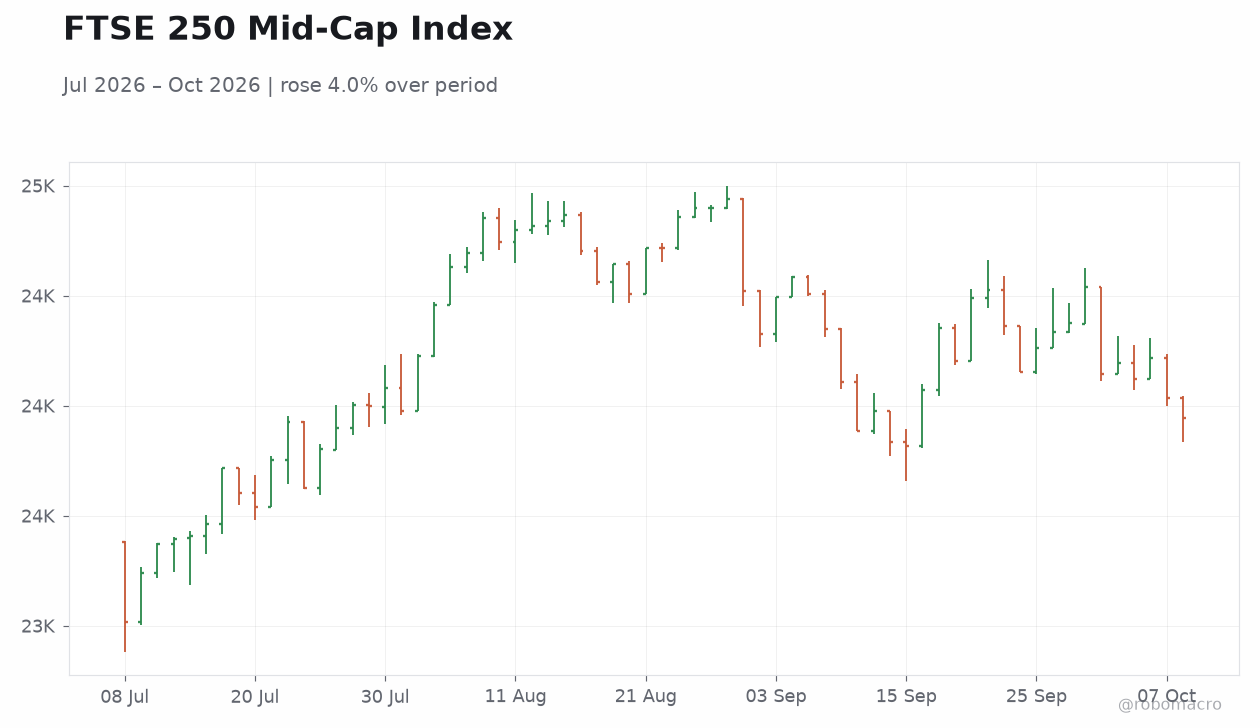
| FTSE 250 | 23,943.90 | -0.39% |
| GBP/USD | 1.32 | +0.21% |
| GBP/EUR | 1.18 | -0.10% |
| GBP/JPY | 209.45 | +0.28% |
| Brent Crude | 102.83 | -1.39% |
| Gold | 4,225.30 | +1.64% |
| UK Nat Gas | 3.14 | -0.95% |
| Bitcoin | 82,327.01 | -1.14% |
| UK 2Y Gilt | 4.63% | +2 bp |
| UK 10Y Gilt | 5.37% | -5 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| BoE Mann Speech | - | - | - |
| S&P Global Construction PMI | 44.30 | 45.20 | 46.10 |
| Lloyds House Price Index Month-over-Month | -0.30 | 0.20 | 0 |
| Lloyds House Price Index Year-over-Year | -0.40 | - | 0 |
| RICS House Price Balance | -28 | -30 | -32 |
| BoE Credit Conditions Survey | - | - | - |
| BoE Greene Speech | - | - | - |
| BoE Gov Bailey Speech | - | - | - |
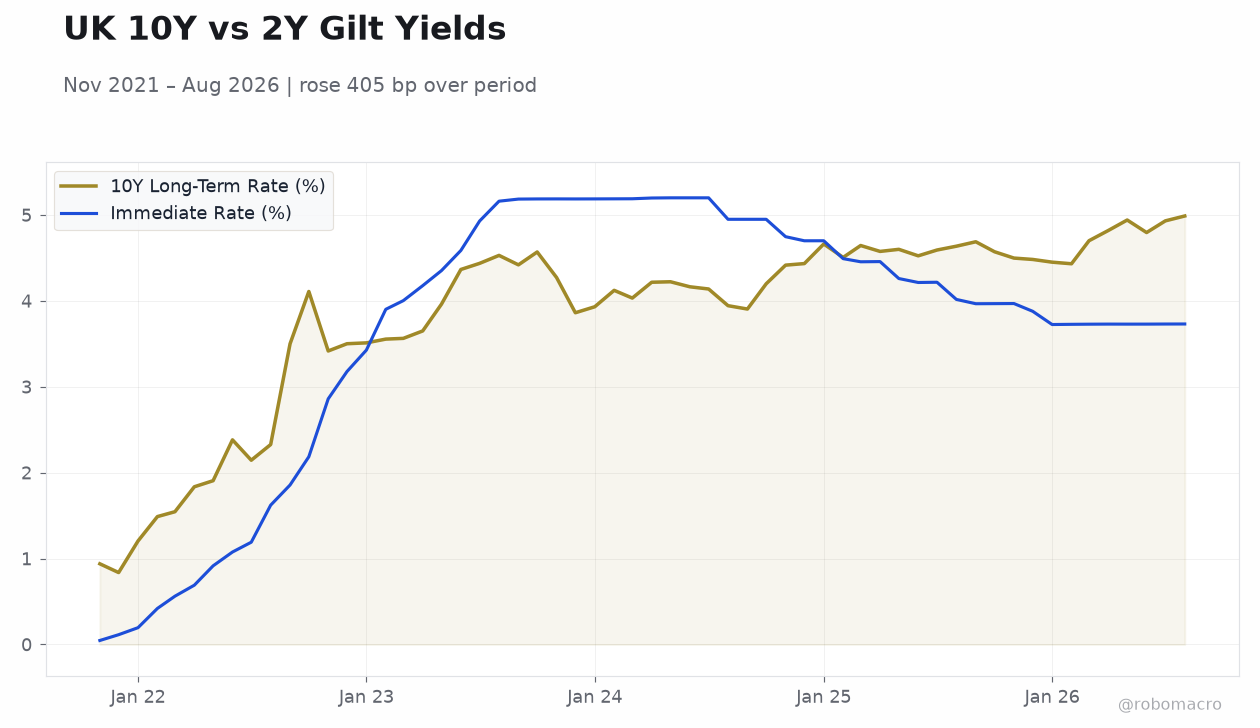 UK 10Y vs 2Y Gilt Yields | Type: macro_line | 10Y Long-Term Rate (%): 4.989 (2026-08-01) | Range: 0.8375–4.989 | Trend(6pt): 0.9394,3.511,4.033,4.6,4.932,4.989 | Immediate Rate (%): 3.731 (2026-08-01) | Range: 0.0468–5.2 | Trend(6pt): 0.0468,3.428,5.189,4.26,3.731,3.731
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| No events available |
- Bailey calls for credible budget policy ahead of the Autumn Budget, warning against a repeat of the 2022 gilt turmoil
- 10-year gilt yield eased 5 bp to 5.37% while the 2-year rose 2 bp to 4.63%; FTSE 100 slipped 0.09%
- Construction PMI improved to 46.1 but housing data stayed soft, with RICS balance at -32
Yesterday's Recap
UK markets ended mixed on Wednesday as investors weighed soft housing data against hawkish-leaning commentary from Bank of England officials. The FTSE 100 closed down 0.09% at 10,448.90, while the mid-cap FTSE 250 underperformed, falling 0.39% to 23,943.90. Sterling firmed 0.21% against the dollar to 1.32 and gained 0.28% versus the yen at 209.45, though it slipped 0.10% against the euro to 1.18.
In fixed income, the 10-year gilt yield eased 5 bp to 5.37%, while the 2-year yield rose 2 bp to 4.63%, flattening the curve modestly as short-end pricing stayed anchored near a 3.73% Bank Rate. Data flow was dominated by housing: the Lloyds House Price Index was flat month-on-month and year-on-year, missing consensus for a 0.2% monthly gain, while the RICS House Price Balance deteriorated to -32 from -28, signaling continued price weakness across the survey panel. Construction activity offered a brighter note, with the S&P Global Construction PMI rising to 46.1 from 44.3, beating the 45.2 consensus though still below the 50 expansion threshold.
On the policy front, Governor Andrew Bailey delivered a speech urging fiscal credibility, and MPC member Catherine Greene also spoke, keeping the Bank firmly in the spotlight ahead of the Budget.
The Day Ahead
Thursday's calendar is quiet on scheduled UK data releases, leaving market attention on secondary flows and policy commentary. With no tier-one prints due, gilt and sterling moves will likely track global risk sentiment and positioning ahead of the Autumn Budget. The BoE Credit Conditions Survey and speeches from Greene and Bailey earlier in the week should continue to reverberate through rate expectations as analysts digest their implications.
Traders will also watch how the 2s10s gilt curve behaves after Wednesday's flattening, with the long end benefiting from fiscal-credibility narratives. Equity desks may see muted volumes absent domestic catalysts, keeping the FTSE 100 tethered to global macro currents. Any follow-up commentary from MPC members could move the short end if it clarifies the path for Bank Rate from the current 3.73% setting.
Page 1
Never miss an issue
Subscribe to UK Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.