UK Macro Daily(Beta Mode)
UK Growth Beat, BoE Divides on Inflation
Market Snapshot
| Asset | Level | Change |
|---|---|---|
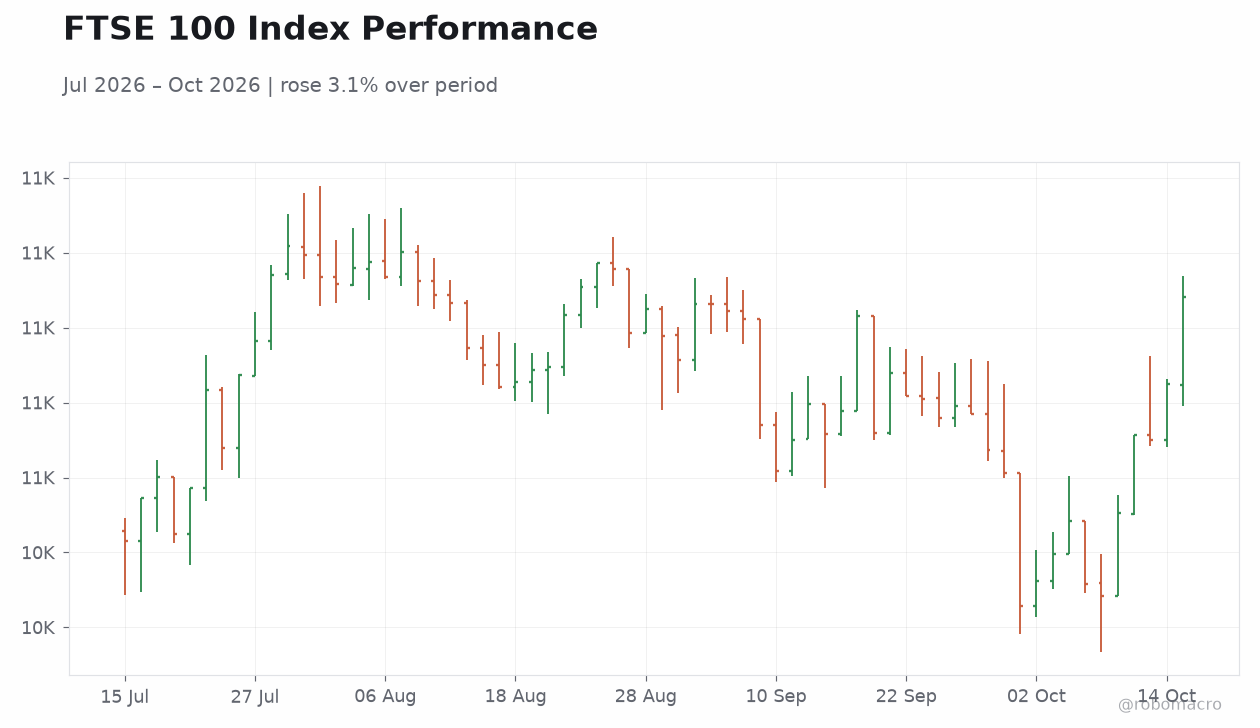
| FTSE 100 | 10,840.35 | +1.08% |
| FTSE 250 | 24,424.80 | +0.26% |
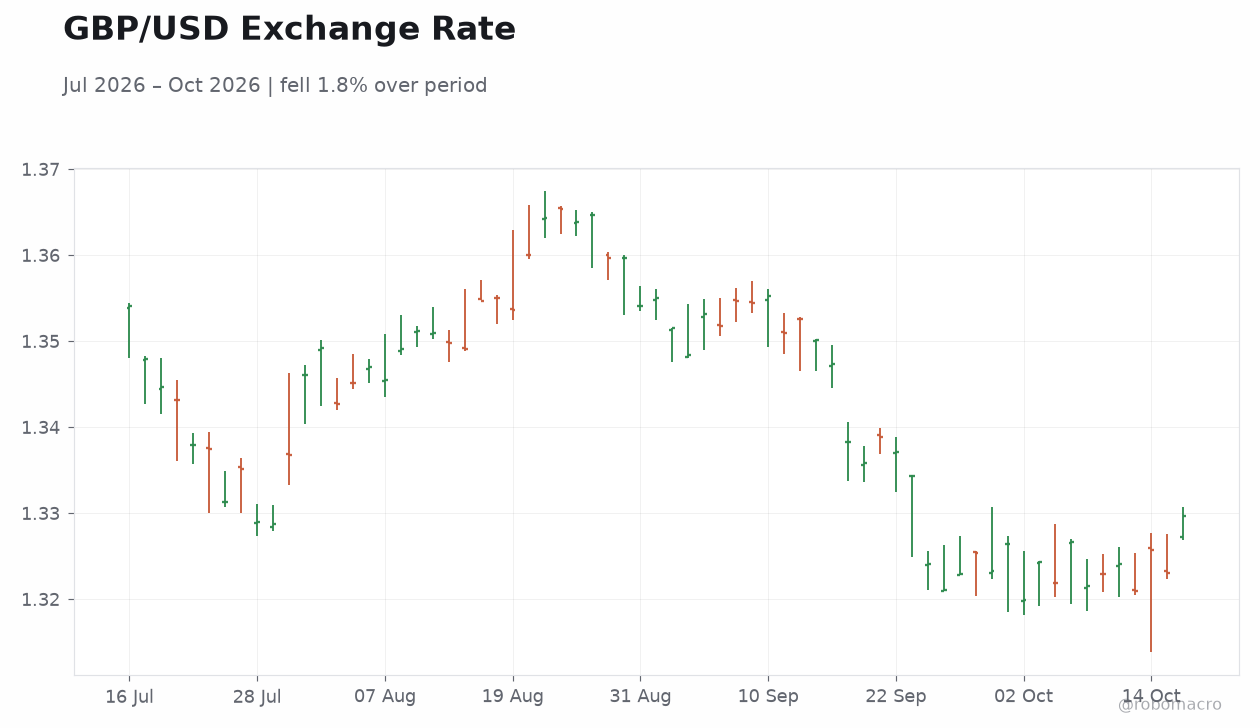
| GBP/USD | 1.33 | +0.52% |
| GBP/EUR | 1.18 | +0.23% |
| GBP/JPY | 209.87 | +0.43% |
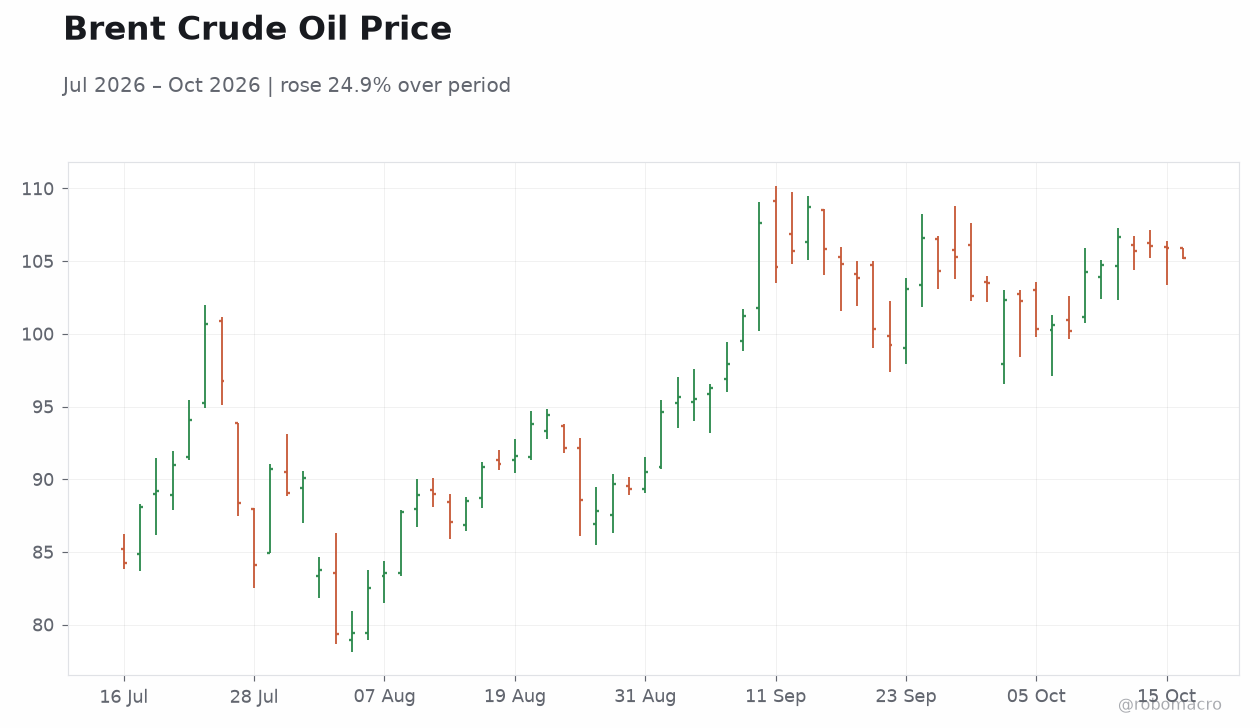
| Brent Crude | 105.22 | -0.66% |
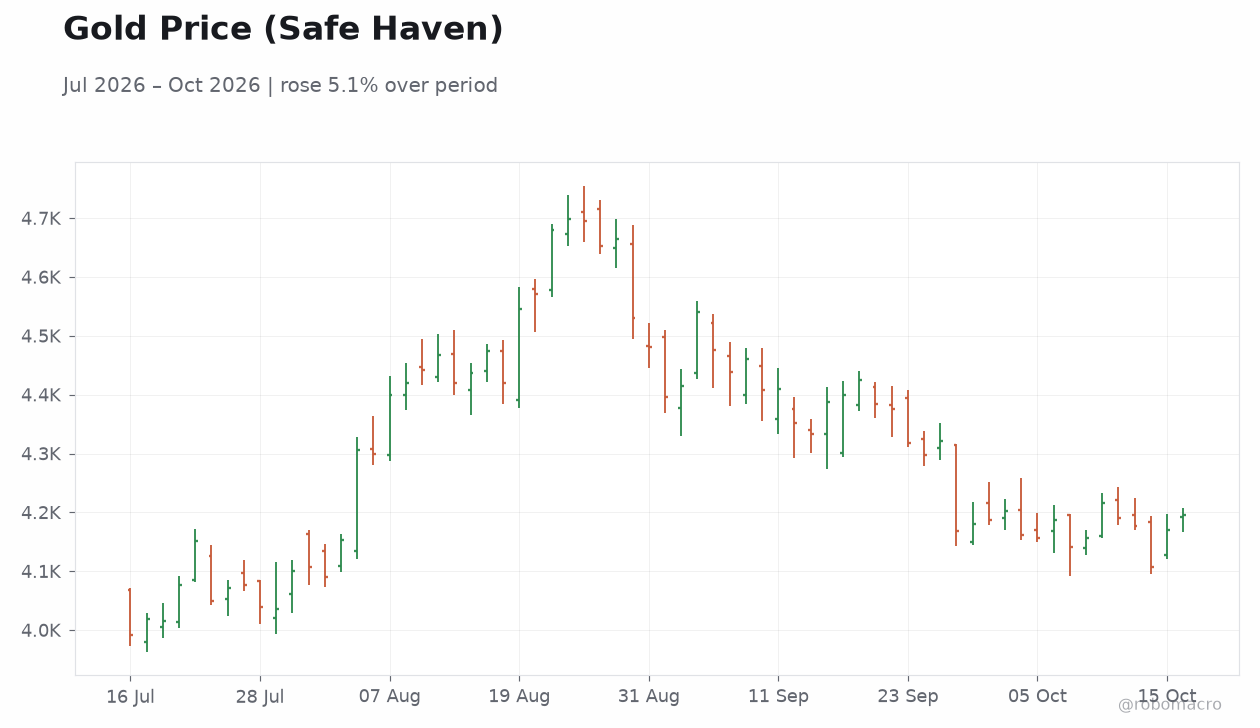
| Gold | 4,192.60 | +0.54% |
| UK Nat Gas | 3.22 | -0.62% |
| Bitcoin | 82,048.56 | +0.60% |
| UK 2Y Gilt | 4.70% | -2 bp |
| UK 10Y Gilt | 5.43% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Dhingra Speech | - | - | - |
| BoE Breeden Speech | - | - | - |
| BoE Gov Bailey Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| BoE Woods Speech | - | - | - |
| GDP Month-over-Month | 0.40 | -0.10 | 0.10 |
| GDP 3-Month Avg | 0.50 | 0.50 | 0.70 |
| Goods Trade Balance | -19,300m | -21,800m | -18,010m |
| Goods Trade Balance Non-EU | -8,190m | - | -5,290m |
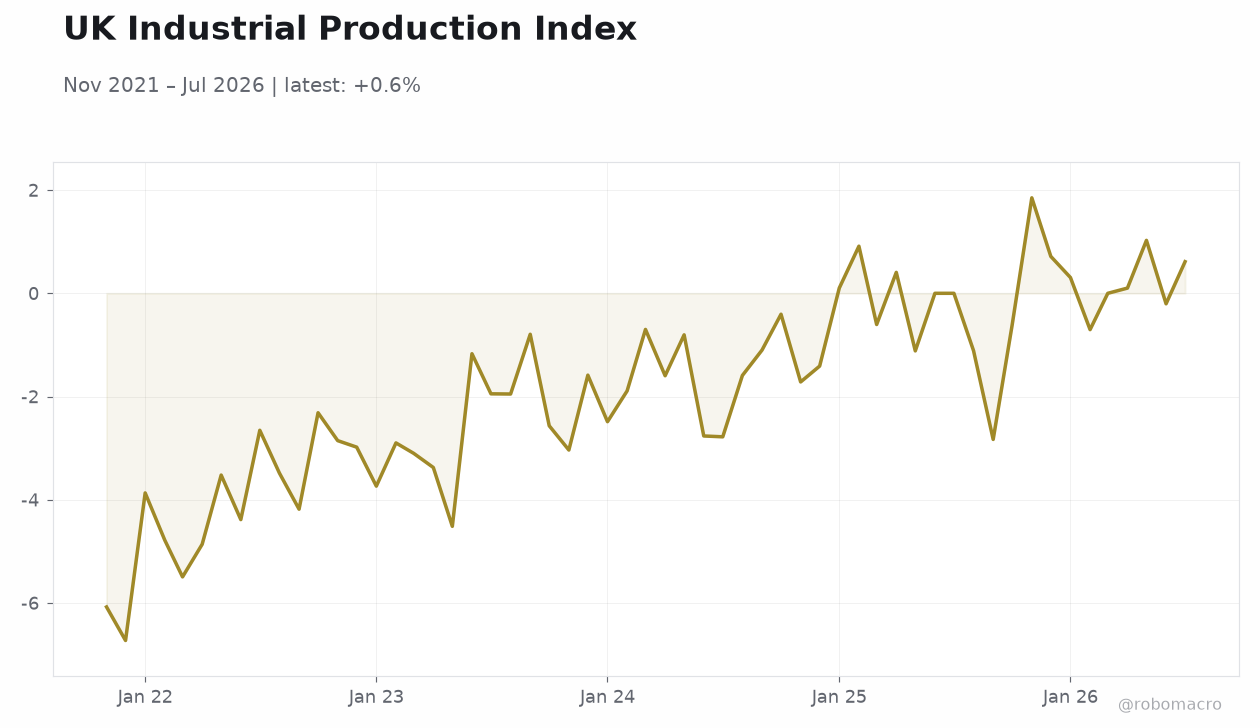 UK Industrial Production Index | Type: macro_line | Industrial Production Index: 0.6129 (2026-07-01) | Range: -6.726–1.85 | Trend(5pt): -6.077,-3.736,-0.7,-1.116,0.6129
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Saturday (2026-10-17) | |||
| BoE Gov Bailey Speech | - | - | 02:45 |
- August GDP rose 0.1% m/m, beating the -0.1% consensus, while the three-month average accelerated to 0.7% from 0.5%, signalling firmer underlying momentum.
- Manufacturing production surged 1.2% m/m and industrial output gained 0.8%, both far above forecasts, as the goods trade deficit narrowed to £18.0bn.
- Sterling firmed to $1.33 and gilt yields held near 5.43% as markets price a possible BoE hike to 4% in November.
Yesterday's Recap
UK data delivered a positive surprise on Thursday. GDP expanded 0.1% month-on-month in August against expectations of a 0.1% contraction, and the three-month average through August reached 0.7%, up from 0.5% previously. The production side drove the beat: manufacturing output jumped 1.2% m/m after a 1.0% prior gain, and industrial production rose 0.8% versus a forecast decline.
External accounts improved too, with the overall goods trade deficit narrowing to £18.0bn from £19.3bn and the non-EU gap shrinking to £5.3bn. Markets responded with a classic risk-on, sterling-positive pattern: the FTSE 100 climbed 1.08% to 10,840, the FTSE 250 added 0.26%, and cable firmed 0.52% to 1.33 against the dollar. The 2-year gilt yield eased 2 bp to 4.70% while the 10-year held at 5.43%, a modest bull-flattening consistent with growth optimism tempered by sticky inflation.
Brent crude slipped 0.66% to $105.22, offering marginal relief on the energy front.
The Day Ahead
Friday's calendar is light on tier-one UK data, with the session anchored by commentary rather than releases. Governor Andrew Bailey is scheduled to speak early on Saturday at 02:45 UK time, closing out an unusually dense week of BoE communications that has featured Dhingra, Breeden, Pill, Woods and Cleland. With no CPI, labour-market or retail-sales prints due, attention shifts to how markets digest the week's growth upside and the widening range of MPC views on the inflation outlook.
Positioning into the weekend may see sterling consolidate gains, with the 2s10s gilt curve and FTSE breadth the key tells. Any colour from Bailey on the November decision path will be scrutinised given the hawkish repricing already under way.
Other Economic Notes
The composition of the growth beat matters as much as its size. Output is expanding without a corresponding pickup in hiring — unemployment sits at 4.9% — a productivity-flavoured pattern that complicates the case for demand-led rate cuts. ↓ p.2