RoboMacro ResearchAlso todaySee the VIX Daily

UK Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Sterling Firms as Bailey Flags Subdued Price Pressures

FTSE 10010,881.90+0.38%
GBP/USD1.33+0.43%
UK 10Y Gilt5.42%-1 bp
Brent Crude107.70-1.97%

Market Snapshot

AssetLevelChange
FTSE 10010,881.90+0.38%
FTSE 25024,533.90+0.45%
GBP/USD1.33+0.43%
GBP/EUR1.19+0.29%
GBP/JPY210.76+0.42%
Brent Crude107.70-1.97%
Gold4,204.30+0.55%
UK Nat Gas3.08-1.22%
Bitcoin82,670.82+1.58%
UK 2Y Gilt4.67%-3 bp
UK 10Y Gilt5.42%-1 bp

Prior Economic Events

Data Prior Cons Actual
No events available
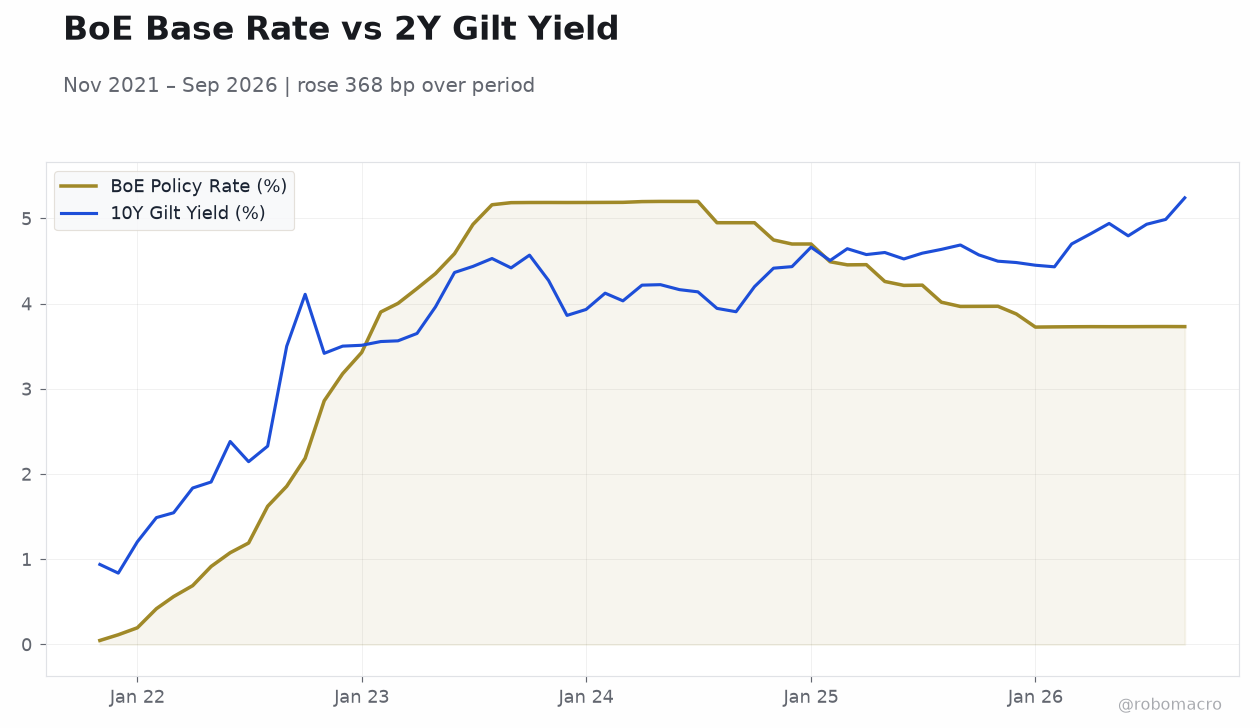
BoE Base Rate vs 2Y Gilt YieldBoE Base Rate vs 2Y Gilt Yield | Type: macro_line | BoE Policy Rate (%): 3.731 (2026-09-01) | Range: 0.0468–5.2 | Trend(6pt): 0.0468,3.428,5.189,4.26,3.731,3.731 | 10Y Gilt Yield (%): 5.242 (2026-09-01) | Range: 0.8375–5.242 | Trend(6pt): 0.9394,3.511,4.033,4.6,4.932,5.242

Today's Economic Events

Data Prior Cons Time
No events available
  • Sterling gained 0.43% against the dollar to 1.33, while the FTSE 100 rose 0.38% to 10,881.90 and the FTSE 250 added 0.45% to 24,533.90.
  • Gilt yields eased, with the 2-year down 3 bp to 4.67% and the 10-year slipping 1 bp to 5.42%, as Governor Andrew Bailey described second-round inflation pressures as "quite subdued".
  • Attention turns to the UK's fiscal landscape, with Chancellor John Healey's first Budget looming and speculation mounting over potential tax rises for the banking sector.

Yesterday's Recap

UK markets closed the week on a constructive note, with risk appetite firming across the board. The FTSE 100 advanced 0.38% to 10,881.90, while the mid-cap FTSE 250 outperformed marginally, gaining 0.45% to 24,533.90 — a signal of domestic confidence. Sterling was the standout, appreciating 0.43% against the dollar to 1.33 and 0.29% versus the euro to 1.19, with GBP/JPY also up 0.42% at 210.76.

In fixed income, the 2-year gilt yield fell 3 bp to 4.67%, and the 10-year yield eased 1 bp to 5.42%, reflecting a modest bull-flattening as investors priced in a more dovish tone from the Bank of England. The commodity complex was mixed: Brent crude dropped 1.97% to $107.70, and UK natural gas declined 1.22% to 3.08, offering some relief on the imported-inflation front. Gold rose 0.55% to $4,204.30, while Bitcoin rallied 1.58% to $82,670.82.

The combination of a firmer currency and lower front-end yields suggests markets are leaning toward a benign inflation outlook, reinforced by recent data showing the UK economy unexpectedly grew 0.1% in August.

The Day Ahead

The calendar is light at the start of the week, with no major tier-one UK data releases scheduled. Attention will instead focus on commentary from Bank of England policymakers, following Governor Bailey's remarks on subdued second-round price pressures at the IMF meetings. Markets will parse any further guidance on the timing of the next rate move, with the Bank currently holding Bank Rate at 3.73%.

Chancellor Healey's pre-Budget rhetoric will also be scrutinised, as the Treasury keeps tax options open amid pressure from the financial services sector. Later in the week, investors will look ahead to the Bank of Japan's rate decision for global rate-cycle context. With UK CPI at 3.1% year-on-year, still above target, the interplay between fiscal policy and monetary accommodation remains the key medium-term theme.

Other Economic Notes

The UK's fiscal picture is dominating domestic headlines as the first Healey Budget approaches. ↓ p.2
Page 1

UK Macro Daily(Beta Mode)

October 19, 2026 robomacro.com
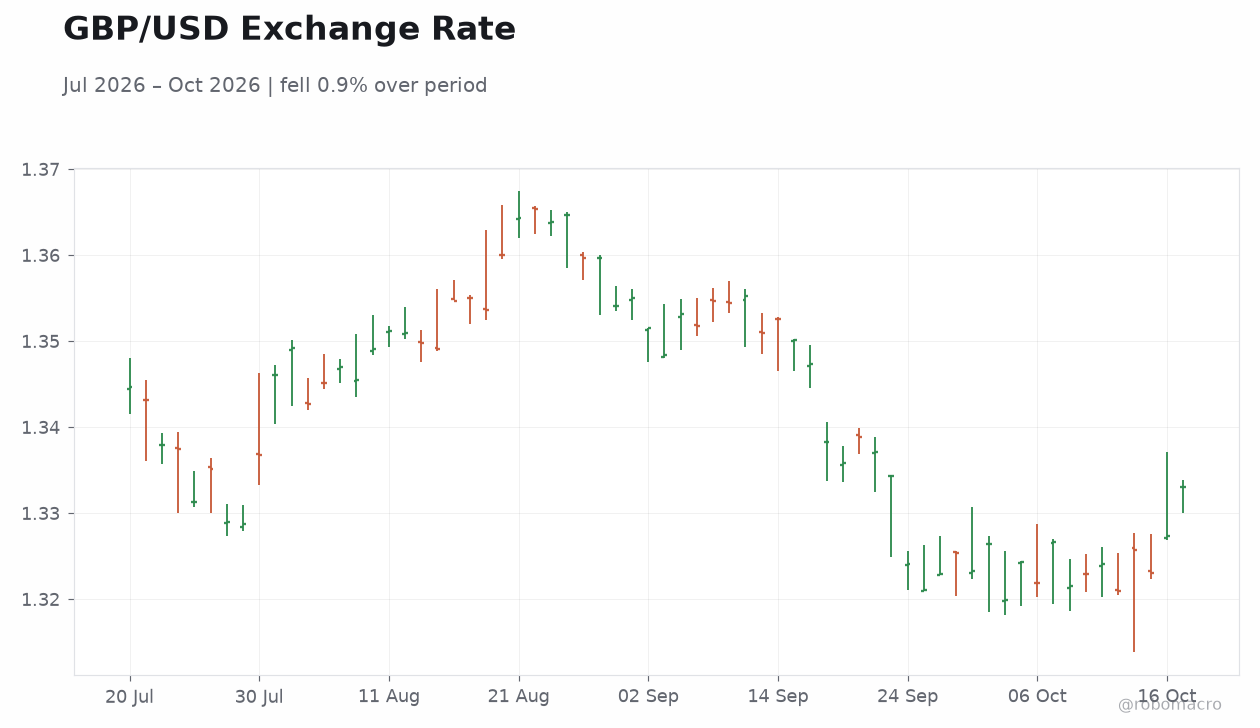
GBP/USD Exchange Rate GBP/USD Exchange Rate | Type: market_hloc | GBP/USD: 1.333 (2026-10-19) | Range: 1.32–1.365 | Trend(6pt): 1.345,1.351,1.352,1.324,1.327,1.333
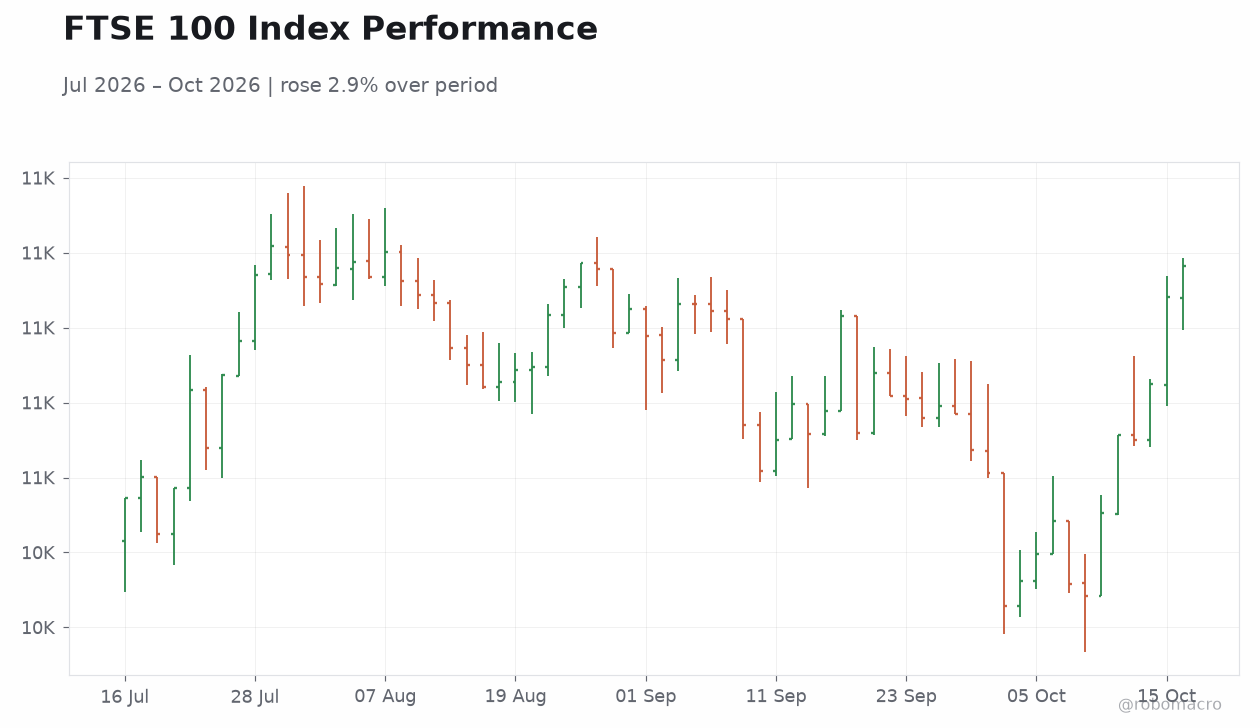
FTSE 100 Index Performance FTSE 100 Index Performance | Type: market_hloc | FTSE 100: 1.088e+04 (2026-10-16) | Range: 1.043e+04–1.091e+04 | Trend(6pt): 1.057e+04,1.09e+04,1.079e+04,1.071e+04,1.084e+04,1.088e+04
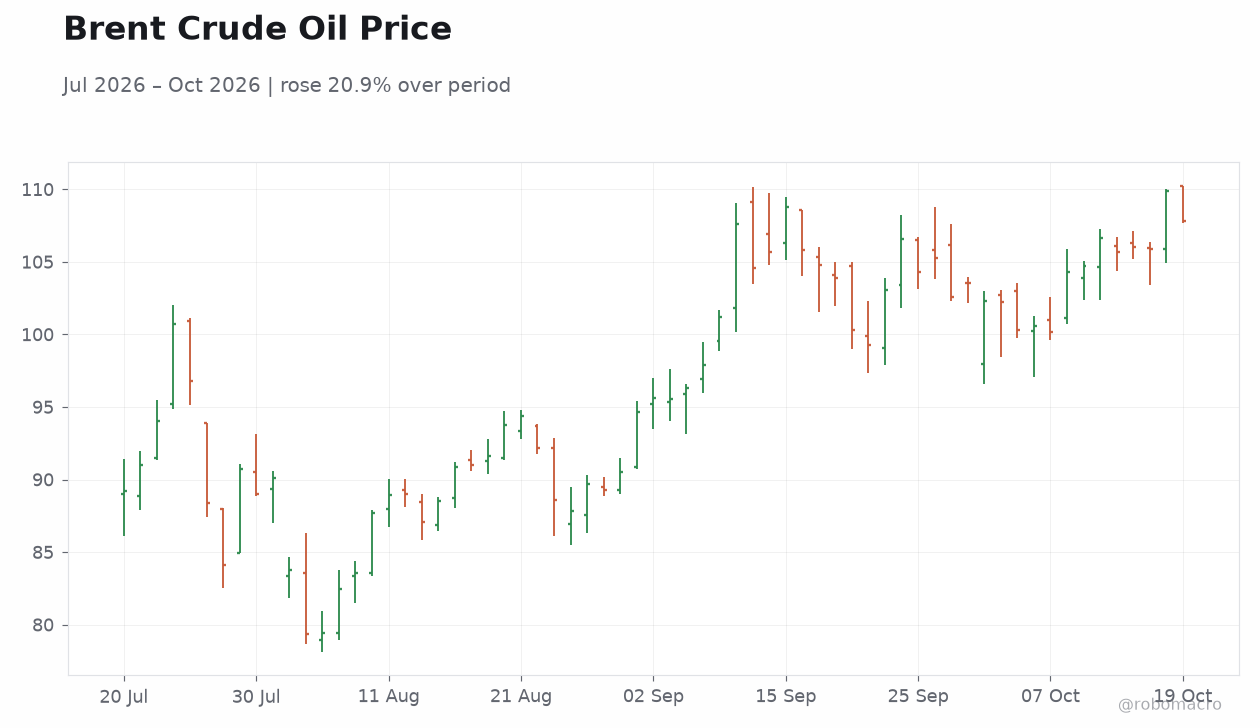
Brent Crude Oil Price Brent Crude Oil Price | Type: market_hloc | Brent ($/bbl): 107.8 (2026-10-19) | Range: 79.36–109.9 | Trend(5pt): 89.22,88.91,95.63,104.3,107.8
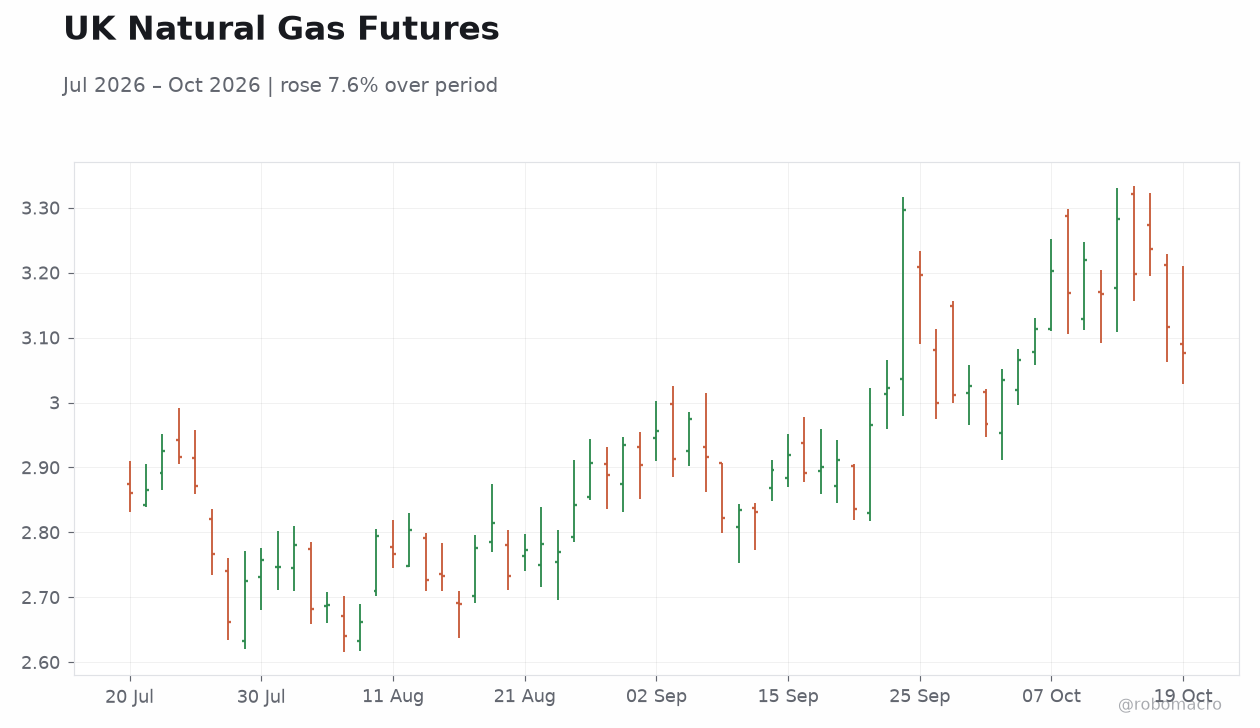
UK Natural Gas Futures UK Natural Gas Futures | Type: market_hloc | Nat Gas ($/MMBtu): 3.076 (2026-10-19) | Range: 2.64–3.297 | Trend(5pt): 2.86,2.767,2.956,3.196,3.076

Other Economic Notes (continued)

The Chancellor has signalled that banks are "key to the economy" but refuses to rule out tax rises, keeping the financial sector's lobbying campaign on high alert — though divisions between large lenders may have blunted its effectiveness. The resilience of the UK economy has surprised forecasters, with August's 0.1% GDP expansion defying expectations of stagnation, prompting the IMF to revise its outlook. However, the underlying picture remains fragile, with the struggling economy looming large over fiscal plans and constraining the Chancellor's room for manoeuvre.

Global Macro News

Global trade tensions continue to reshape macro alignments, with Canada's Carney government pursuing a "European pivot" as Trump's trade war forces a rethink of transatlantic relationships — a dynamic with implications for UK trade negotiations. In energy markets, Brent crude's 1.97% decline to $107.70 came despite renewed geopolitical risk, as UKMTO reported an unknown projectile striking a tanker off Saudi Arabia's coast and gunmen firing on a vessel near Yemen. The UK Maritime Trade Operations noted that most vessels are not reporting Hormuz attacks, suggesting actual disruption may be understated — a factor keeping a floor under shipping and insurance costs.

Meanwhile, the dollar's dominance is under scrutiny, with the Bank of England itself publishing analysis on financial innovation and dollar hegemony's monetary policy implications. Japan's policy trajectory also matters, with the BoJ's October decision looming as a test of the global normalisation cycle.

Sponsored by Arbitrage Search
Page 2

UK Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Continuation

BoE Watch

Governor Andrew Bailey's characterisation of second-round price pressures as "quite subdued" is the most significant signal for rate expectations, suggesting the Bank sees limited wage-price spiral risk despite headline CPI at 3.1%. With Bank Rate at 3.73%, the committee retains room to ease further should activity data soften, and the 3 bp decline in the 2-year yield suggests markets are beginning to price a slightly more accommodative path. However, the Bank's own research into financial innovation and dollar dominance — presented at the IMF — hints at a deeper structural concern: that US monetary policy transmits more powerfully to UK financial conditions than domestic settings, complicating the calibration of Bank Rate.

Bailey's high-profile walkout from an IMF summit in protest at Russia's presence underscores the geopolitical overlay now shaping policy deliberations. Commentary urging the Governor to "stop sitting on his hands" reflects growing impatience among commentators, but the data-dependent stance appears intact. The key tension: with the economy showing unexpected resilience and inflation above target, the MPC must weigh premature easing against choking off the recovery — and fiscal expansion from the Healey Budget could tip that balance either way.

Sponsored by Arbitrage Search
Page 3