RoboMacro ResearchAlso todaySee the FI Daily

UK Macro Daily(Beta Mode)

October 21, 2026 robomacro.com

Sterling Jumps on Jobs Surprise as Hike Bets Build

FTSE 10010,733.00-0.29%
GBP/USD1.34+0.55%
UK 10Y Gilt5.34%0 bp
Brent Crude110.60+1.66%

Market Snapshot

AssetLevelChange
FTSE 10010,733.00-0.29%
FTSE 25024,364.80-0.06%
GBP/USD1.34+0.55%
GBP/EUR1.19+0.40%
GBP/JPY211.57+0.28%
Brent Crude110.60+1.66%
Gold4,139.10-0.08%
UK Nat Gas2.97+0.13%
Bitcoin82,581.24+0.89%
UK 2Y Gilt4.71%+7 bp
UK 10Y Gilt5.34%0 bp

Prior Economic Events

Data Prior Cons Actual
No events available
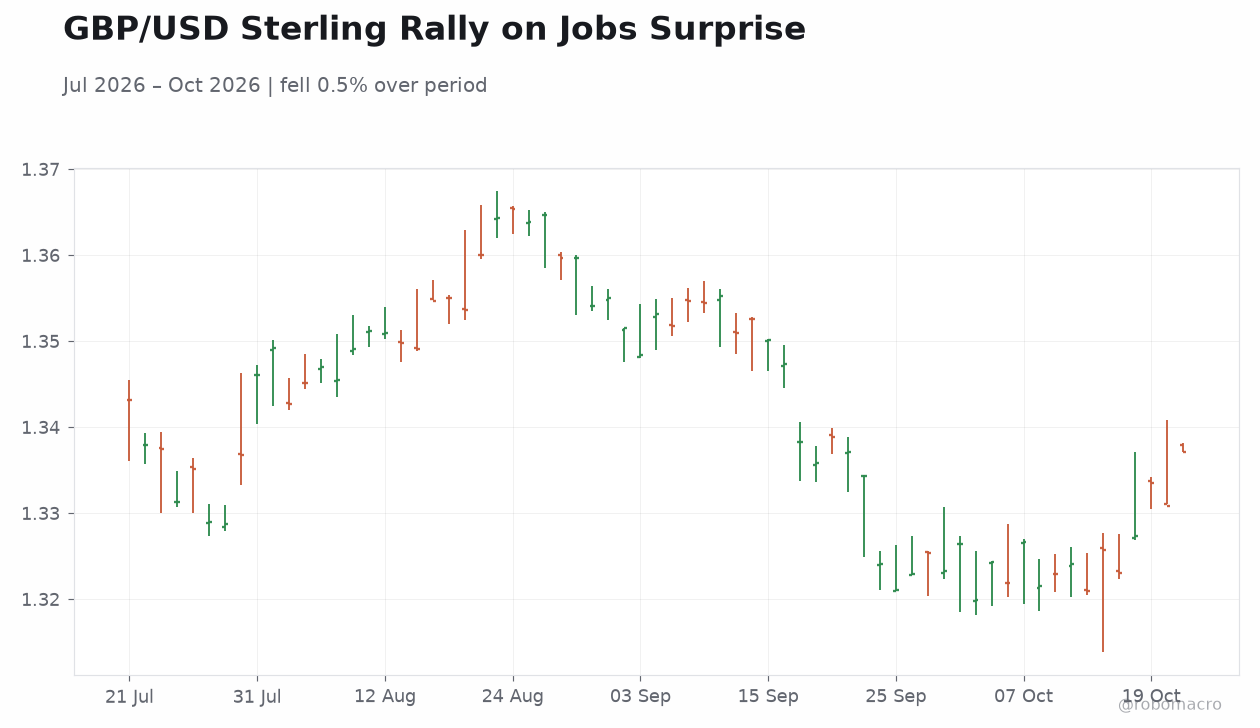
GBP/USD Sterling Rally on Jobs SurpriseGBP/USD Sterling Rally on Jobs Surprise | Type: market_hloc | GBP/USD: 1.337 (2026-10-21) | Range: 1.32–1.365 | Trend(6pt): 1.343,1.351,1.348,1.321,1.334,1.337

Today's Economic Events

Data Prior Cons Time
No events available
  • UK unemployment fell to 4.70% with wage growth picking up, reinforcing expectations of a November Bank of England rate hike and lifting sterling across the board.
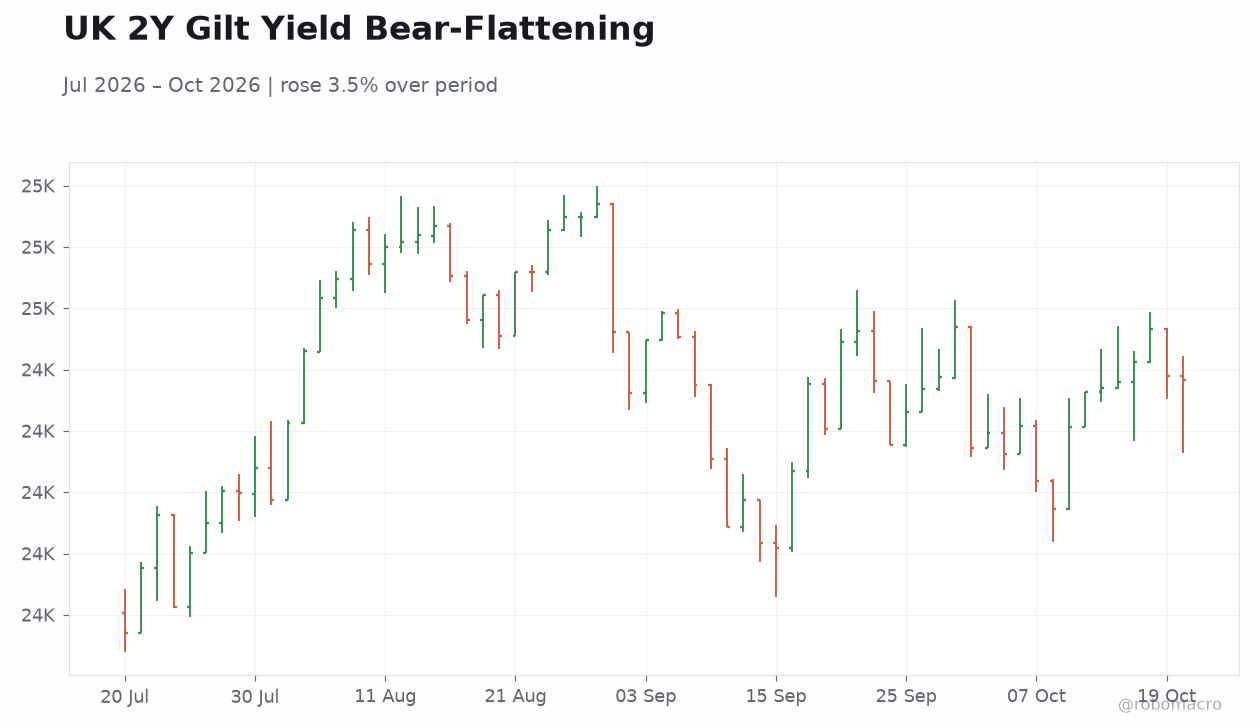
  • Gilt curve bear-flattened as the 2-year yield rose 7 bp to 4.71% while the 10-year held at 5.34%, with markets repricing near-term policy risk.
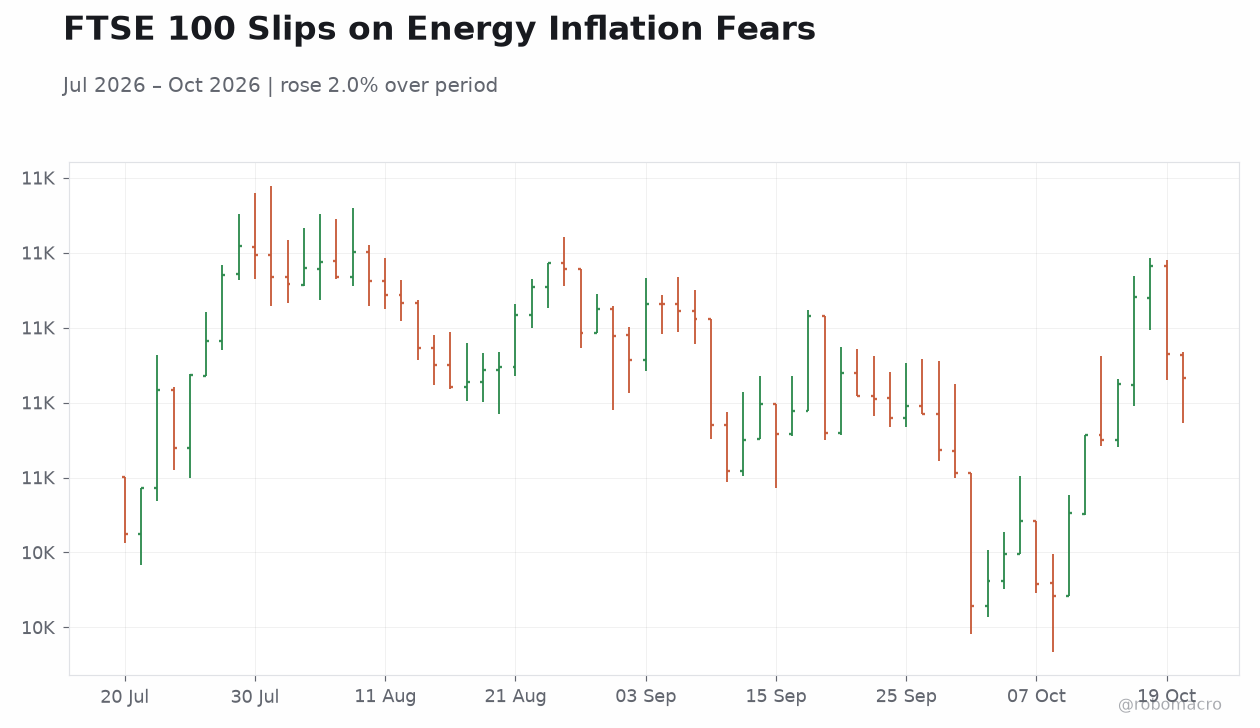
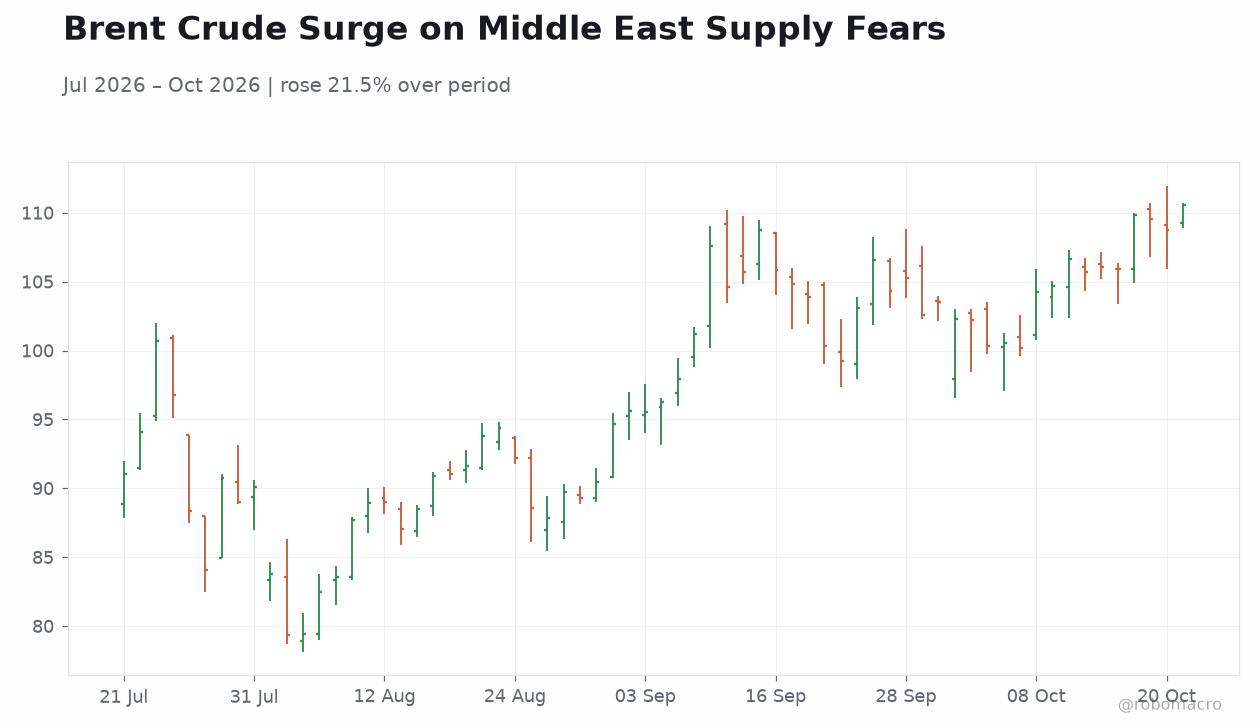
  • Brent crude surged 1.66% to $110.60 on Middle East supply fears, while FTSE 100 slipped 0.29% amid energy-driven inflation concerns.

Yesterday's Recap

UK labour market data surprised to the downside on unemployment, which fell to 4.70%, its lowest level since July of last year, while wage growth accelerated modestly in the three months through August. The figures landed ahead of the Bank of England's November meeting and were read by markets as cementing the case for a rate hike, with sterling rallying sharply on the release. GBP/USD climbed 0.55% to 1.34, GBP/EUR advanced 0.40% to 1.19, and GBP/JPY rose 0.28% to 211.57.

Gilt markets reflected the repricing, with the UK 2-year yield rising 7 bp to 4.71% while the 10-year held steady at 5.34%, producing a bear-flattening move at the front end. Equities were softer, with the FTSE 100 down 0.29% to 10,733.00 and the FTSE 250 off 0.06% at 24,364.80, as higher rate expectations and elevated energy prices weighed on sentiment. Brent crude jumped 1.66% to $110.60, adding to the inflationary backdrop that underpins the hawkish policy narrative.

The Day Ahead

The UK calendar is light, with no major tier-one data releases scheduled, leaving markets to consolidate the labour market surprise and position ahead of the Bank of England's November decision. Attention will centre on any further Bank of England commentary following MPC member Greene's warning that inflation risks are larger than previously thought, which reinforced the hawkish tone set by the jobs data. Gilt traders will watch for follow-through in the 2-year sector after the 7 bp rise, with the front-end curve likely to remain sensitive to any shift in hike pricing.

Sterling crosses will take their cue from broader risk sentiment and energy price developments, particularly given Brent's move above $110. With the Budget looming, fiscal expectations may also begin to feed into gilt and sterling positioning as investors assess the Chancellor's plans.

Other Economic Notes

The combination of falling unemployment and accelerating wage growth complicates the inflation outlook, as stronger labour income risks sustaining domestic price pressures well into 2027. ↓ p.2
Page 1

UK Macro Daily(Beta Mode)

October 21, 2026 robomacro.com
FTSE 100 Slips on Energy Inflation Fears FTSE 100 Slips on Energy Inflation Fears | Type: market_hloc | FTSE 100: 1.073e+04 (2026-10-20) | Range: 1.043e+04–1.091e+04 | Trend(6pt): 1.052e+04,1.084e+04,1.083e+04,1.07e+04,1.076e+04,1.073e+04
Brent Crude Surge on Middle East Supply Fears Brent Crude Surge on Middle East Supply Fears | Type: market_hloc | Brent Crude (USD): 110.6 (2026-10-21) | Range: 79.36–110.6 | Trend(6pt): 91.01,88.98,95.52,105.3,108.8,110.6
UK 2Y Gilt Yield Bear-Flattening UK 2Y Gilt Yield Bear-Flattening | Type: market_hloc | FTSE 250: 2.436e+04 (2026-10-20) | Range: 2.354e+04–2.494e+04 | Trend(6pt): 2.354e+04,2.48e+04,2.45e+04,2.426e+04,2.438e+04,2.436e+04

Other Economic Notes (continued)

With CPI running at 3.10% year-on-year, well above target, the Bank of England faces a delicate balancing act between restraining inflation and avoiding unnecessary damage to an economy that is only now showing signs of employment resilience. The Budget represents a key near-term risk, with fiscal loosening potentially adding to demand-side pressures and complicating the monetary policy path. Energy costs remain a persistent threat, with Brent above $110 keeping headline inflation risks skewed to the upside and squeezing household real incomes.

Global Macro News

Middle East tensions dominated the global backdrop, with a Saudi-led coalition intercepting four drones launched towards the kingdom and Houthi attacks continuing to disrupt regional stability, pushing Brent crude up 1.66% to $110.60. The attacks have driven private jet charter costs from Saudi Arabia up more than 50% as wealthy travellers exit the kingdom, underscoring the scale of disruption to regional business activity. In the US, United Airlines forecast quarterly profit well below estimates as soaring fuel costs threaten to offset strong travel demand, a reminder that elevated energy prices are transmitting into corporate margins globally.

A lawsuit challenging US tariffs against Canada has been filed at the Court of International Trade, keeping trade policy uncertainty in focus. Gold held near $4,139.10, down 0.08%, while Bitcoin rose 0.89% to $82,581.24.

Sponsored by Arbitrage Search
Page 2

UK Macro Daily(Beta Mode)

October 21, 2026 robomacro.com

Continuation

BoE Watch

Bank of England policymaker Greene warned that inflation risks are bigger than previously thought, a clear signal that the committee remains concerned about persistent price pressures even as headline CPI sits at 3.10%. The combination of falling unemployment at 4.70% and accelerating wage growth has strengthened the case for a November rate hike, with markets now pricing a higher probability of tightening. The Bank of England is also considering stress testing the financial sector's exposure to artificial intelligence, reflecting its broadening remit on emerging risks.

The Bank Rate currently stands at 3.73%, and with inflation well above target and the labour market tightening, the MPC's forward guidance has taken on a distinctly hawkish tone. The committee's communications suggest a bias toward further tightening unless inflation data meaningfully decelerate, keeping front-end gilt yields and sterling supported. Markets should watch for any further speeches that clarify the committee's tolerance for above-target inflation, as these will drive near-term rate expectations.

Sponsored by Arbitrage Search
Page 3