UK Macro Daily(Beta Mode)
Inflation Shock Lifts Sterling, Gilts
Market Snapshot
| Asset | Level | Change |
|---|---|---|
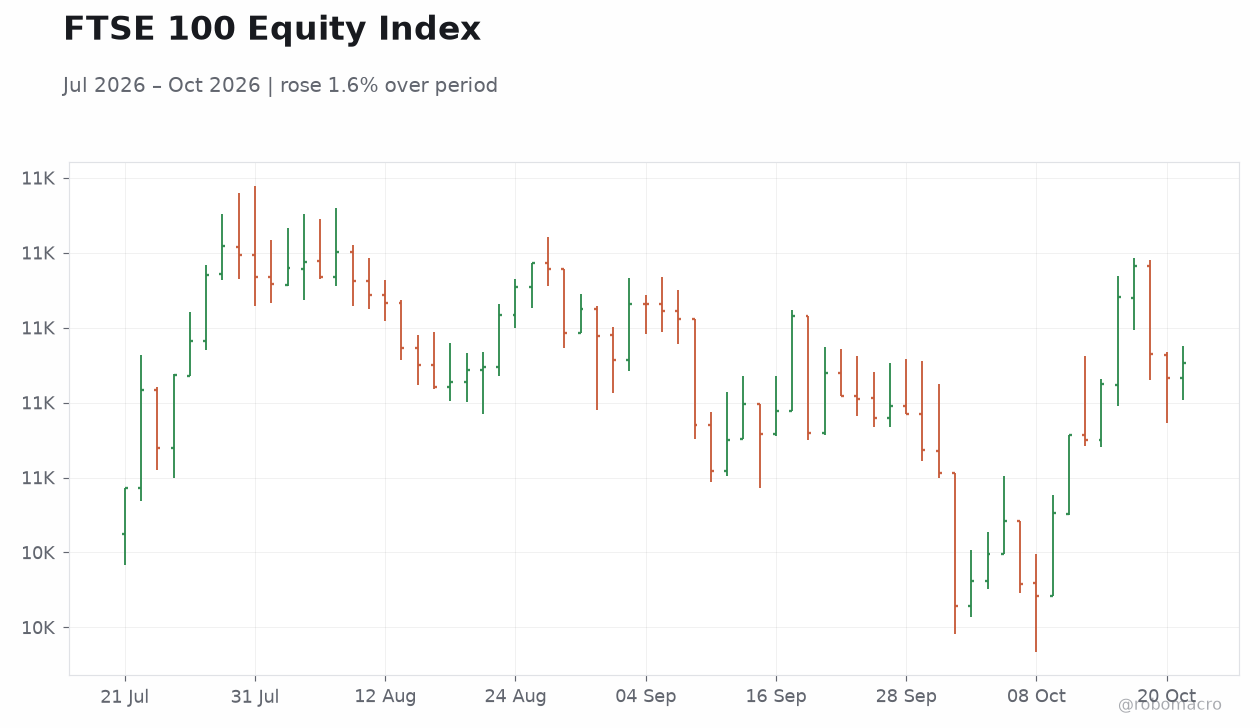
| FTSE 100 | 10,752.88 | +0.19% |
| FTSE 250 | 24,439.80 | +0.31% |
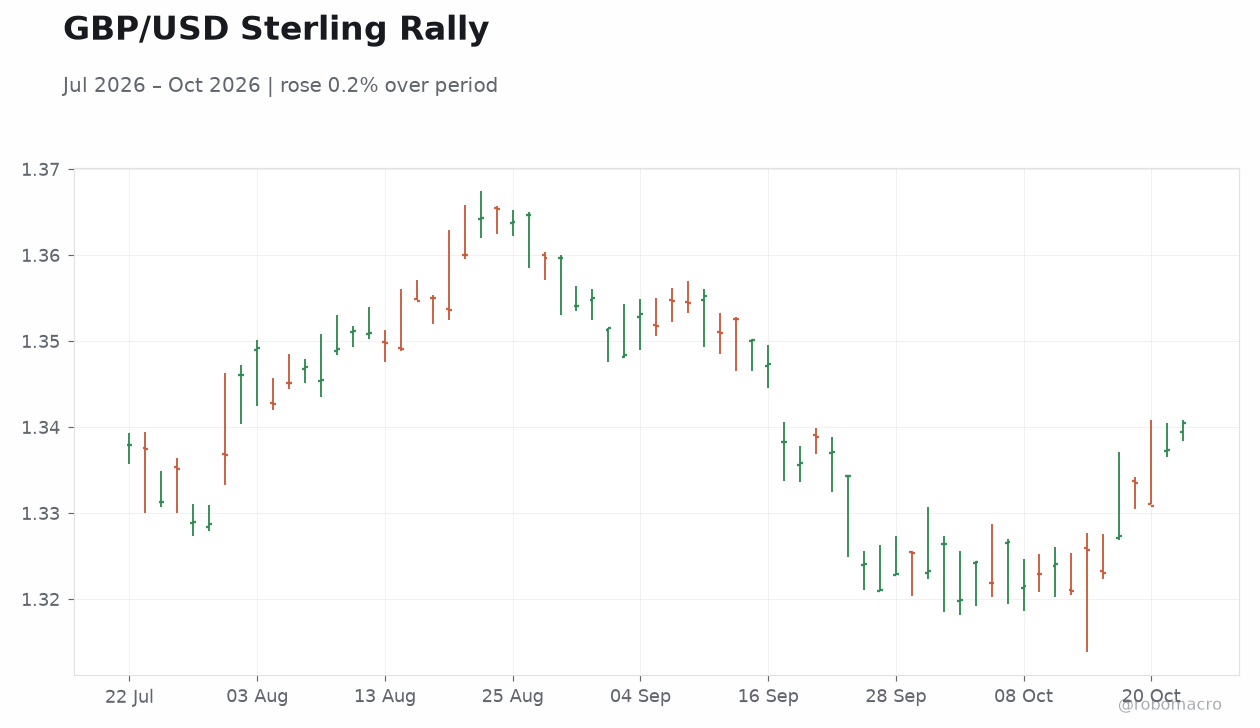
| GBP/USD | 1.34 | +0.25% |
| GBP/EUR | 1.19 | -0.02% |
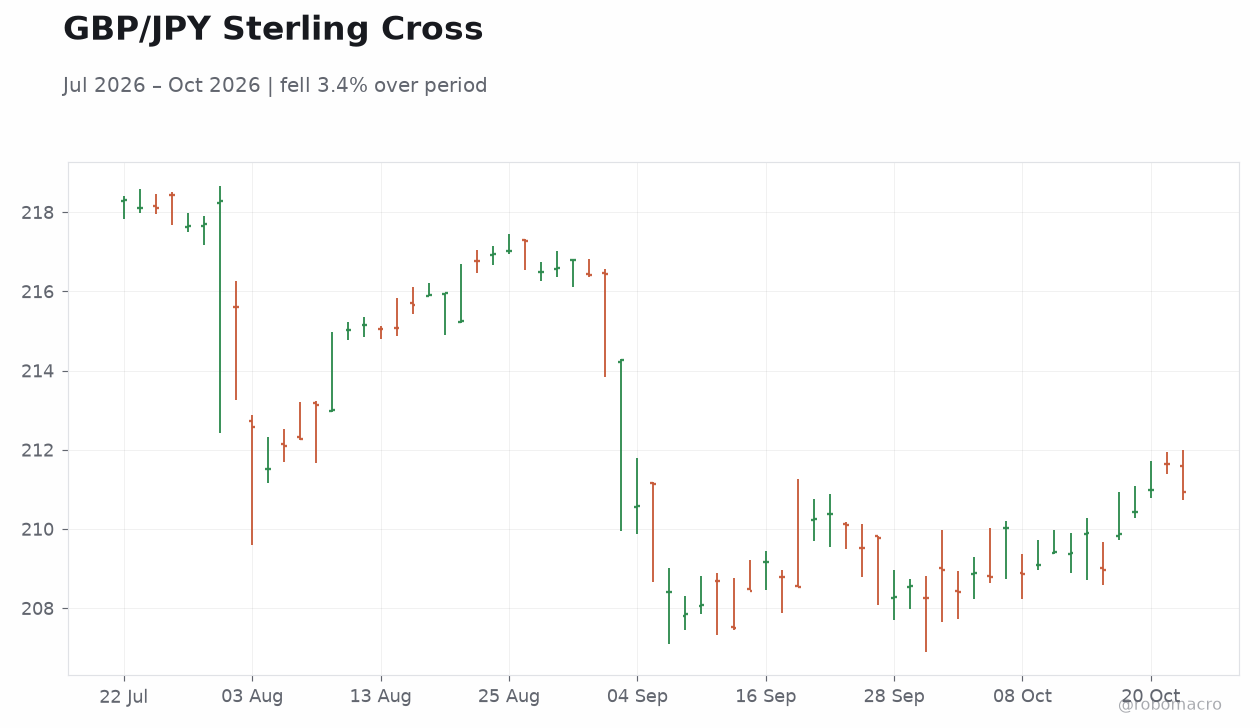
| GBP/JPY | 210.90 | -0.35% |
| Brent Crude | 111.25 | +2.23% |
| Gold | 4,085.50 | -1.55% |
| UK Nat Gas | 2.76 | -0.97% |
| Bitcoin | 82,725.79 | -0.26% |
| UK 2Y Gilt | 4.72% | +1 bp |
| UK 10Y Gilt | 5.41% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
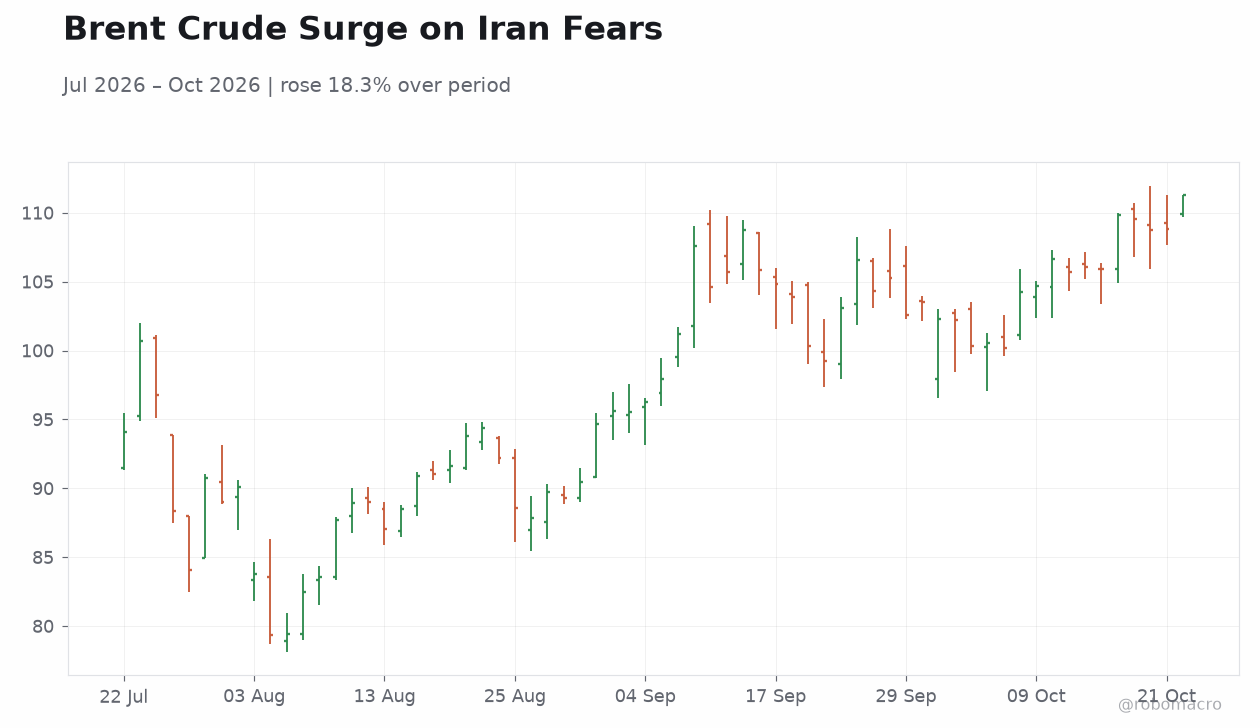 Brent Crude Surge on Iran Fears | Type: market_hloc | Brent Crude (USD): 111.3 (2026-10-22) | Range: 79.36–111.3 | Trend(6pt): 94.07,87.07,96.28,102.6,108.8,111.3
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- UK CPI jumped to 3.50% YoY in September, topping forecasts and cementing expectations of a November Bank of England rate rise.
- Sterling extended gains on the inflation print while the 10-year gilt yield climbed 7 bp to 5.41%, steepening the curve.
- Brent crude surged 2.23% to $111.25 on Iran-war supply fears, feeding the energy-led inflation impulse.
Yesterday's Recap
UK CPI printed at 3.50% YoY for September, above consensus and a sharp acceleration driven by energy and fuel costs linked to the Iran conflict. Public borrowing also topped forecasts, a twin blow landing just ahead of next week's Budget. Markets responded decisively: GBP/USD rose 0.25% to 1.34 and the 10-year gilt yield added 7 bp to 5.41%, while the 2-year edged 1 bp higher to 4.72%.
The FTSE 100 firmed 0.19% to 10,752.88 and the FTSE 250 gained 0.31% to 24,439.80, equities shrugging off higher rates. Brent crude jumped 2.23% to $111.25, the dominant driver of the inflation surprise, while gold fell 1.55% to $4,085.50 as real yields rose. UK natural gas slipped 0.97% to 2.76.
The Day Ahead
The calendar is light on Thursday, with no top-tier UK data scheduled, leaving markets to consolidate the inflation shock and position for next week's Budget and the November MPC. Attention turns to gilt supply dynamics and any BoE speaker commentary for signals on the pace of tightening. Sterling crosses remain the key tell, with GBP/JPY at 210.90 and GBP/EUR at 1.19 reflecting the rate differential.
Traders will watch whether the 10-year gilt holds above 5.40% or extends its steepening. With no domestic prints to distract, global risk sentiment and oil headlines will dominate intraday direction.
Other Economic Notes
The combination of 3.50% CPI and above-forecast borrowing places fiscal and monetary policy on a collision course ahead of the Budget. Higher gilt yields raise debt-servicing costs precisely as the Chancellor faces constrained headroom, complicating any pre-election giveaways. The BoE's Bank Rate sits at 3.73%, and with inflation running well above target the real policy stance is negative, arguing for further tightening.
Fuel-driven inflation is the crux: if Brent stays near $111, second-round effects into wages and services become the MPC's central concern. Housing and retail activity remain vulnerable to the renewed rate-rise narrative.