UK Macro Daily(Beta Mode)
UK Inflation Data Bolsters BoE Hike Odds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
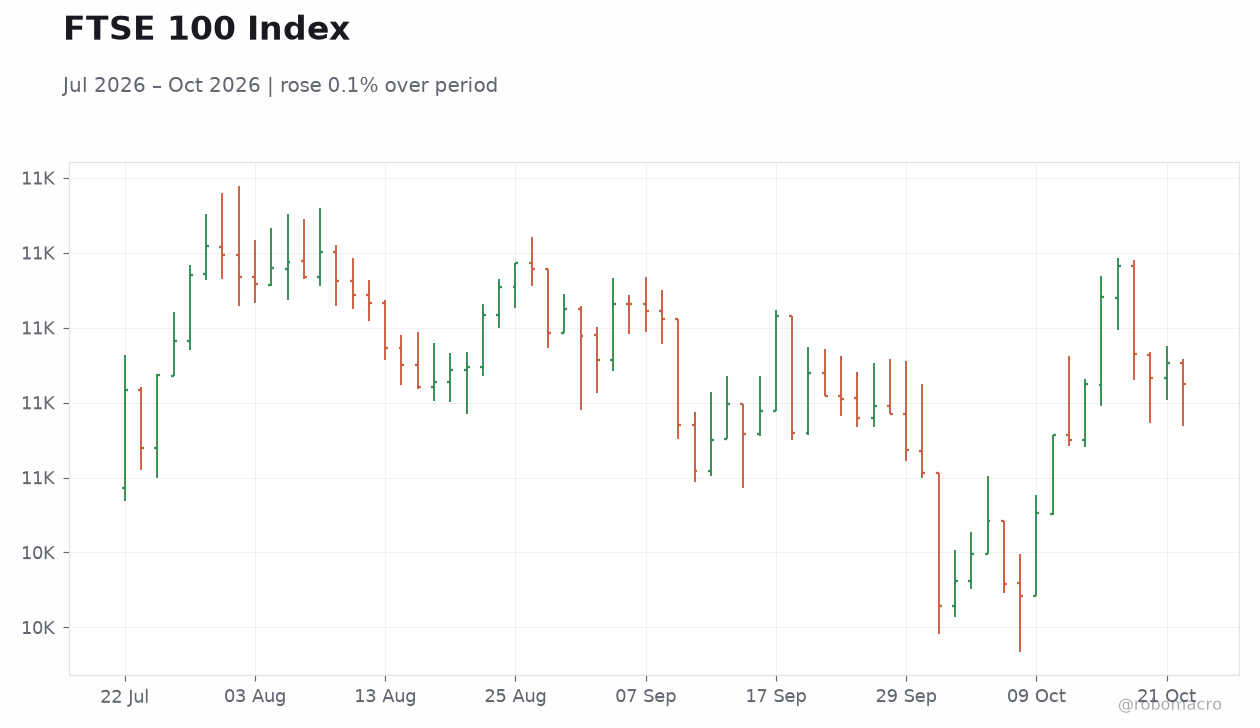
| FTSE 100 | 10,725.03 | -0.26% |
| FTSE 250 | 24,211.70 | -0.93% |
| GBP/USD | 1.34 | -0.06% |
| GBP/EUR | 1.19 | +0.13% |
| GBP/JPY | 210.03 | -0.84% |
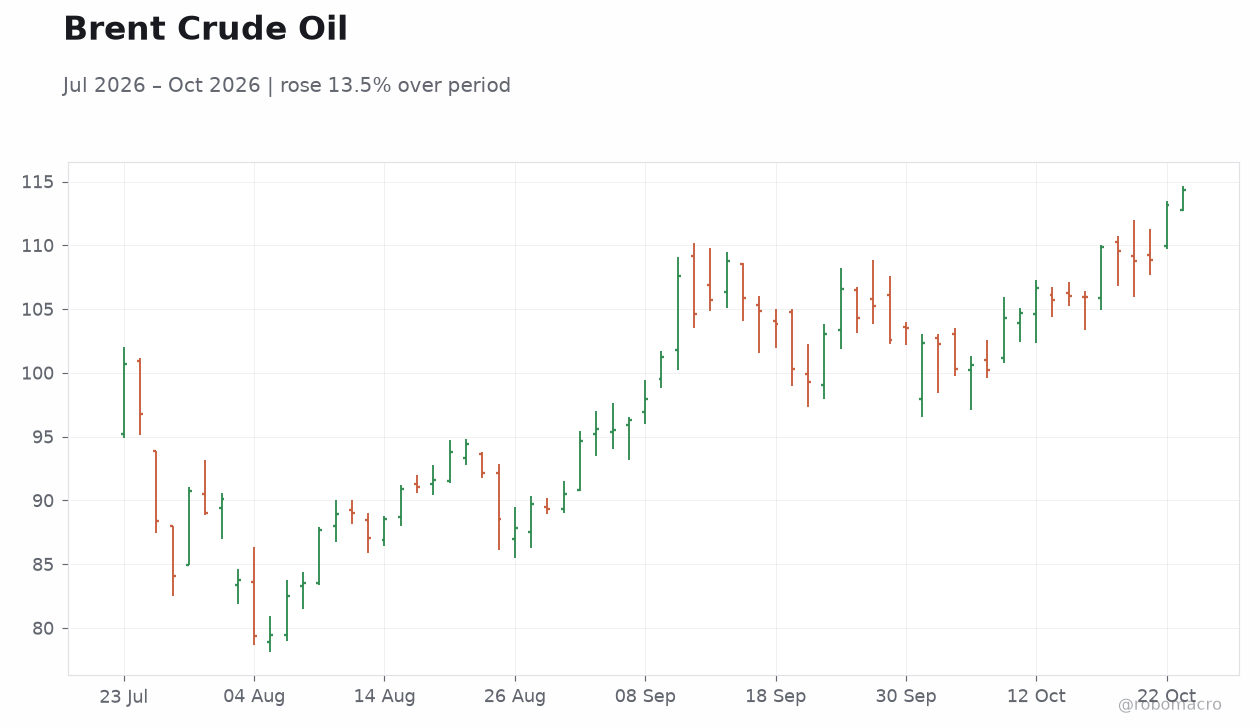
| Brent Crude | 114.14 | +0.86% |
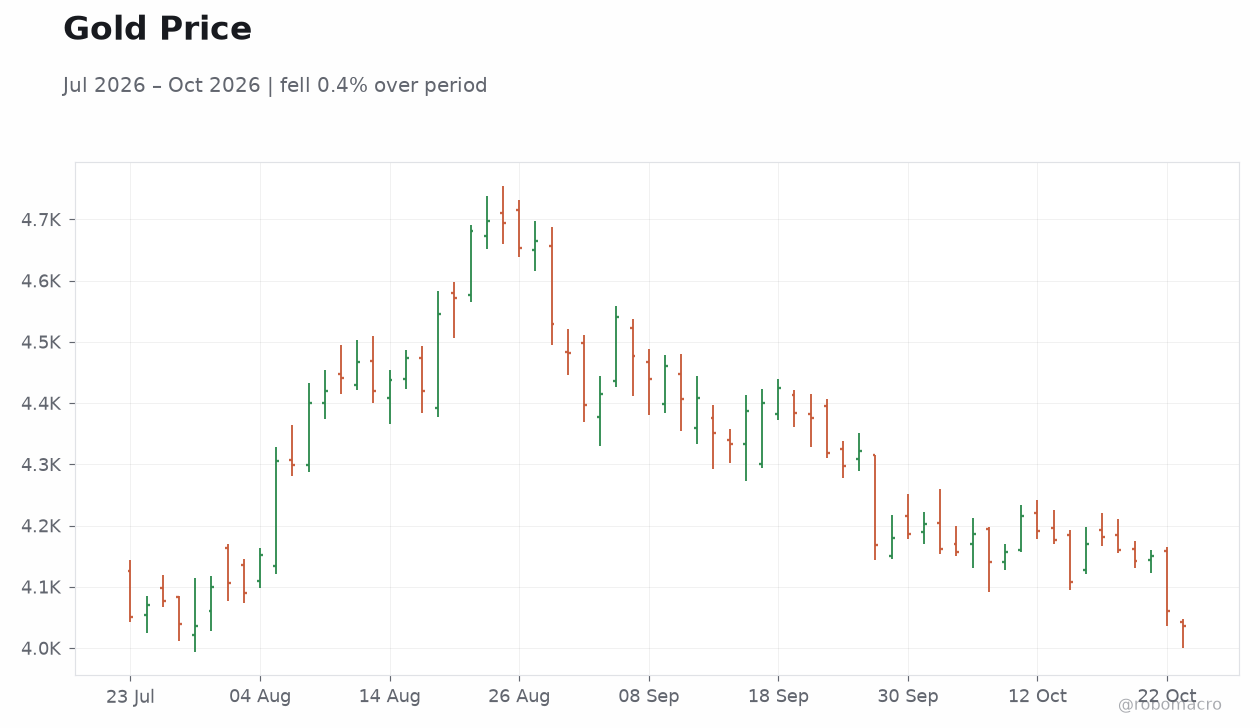
| Gold | 4,037.00 | -0.58% |
| UK Nat Gas | 2.74 | -2.11% |
| Bitcoin | 81,660.97 | -2.80% |
| UK 2Y Gilt | 4.71% | -1 bp |
| UK 10Y Gilt | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
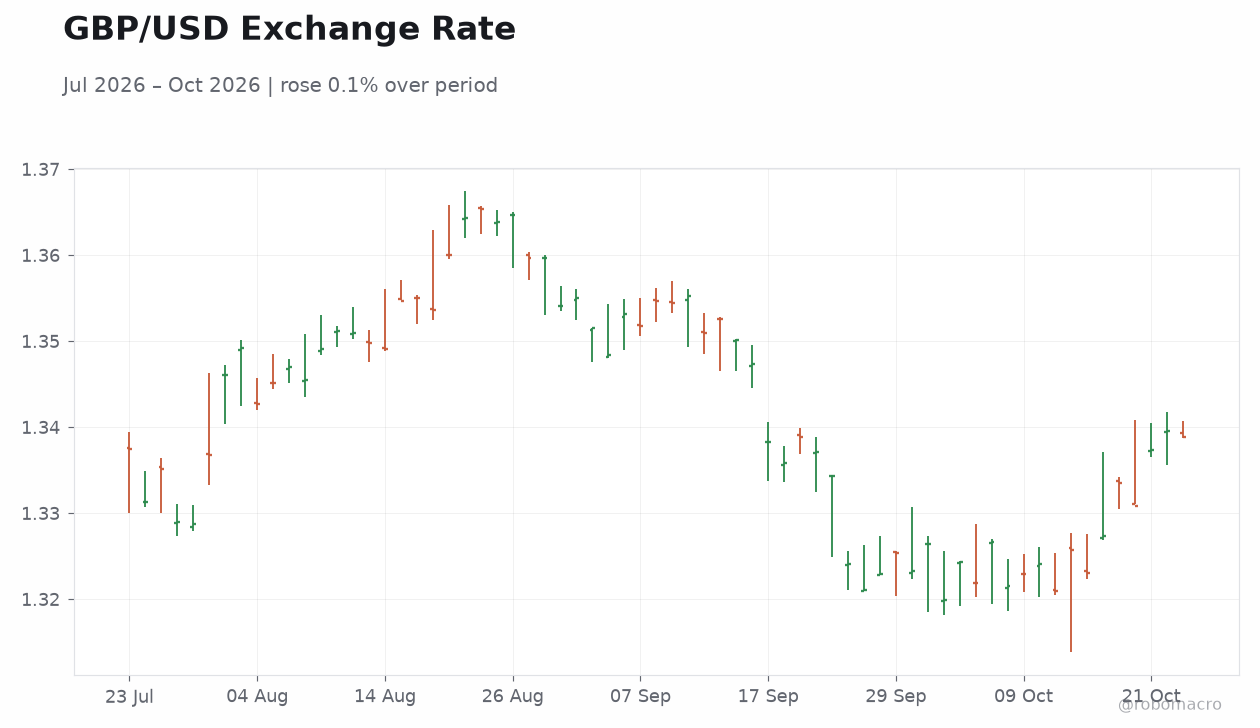 GBP/USD Exchange Rate | Type: market_hloc | Rate: 1.339 (2026-10-23) | Range: 1.32–1.365 | Trend(6pt): 1.338,1.349,1.352,1.325,1.337,1.339
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Firm UK inflation and wage growth lift November BoE hike odds
- FTSE 100 and FTSE 250 decline as gilt yields edge lower
- Sterling mixed with GBP/USD slipping while GBP/EUR advances
Yesterday's Recap
UK markets digested recent inflation data that printed firmer than expected, keeping the case for Bank of England tightening alive. The FTSE 100 fell 0.26 percent to 10,725.03 while the FTSE 250 dropped 0.93 percent to 24,211.70, reflecting caution across mid-cap names. Sterling traded mixed, with GBP/USD easing 0.06 percent to 1.34 and GBP/JPY declining 0.84 percent to 210.03, though GBP/EUR rose 0.13 percent to 1.19.
The UK 2Y gilt yield declined one basis point to 4.71 percent, signalling modest duration demand. Brent crude advanced 0.86 percent to 114.14 dollars per barrel while UK natural gas fell 2.11 percent. Gold slipped 0.58 percent to 4,037.00 dollars per ounce.
Bitcoin declined 2.80 percent amid risk-off flows. Recent wage growth acceleration added to the narrative that labour-market pressures remain intact despite the 4.70 percent unemployment rate recorded in July. Public-finance pressures are prompting renewed discussion of potential tax changes on banks, which could affect lending margins and credit conditions.
The Day Ahead
With the economic calendar empty, attention turns to Bank of England communications and any follow-up analyst notes on the September CPI print of 3.50 percent year-on-year. Market participants will monitor sterling crosses for signs that the recent inflation surprise is altering rate expectations. Gilt trading desks are expected to focus on technical support around the 4.71 percent level in the two-year sector.
Broader equity sentiment may hinge on overnight moves in US indices and any updates on global risk appetite. Housing and retail-sales data are not scheduled, leaving wage and inflation prints as the dominant recent anchors for policy pricing. The combination of resilient wage growth and sticky inflation at 3.50 percent has narrowed the window for near-term policy easing.
Other Economic Notes
Labour-market data continue to show unemployment at 4.70 percent, yet the pace of earnings gains suggests underlying capacity constraints remain. Gilt-market liquidity has stayed orderly, with the two-year yield holding near 4.71 percent despite the modest daily decline. These factors collectively point to a higher-for-longer policy path than markets had priced earlier in the month.
↓ p.2