UK Macro Daily(Beta Mode)
CBI Trades Beat, Gilts Diverge Ahead of BoE
Market Snapshot
| Asset | Level | Change |
|---|---|---|
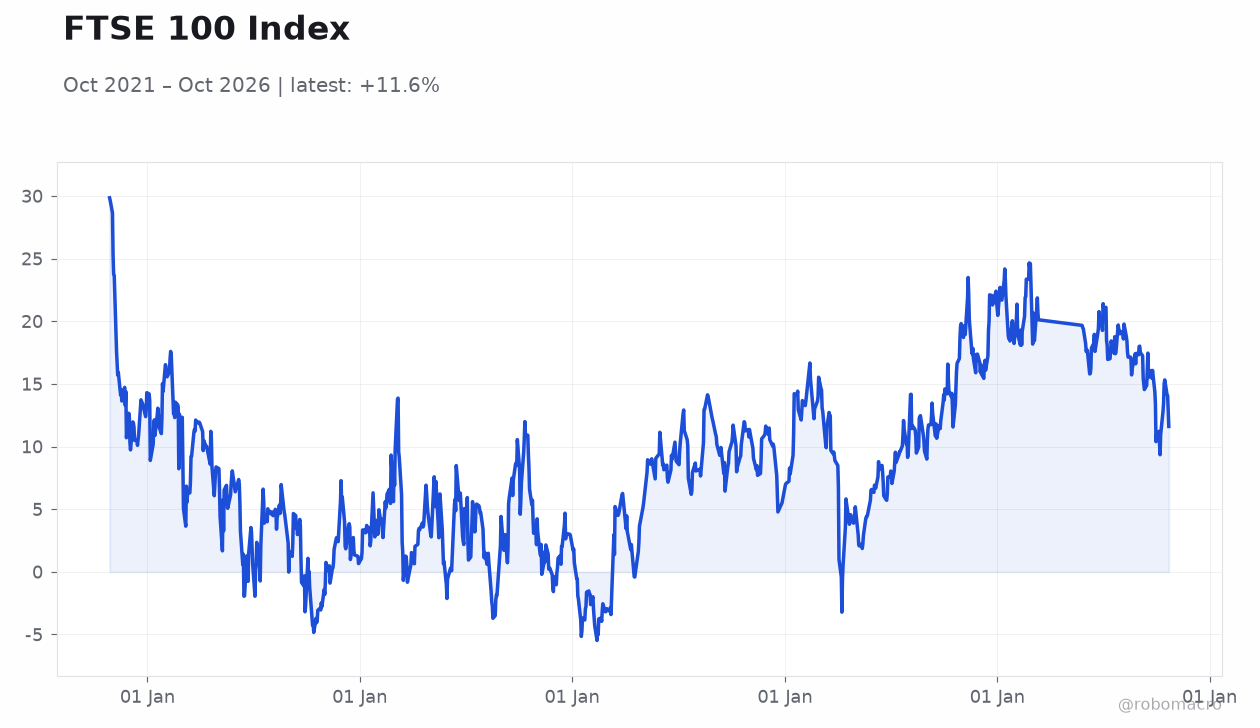
| FTSE 100 | 10,690.40 | -0.32% |
| FTSE 250 | 24,501.30 | +1.09% |
| GBP/USD | 1.33 | -0.34% |
| GBP/EUR | 1.19 | +0.07% |
| GBP/JPY | 210.29 | +0.24% |
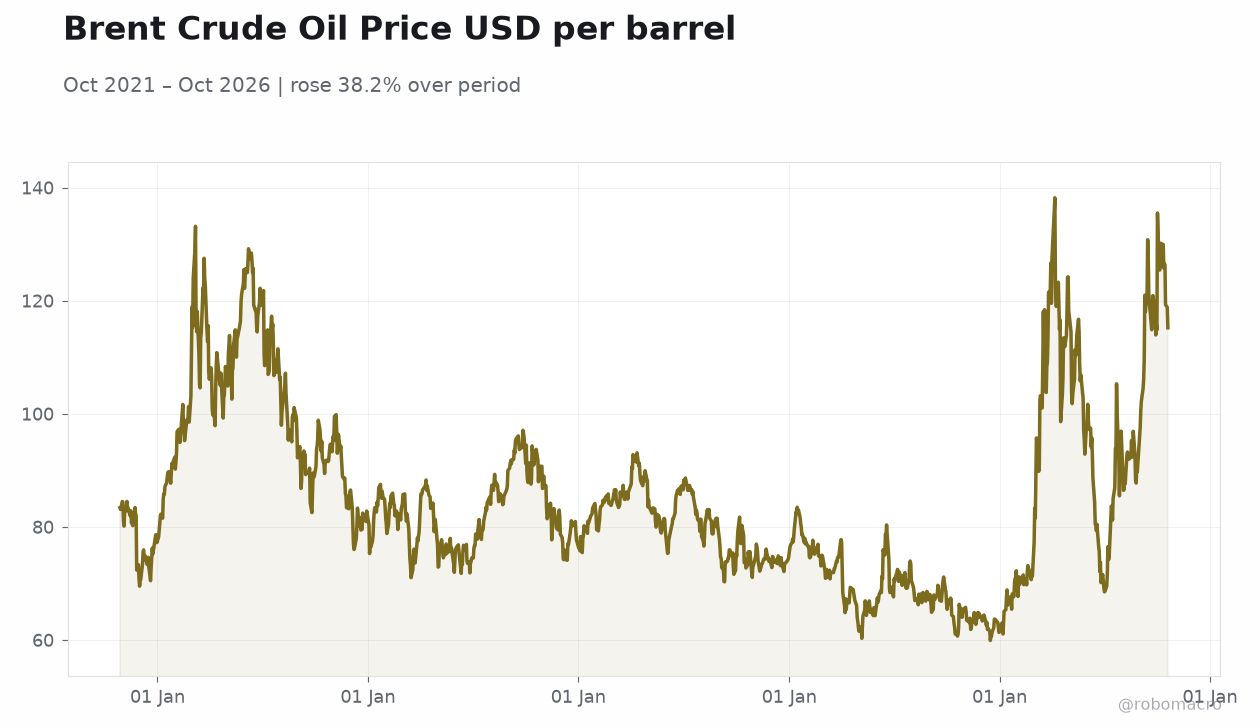
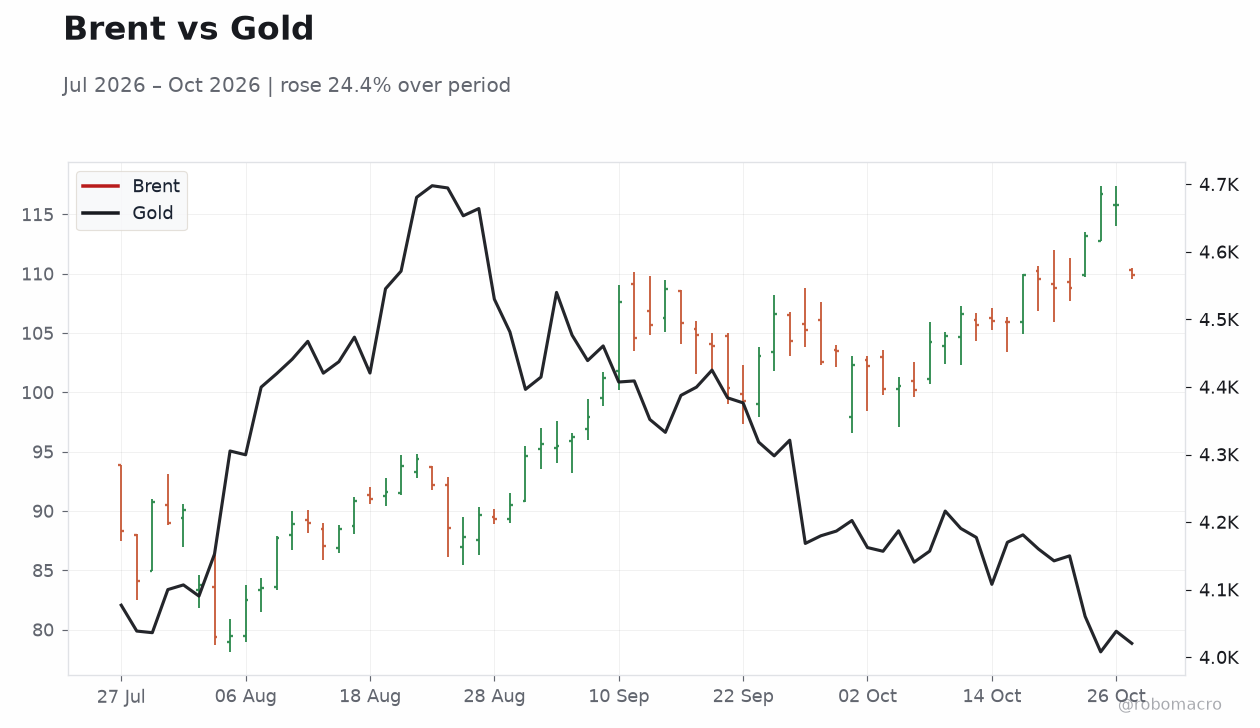
| Brent Crude | 109.86 | -5.14% |
| Gold | 4,023.20 | -0.38% |
| UK Nat Gas | 3.04 | +16.79% |
| Bitcoin | 79,806.35 | -0.27% |
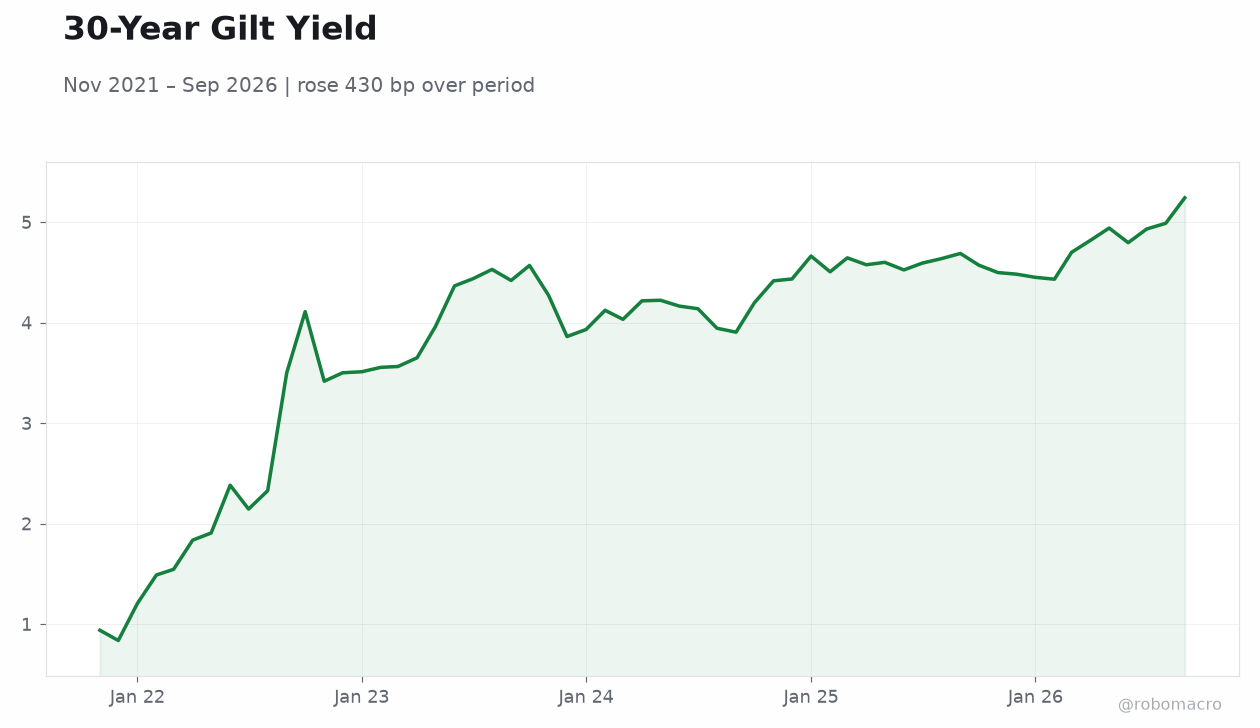
| UK 2Y Gilt | 4.71% | +3 bp |
| UK 10Y Gilt | 5.31% | -6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| CBI Distributive Trades | -55 | -47 | -10 |
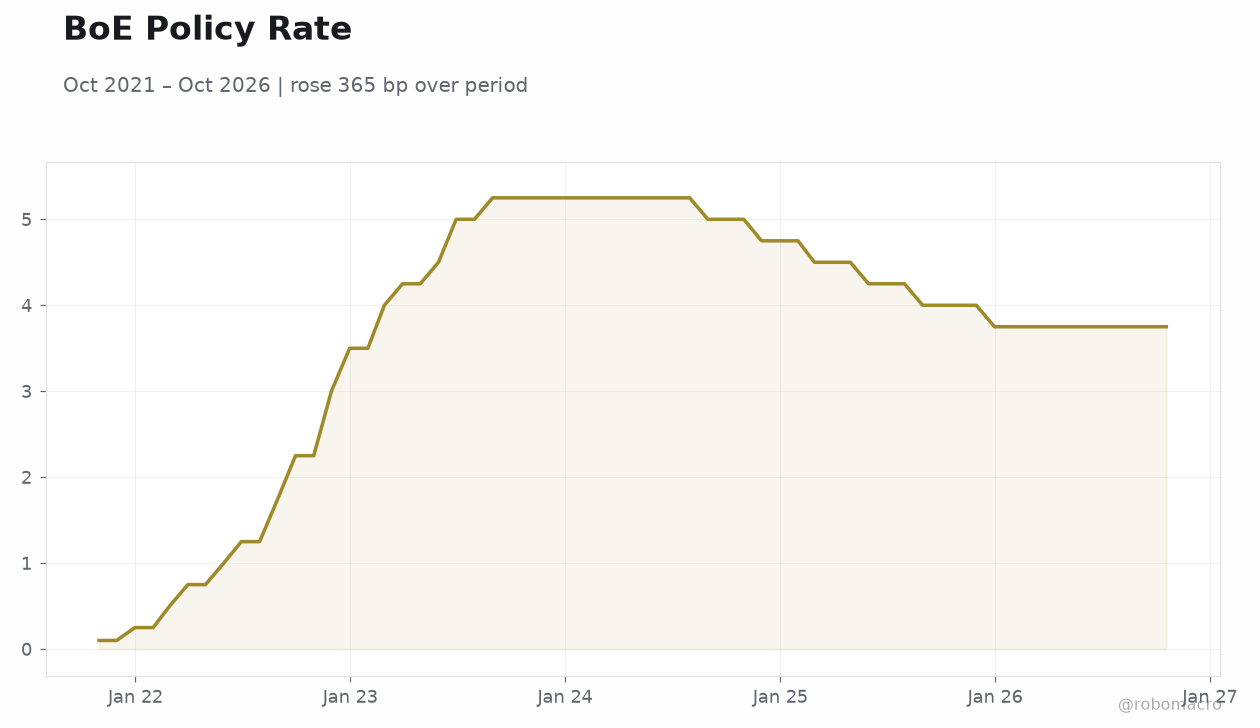 BoE Policy Rate | Type: macro_line | Policy Rate %: 3.75 (2026-10-19) | Range: 0.1–5.25 | Trend(5pt): 0.1,3.5,5.25,4.25,3.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-29) | |||
| BoE Consumer Credit | 2,464m | - | 05:30 |
| Mortgage Approvals | 54,920 | 56,000 | 05:30 |
| Mortgage Lending Level | 4,410m | - | 05:30 |
| Friday (2026-10-30) | |||
| Nationwide Housing Prices Month-over-Month | -0.20 | -0.20 | 03:00 |
| Nationwide Housing Prices Year-over-Year | 0.80 | - | 03:00 |
| BoE Mills Speech | - | - | 05:00 |
- CBI Distributive Trades printed -10, sharply above consensus of -47.
- FTSE 250 rose 1.09% while GBP/USD fell 0.34% to 1.33.
- UK 10-year gilt yield eased 6 bp to 5.31% as 2-year rose 3 bp to 4.71%.
Yesterday's Recap
The CBI Distributive Trades survey for October delivered a clear upside surprise, printing at -10 versus the -47 consensus and prior -55. Equity markets showed divergence, with the FTSE 100 declining 0.32% to 10,690.40 while the FTSE 250 advanced 1.09% to 24,501.30. Sterling weakened across majors, with GBP/USD falling 0.34% to 1.33 and GBP/EUR rising only 0.07% to 1.19.
Gilt yields moved in opposite directions, the 2-year rising 3 bp to 4.71% while the 10-year eased 6 bp to 5.31%. Brent crude dropped 5.14% to 109.86 amid broader energy volatility, and UK natural gas surged 16.79% to 3.04. Overall risk sentiment remained contained ahead of the next Bank of England meeting.
The Day Ahead
Attention turns to Thursday’s UK lending data, including BoE Consumer Credit, Mortgage Approvals and Mortgage Lending Level, all due at 05:30 ET. Friday brings the Nationwide House Price Index for October, with the month-over-month reading expected to match the prior -0.2%. Bank of England Deputy Governor Sarah Breeden’s successor Catherine Mills is scheduled to speak at 05:00 ET on Friday, offering potential guidance on policy transmission.
Markets will also monitor any updates on the 5 November MPC meeting, where the committee is expected to hold the Bank Rate at 3.75%. Housing and credit prints will provide fresh signals on consumer resilience ahead of the November inflation report.
Other Economic Notes
UK CPI stood at 3.50% year-over-year as of September, while unemployment reached 4.70% in July, underscoring a labour market that has cooled without collapsing. Mortgage approvals and consumer credit figures due this week will test whether recent rate cuts are feeding through to household demand. Broader themes include the Bank of England’s ongoing review of insurance sector gaps as a potential systemic risk and its scrutiny of Revolut’s product approvals amid expanding UK lending.
These developments highlight regulators’ focus on financial stability even as growth remains subdued.
Global Macro News
Escalating Houthi attacks on Saudi Arabia have shifted market attention toward non-oil economic risks in the Gulf, with potential knock-on effects for UK energy imports and inflation. ↓ p.2