UK Macro Daily(Beta Mode)
Gilt Pressure Builds Ahead of BoE
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,686.54 | -0.75% |
| FTSE 250 | 24,716.40 | +0.88% |
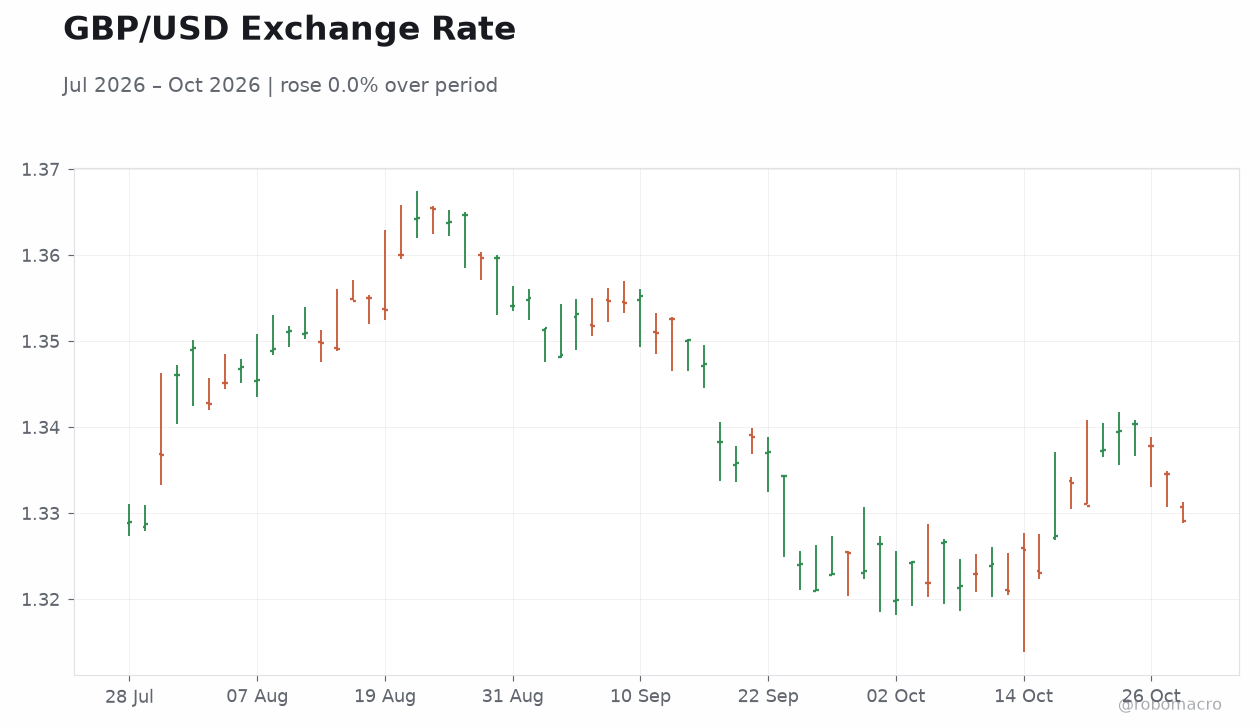
| GBP/USD | 1.33 | -0.41% |
| GBP/EUR | 1.19 | +0.05% |
| GBP/JPY | 209.77 | -0.20% |
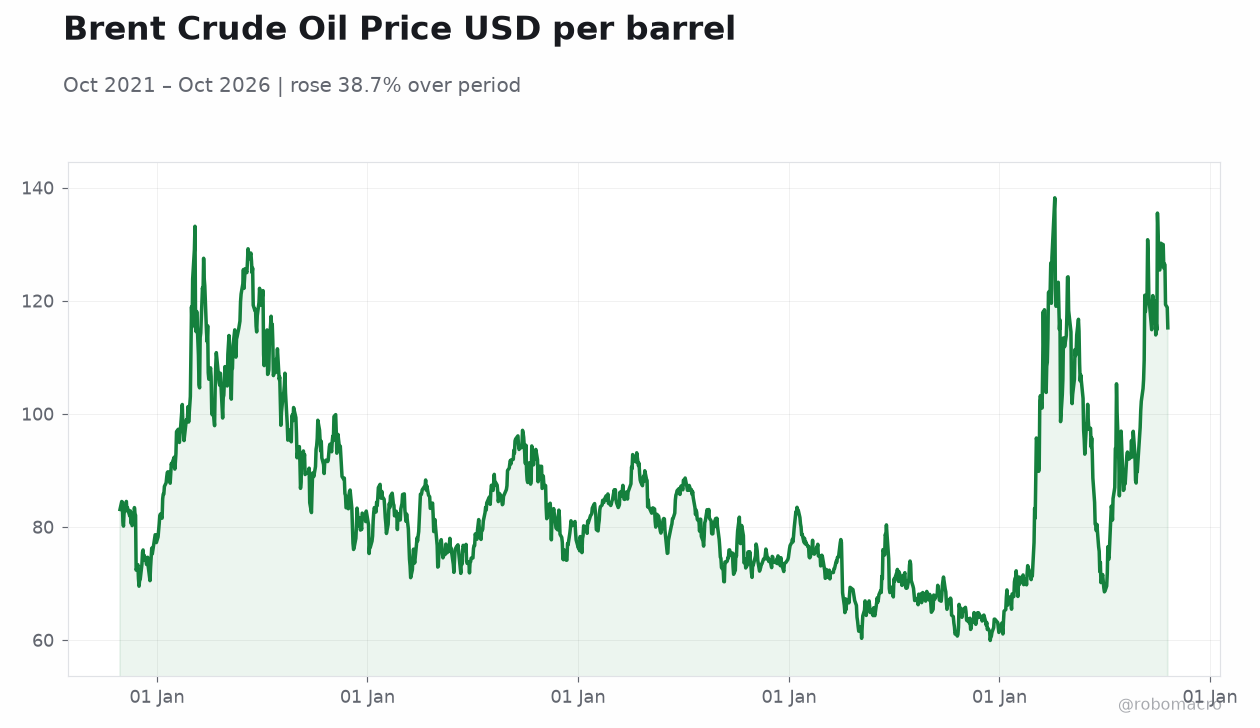
| Brent Crude | 111.26 | -2.30% |
| Gold | 4,046.70 | -0.68% |
| UK Nat Gas | 3.05 | +13.05% |
| Bitcoin | 80,804.41 | +1.00% |
| UK 2Y Gilt | 4.73% | +2 bp |
| UK 10Y Gilt | 5.35% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| CBI Distributive Trades | -55 | -47 | -10 |
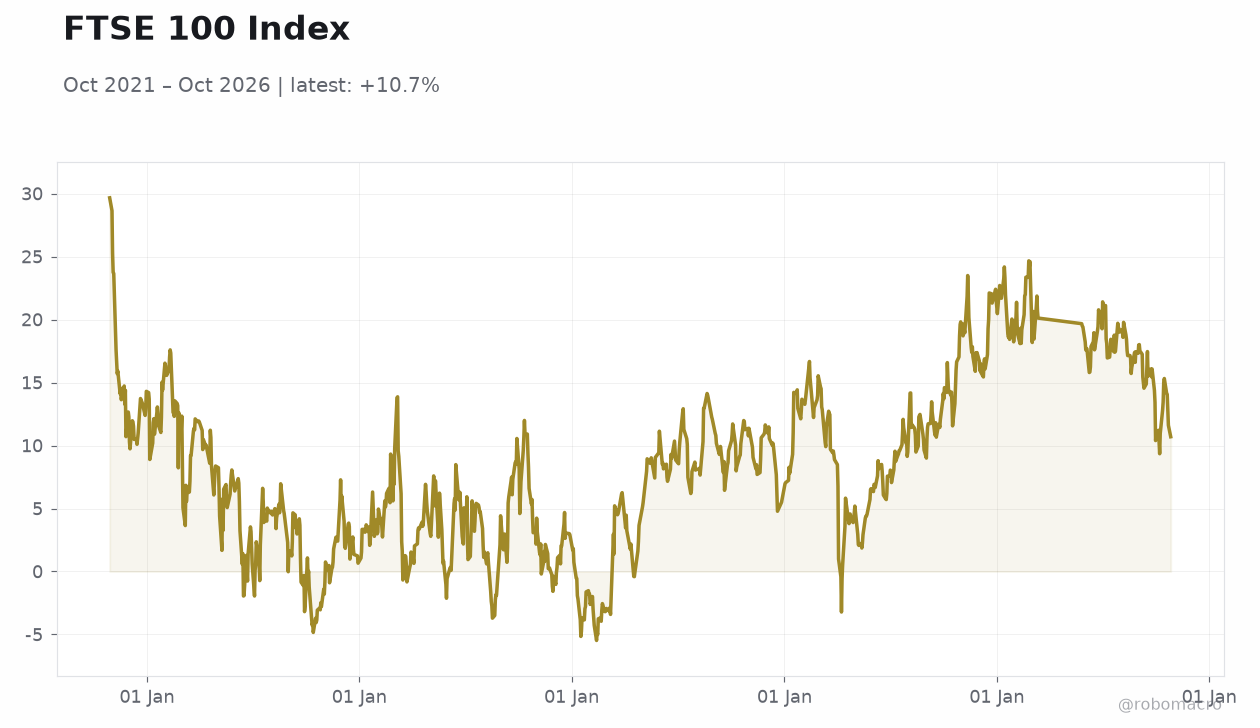 FTSE 100 Index | Type: macro_line | FTSE 100 Index: 10.7 (2026-10-27) | Range: -5.477–29.66 | Trend(6pt): 29.66,0.9848,-3.674,7.981,11.61,10.7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-29) | |||
| BoE Consumer Credit | 2,464m | - | 05:30 |
| Mortgage Approvals | 54,920 | 56,000 | 05:30 |
| Mortgage Lending Level | 4,410m | - | 05:30 |
| Friday (2026-10-30) | |||
| Nationwide Housing Prices Month-over-Month | -0.20 | -0.20 | 03:00 |
| Nationwide Housing Prices Year-over-Year | 0.80 | - | 03:00 |
| BoE Mills Speech | - | - | 05:00 |
- CBI distributive trades rebounded sharply to -10 from -55, beating consensus of -47, signalling retail conditions improving faster than expected
- Sterling slipped 0.41% against the dollar to 1.33 while FTSE 250 outperformed, gaining 0.88% as mid-caps defied blue-chip weakness
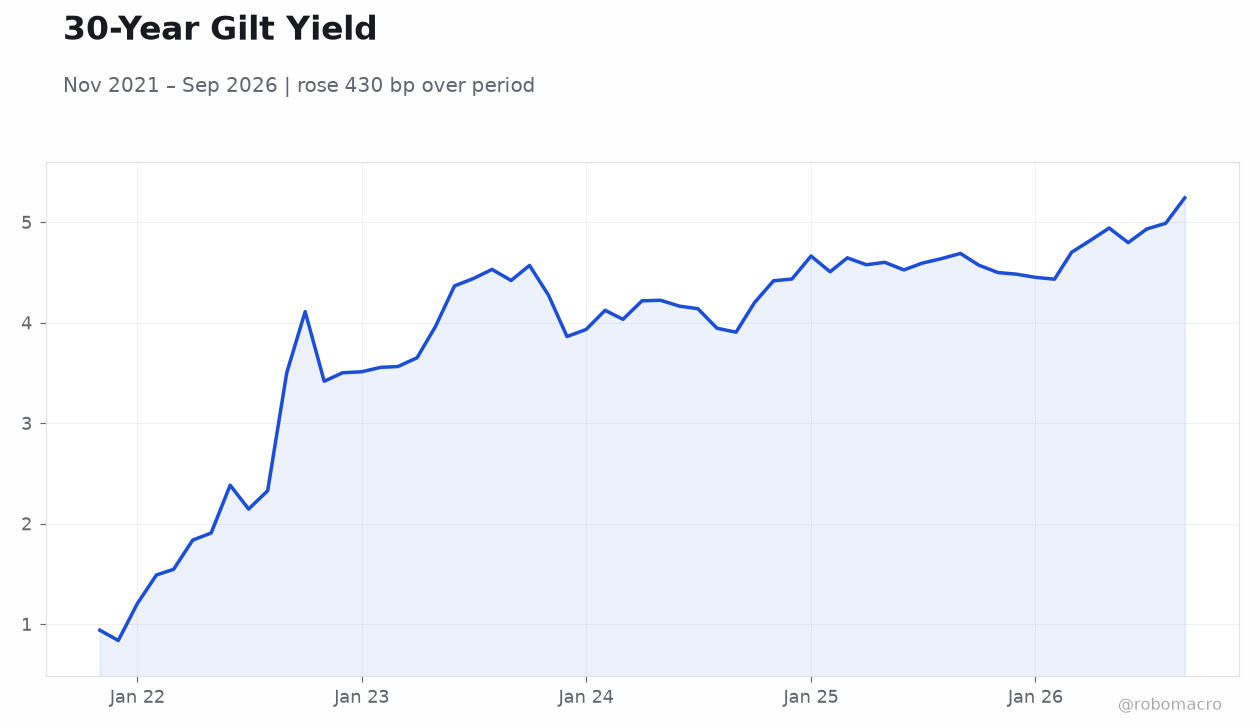
- Gilt yields pushed higher with the 10-year at 5.35% (+4bp) and 2-year at 4.73% (+2bp), keeping pressure on the fiscal outlook ahead of the Autumn Budget
Yesterday's Recap
The CBI Distributive Trades survey printed at -10 for October, a dramatic improvement from the prior -55 and comfortably ahead of the -47 consensus, suggesting retailers are seeing demand stabilise after a prolonged slump. Despite that encouraging survey, gilts sold off with the 10-year yield rising 4bp to 5.35% and the 2-year adding 2bp to 4.73%, reflecting persistent term premium concerns and heavy issuance expectations. Sterling weakened against the dollar, falling 0.41% to 1.33, though it edged up 0.05% versus the euro to 1.19 and slipped 0.20% against the yen to 209.77.
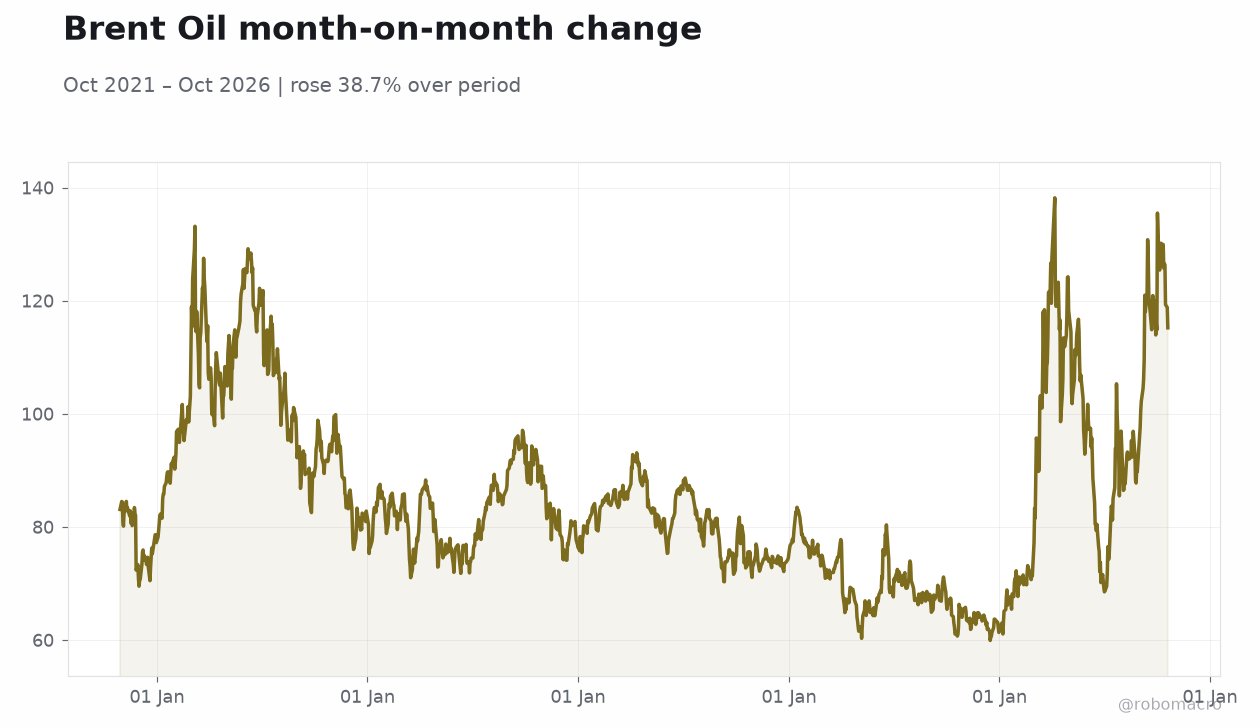
Equity markets diverged sharply: the FTSE 100 fell 0.75% to 10,686.54 while the domestically-focused FTSE 250 rallied 0.88% to 24,716.40, pointing to rotation into UK-facing names. Brent crude dropped 2.30% to $111.26, offering some relief on input costs, while UK natural gas surged 13.05% to 3.05, a reminder that energy volatility remains a live inflation risk. Gold eased 0.68% to $4,046.70 and Bitcoin gained 1.00% to $80,804.41.
The Day Ahead
Attention turns to Thursday's money and credit data, with mortgage approvals due at 05:30 ET, where consensus looks for 56,000 against a prior 54,920, alongside BoE consumer credit and mortgage lending figures for September. These releases will be scrutinised for evidence that housing activity is holding up despite elevated borrowing costs and stretched affordability. Friday brings the Nationwide house price survey at 03:00 ET, with month-over-month consensus at -0.2%, matching the prior reading, and the year-over-year series previously at 0.8%.
Later Friday, BoE's Mills delivers a speech at 05:00 ET, a high-impact event that markets will parse for signals on the policy path ahead of the November 5 MPC decision. With no top-tier releases today, positioning flows and Budget speculation are likely to dominate intraday price action.
Other Economic Notes
The UK economy enters the Autumn Budget period on fragile footing, with CPI at 3.50% and unemployment at 4.70%, a combination that constrains both fiscal and monetary room for manoeuvre. ↓ p.2