UK Macro Daily(Beta Mode)
Budget Calms Gilts as Borrowing Cools
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,722.07 | +0.26% |
| FTSE 250 | 24,674.20 | +0.14% |
| GBP/USD | 1.34 | +0.45% |
| GBP/EUR | 1.20 | +0.13% |
| GBP/JPY | 210.74 | +0.20% |
| Brent Crude | 112.10 | -2.42% |
| Gold | 4,004.00 | -0.68% |
| UK Nat Gas | 2.90 | -1.83% |
| Bitcoin | 78,052.84 | -3.96% |
| UK 2Y Gilt | 4.77% | +3 bp |
| UK 10Y Gilt | 5.32% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| CBI Distributive Trades | -55 | -47 | -10 |
| Autumn Budget | - | - | "" |
| Autumn Forecast Statement | - | - | "" |
| BoE Consumer Credit | 2,464m | 2,200m | 1,914m |
| Mortgage Approvals | 54,920 | 54,000 | 53,440 |
| Mortgage Lending Level | 4,410m | 4,200m | 3,870m |
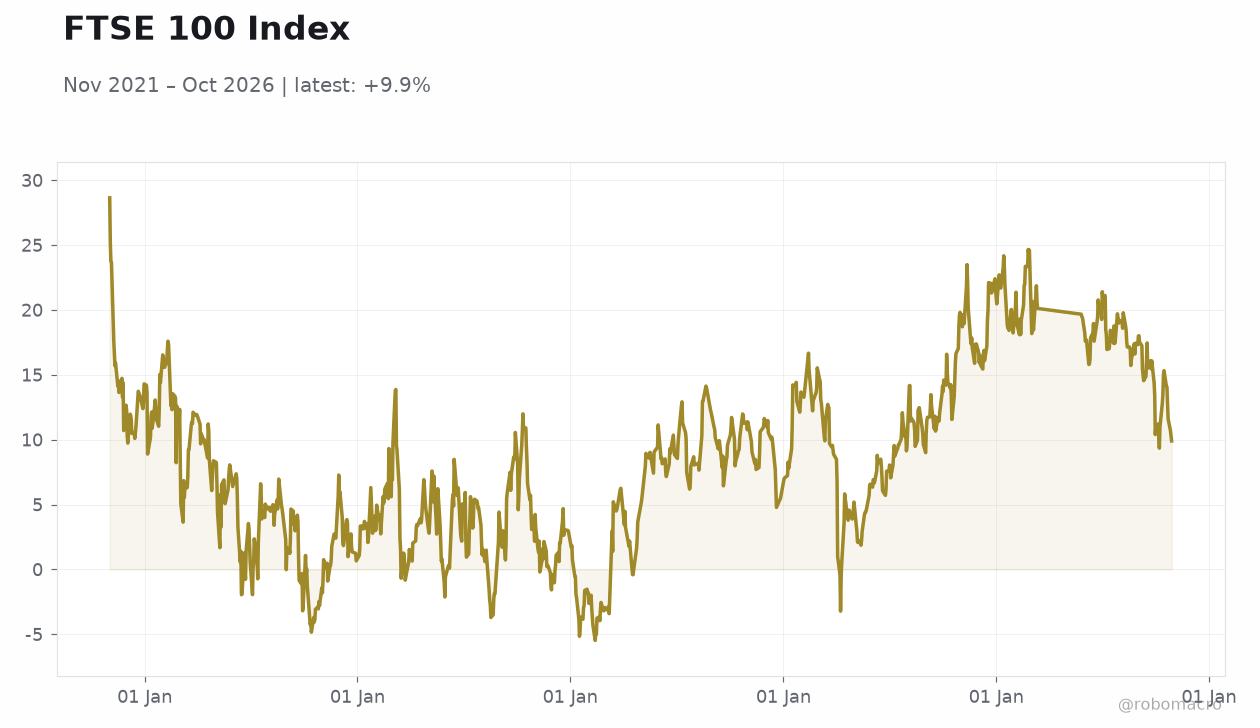 FTSE 100 Index | Type: macro_line | FTSE 100 Index: 9.901 (2026-10-29) | Range: -5.477–28.64 | Trend(6pt): 28.64,2.398,-4.28,7.057,10.7,9.901
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Nationwide Housing Prices Month-over-Month | -0.20 | -0.10 | 03:00 |
| Nationwide Housing Prices Year-over-Year | 0.80 | 0.60 | 03:00 |
| BoE Mills Speech | - | - | 05:00 |
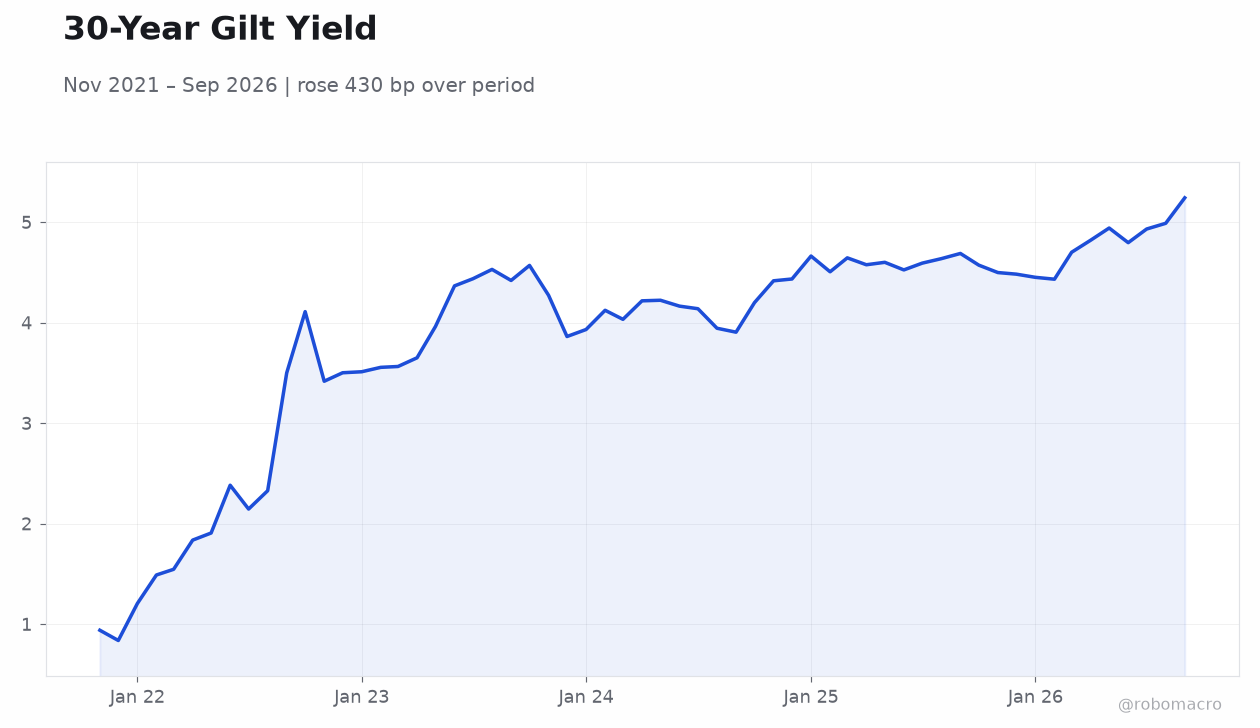
- Autumn Budget and Forecast Statement delivered; 10Y gilt at 5.32% (-1 bp) while 2Y rose 3 bp to 4.77%
- September mortgage approvals fell to 53,440 and consumer credit slowed to £1.914bn, signalling household caution
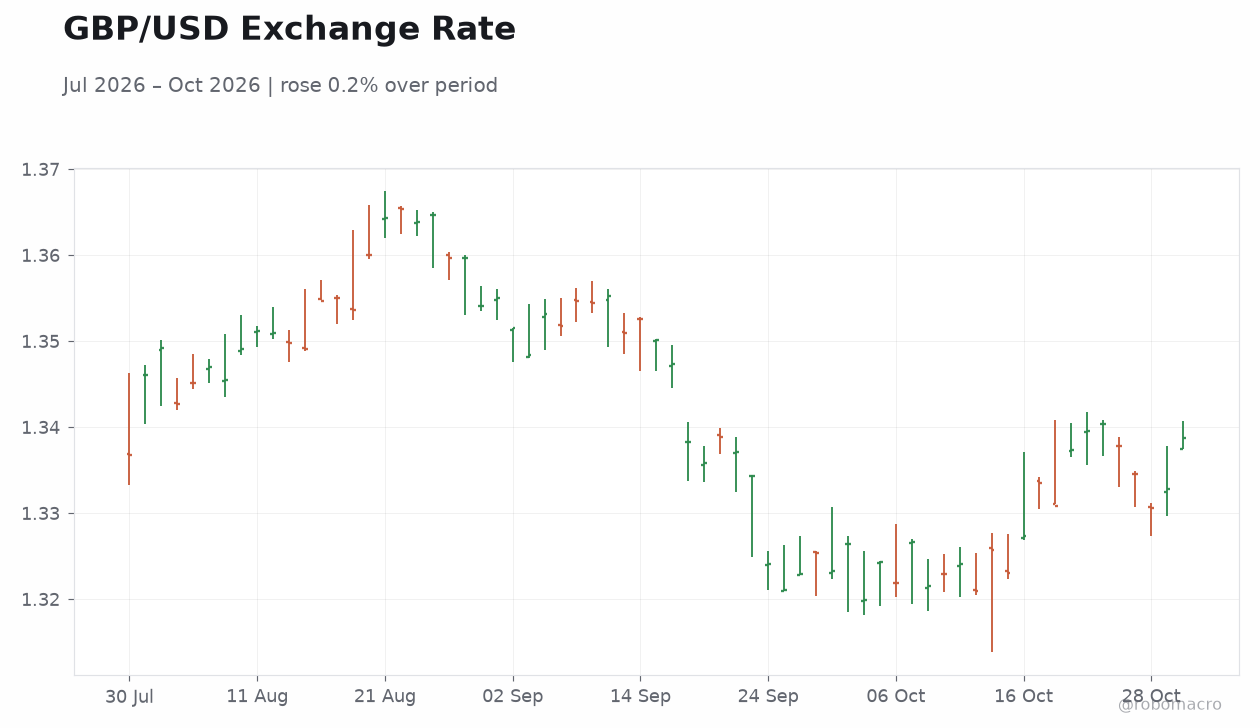
- Sterling firmer at 1.34 versus USD; BoE Mills speech and Nationwide house prices due today ahead of the 5 November MPC
Yesterday's Recap
The Autumn Budget and accompanying Forecast Statement dominated Wednesday's session, and the gilt market's muted reaction — 10-year yields easing 1 bp to 5.32% while 2-year yields rose 3 bp to 4.77% — suggests the fiscal package landed broadly within expectations, though the curve steepened modestly as markets digested the medium-term borrowing profile. Thursday's money and credit data painted a softer household picture: mortgage approvals came in at 53,440 against consensus of 54,000, mortgage lending slowed to £3.87bn versus a £4.2bn forecast, and consumer credit decelerated to £1.914bn from £2.464bn previously. The CBI Distributive Trades survey, released earlier in the week, printed at -10, a sharp improvement on the -55 prior reading and comfortably better than the -47 consensus, hinting at stabilisation in retail activity.
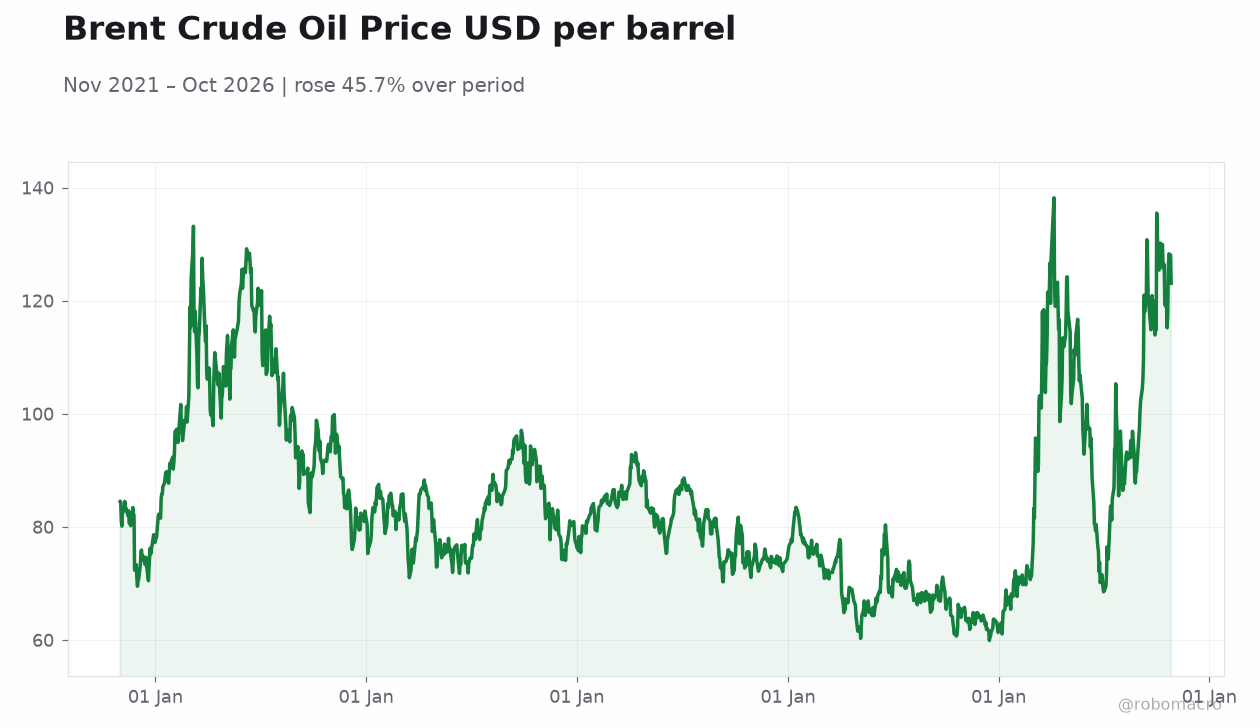
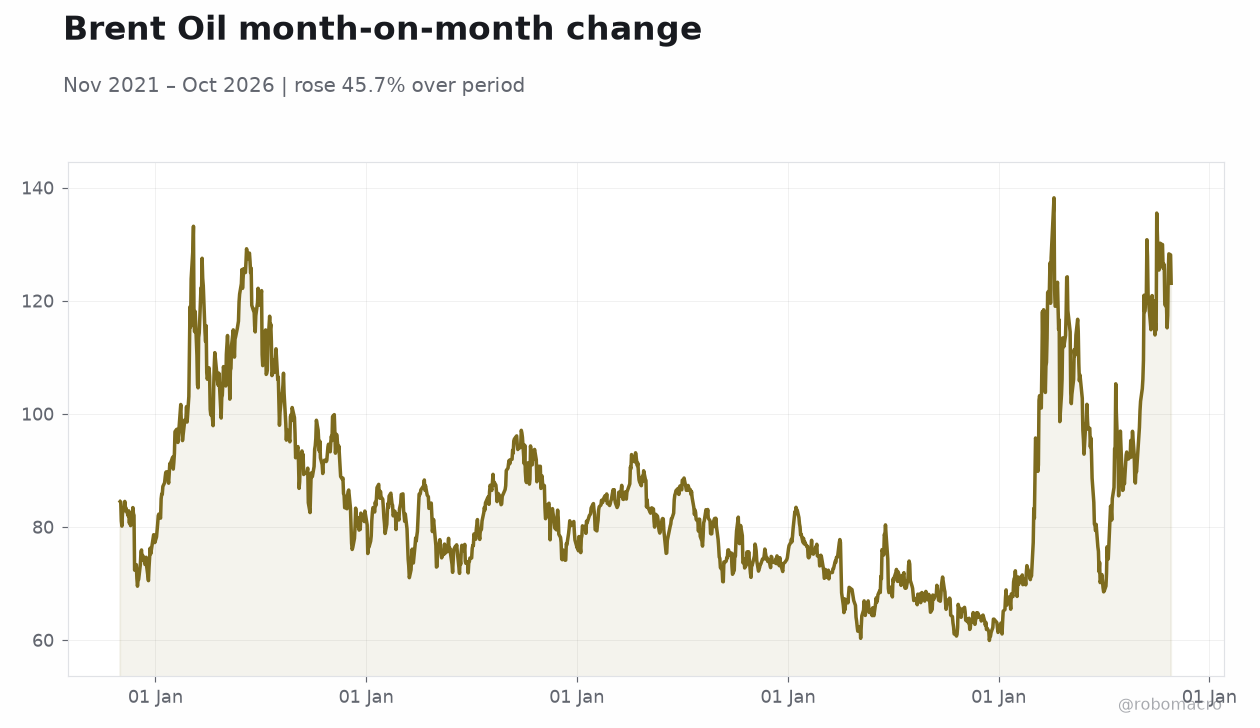
Equities were firm, with the FTSE 100 up 0.26% to 10,722.07 and the FTSE 250 adding 0.14% to 24,674.20. Sterling strengthened across the board, GBP/USD rising 0.45% to 1.34 and GBP/EUR up 0.13% to 1.20. Commodities were the outlier, with Brent crude down 2.42% to $112.10 and UK natural gas off 1.83%.
The Day Ahead
Nationwide housing price data for October are due at 03:00 ET, with consensus pointing to a 0.1% monthly decline and annual growth slowing to 0.6% from 0.8% — a soft print would reinforce the picture of cooling housing activity implied by yesterday's mortgage figures. BoE MPC member Mills speaks at 05:00 ET, a high-impact event that will be scrutinised for signals ahead of the 5 November policy decision, particularly on the inflation persistence debate and the pace of balance-sheet reduction. No further UK releases are scheduled for the remainder of the week, leaving month-end flows and gilt supply dynamics to shape positioning.
With the Budget now digested, attention rotates squarely to next week's MPC meeting and the accompanying Monetary Policy Report.
Other Economic Notes
The Budget's market reception — calm rather than celebratory — reflects a fiscal path that avoids near-term disruption but, per early commentary, stores up pressure for 2027, with the bank tax increase drawing criticism from Lloyds' leadership as unhelpful to growth. ↓ p.2