UK Macro Daily(Beta Mode)
BoE Hike Bets Build Ahead of Thursday Decision
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,729.80 | +0.07% |
| FTSE 250 | 24,453.40 | -0.89% |
| GBP/USD | 1.34 | +0.15% |
| GBP/EUR | 1.20 | +0.11% |
| GBP/JPY | 211.37 | +0.13% |
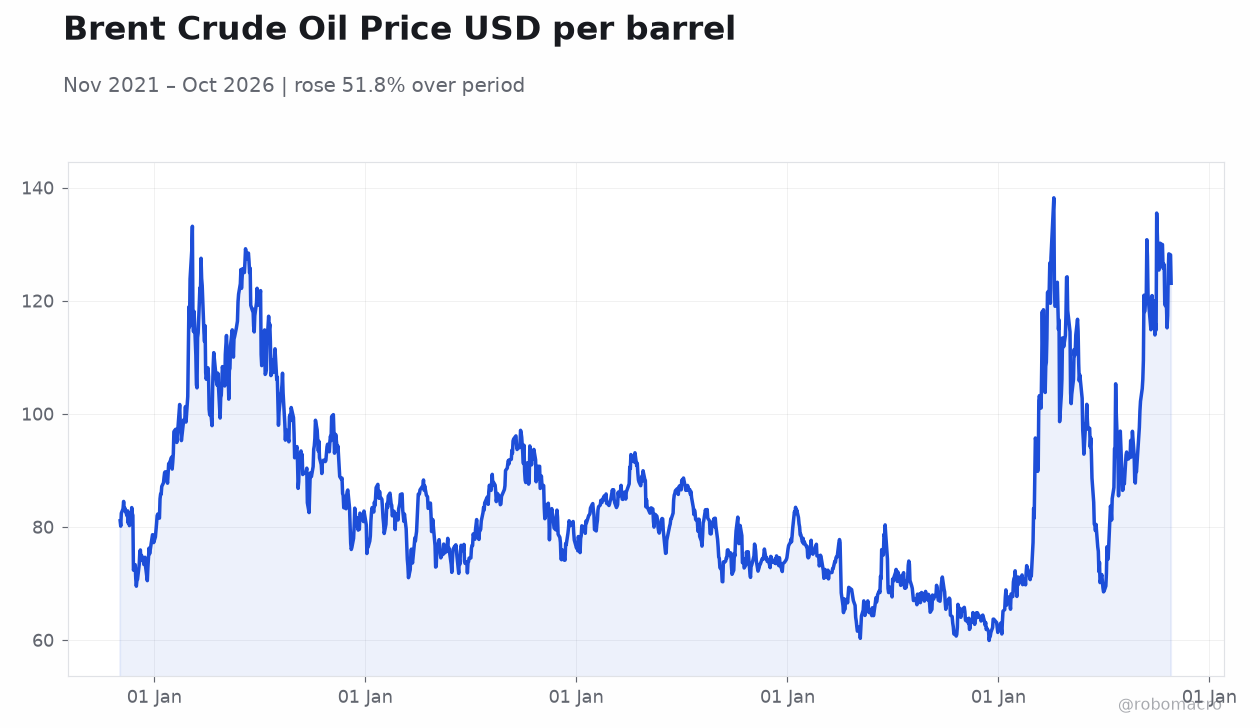
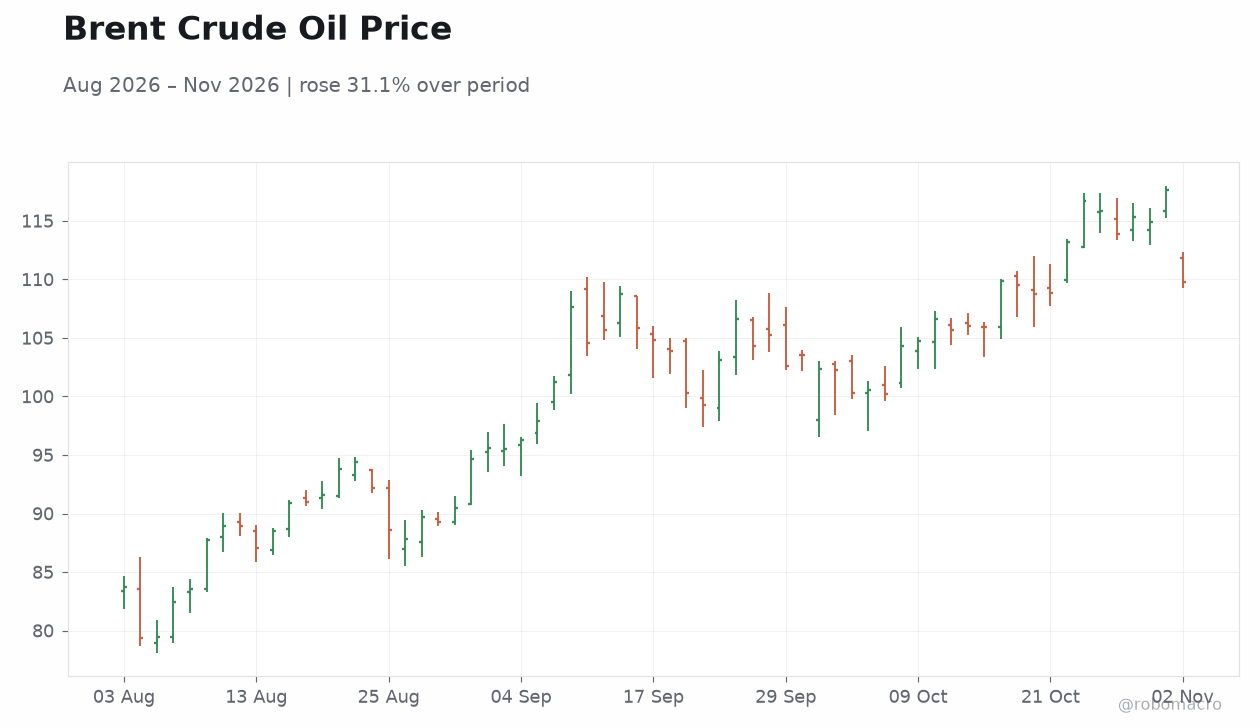
| Brent Crude | 109.77 | -6.69% |
| Gold | 3,924.30 | +0.65% |
| UK Nat Gas | 2.93 | +0.97% |
| Bitcoin | 78,243.86 | +1.04% |
| UK 2Y Gilt | 4.70% | -7 bp |
| UK 10Y Gilt | 5.33% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
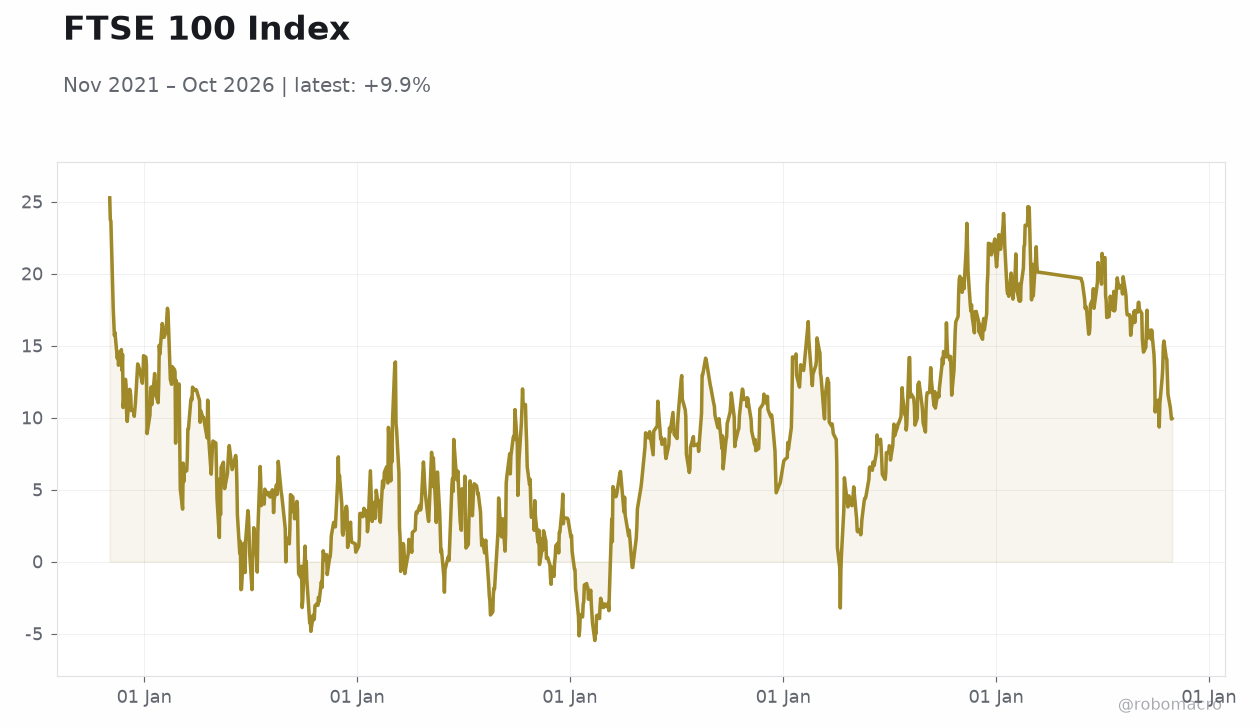 FTSE 100 Index | Type: macro_line | FTSE 100 Index: 9.935 (2026-10-30) | Range: -5.477–25.27 | Trend(6pt): 25.27,2.739,-5.477,8.064,10.29,9.935
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-05) | |||
| S&P Global Construction PMI | 46.10 | 46.50 | 04:30 |
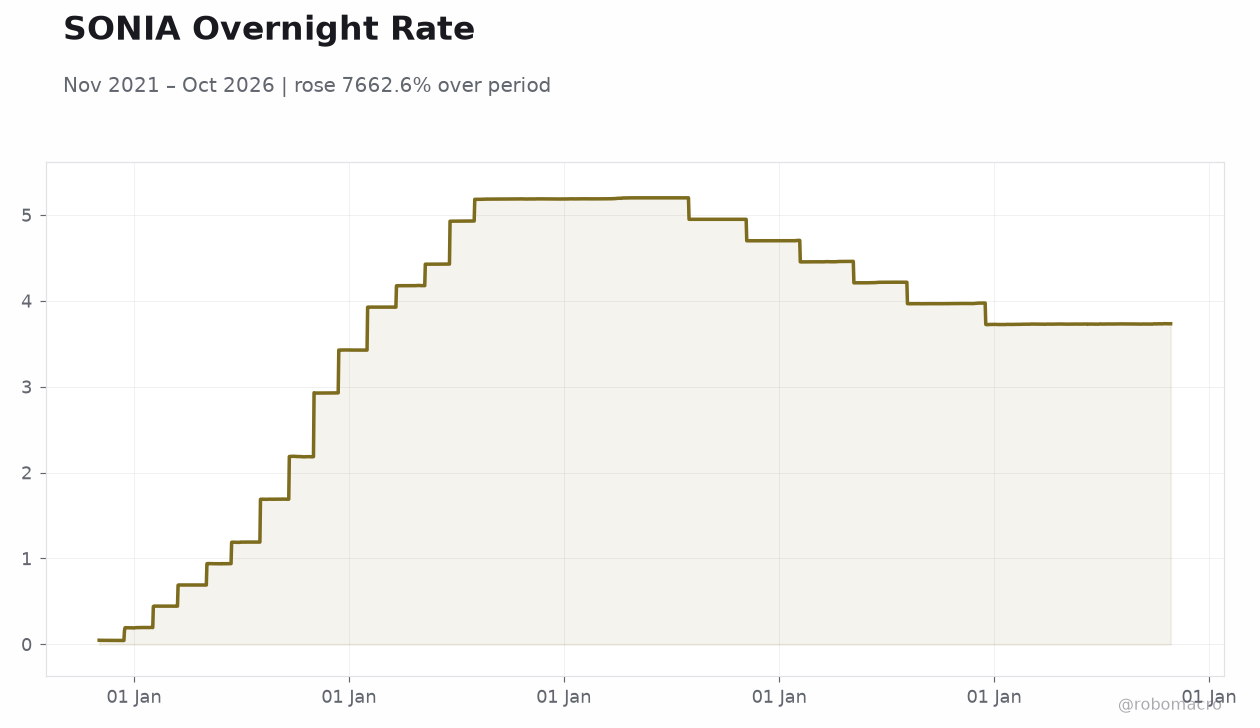
| BoE Interest Rate Decision | 3.75 | 4 | 07:00 |
| BoE MPC Vote Cut | 0 | - | 07:00 |
| BoE MPC Vote Hike | 3 | - | 07:00 |
| BoE MPC Vote Unchanged | 6 | - | 07:00 |
| BoE Monetary Policy Report | - | - | 07:00 |
| MPC Meeting Minutes | - | - | 07:00 |
| Friday (2026-11-06) | |||
| Lloyds House Price Index Month-over-Month | 0 | 0.10 | 02:00 |
- Markets price a first BoE rate rise since 2023, with consensus at 4.00% from 3.75% for Thursday's decision
- Sterling firm at 1.34 versus the dollar; 2-year gilt yield down 7 bp to 4.70% while 10-year edges up to 5.33%
- Brent crude collapses 6.69% to $109.77, easing near-term inflation pressure but signalling demand concerns
Yesterday's Recap
No UK data releases were scheduled for Sunday, leaving markets to digest Friday's close. The FTSE 100 finished marginally higher at 10,729.80 (+0.07%), though the domestically-focused FTSE 250 fell 0.89% to 24,453.40, reflecting caution ahead of Thursday's Bank of England decision. Sterling gained modestly across the board, with GBP/USD at 1.34 (+0.15%) and GBP/EUR at 1.20 (+0.11%).
Gilt markets showed a steepening bias: the 2-year yield fell 7 bp to 4.70% while the 10-year rose 1 bp to 5.33%. Brent crude's sharp 6.69% decline to $109.77 dominated cross-asset moves, while gold firmed 0.65% to $3,924.30 and UK natural gas edged up 0.97% to 2.93.
The Day Ahead
Monday's UK calendar is empty, so attention turns squarely to Thursday's packed schedule. S&P Global Construction PMI is due at 04:30 ET, with consensus at 46.5 versus a previous 46.1 — still deep in contraction territory. The main event is the BoE Interest Rate Decision at 07:00 ET, where consensus points to a hike to 4.00% from 3.75%, accompanied by the Monetary Policy Report and MPC minutes.
Friday brings the Lloyds House Price Index (MoM consensus 0.1%) at 02:00 ET and a high-impact speech from BoE Pill at 07:15 ET. With no releases today, positioning flows and pre-meeting commentary will likely drive intraday price action.
Other Economic Notes
The BoE's October Agents' summary of business conditions is in focus, with reports suggesting the Bank is exploring easing a key limit on riskier mortgage lending — potentially raising the high-risk mortgage threshold to five times income. Such a move would support credit availability and housing activity without loosening the policy rate. UK CPI at 3.50% remains well above target, and unemployment at 4.70% suggests the labour market is cooling only gradually.
The construction sector's persistent sub-50 PMI readings underscore weak activity in that segment, contrasting with firmer services. Housing data this week will test whether price momentum is holding as affordability constraints bite.