UK Macro Daily(Beta Mode)
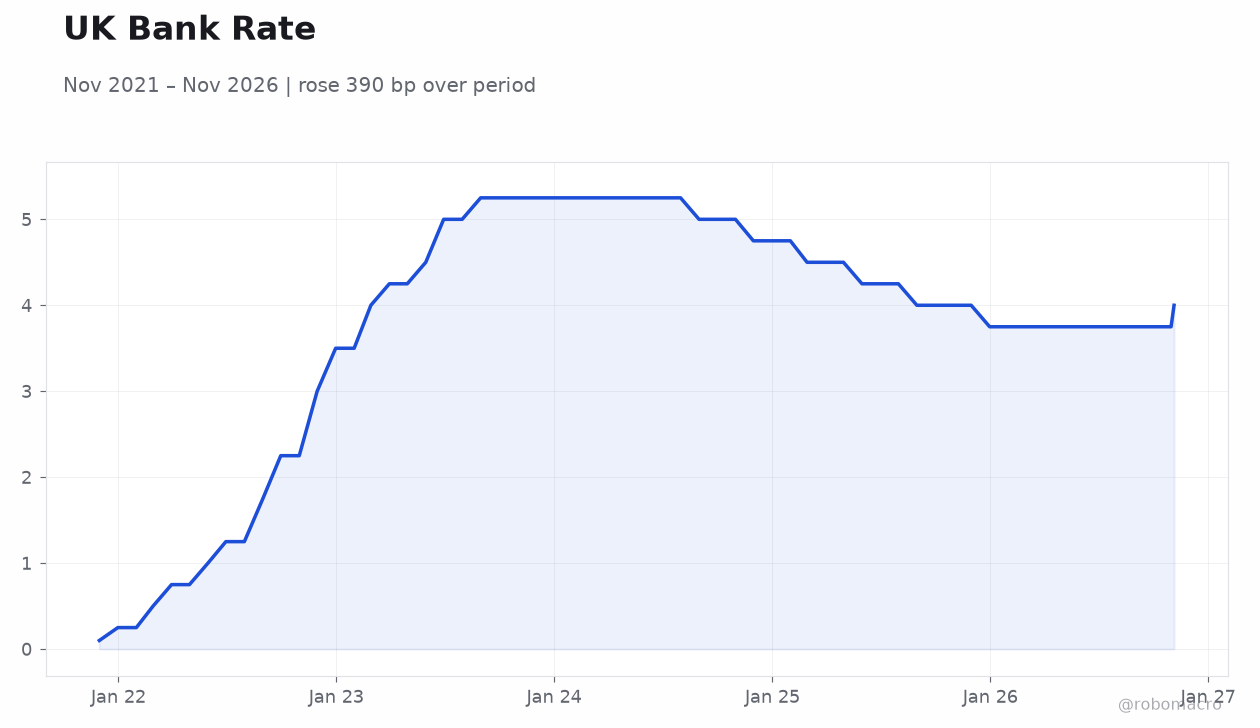
BoE Hikes to 4%, Construction PMI Slumps
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,782.66 | -0.43% |
| FTSE 250 | 24,702.00 | -0.86% |
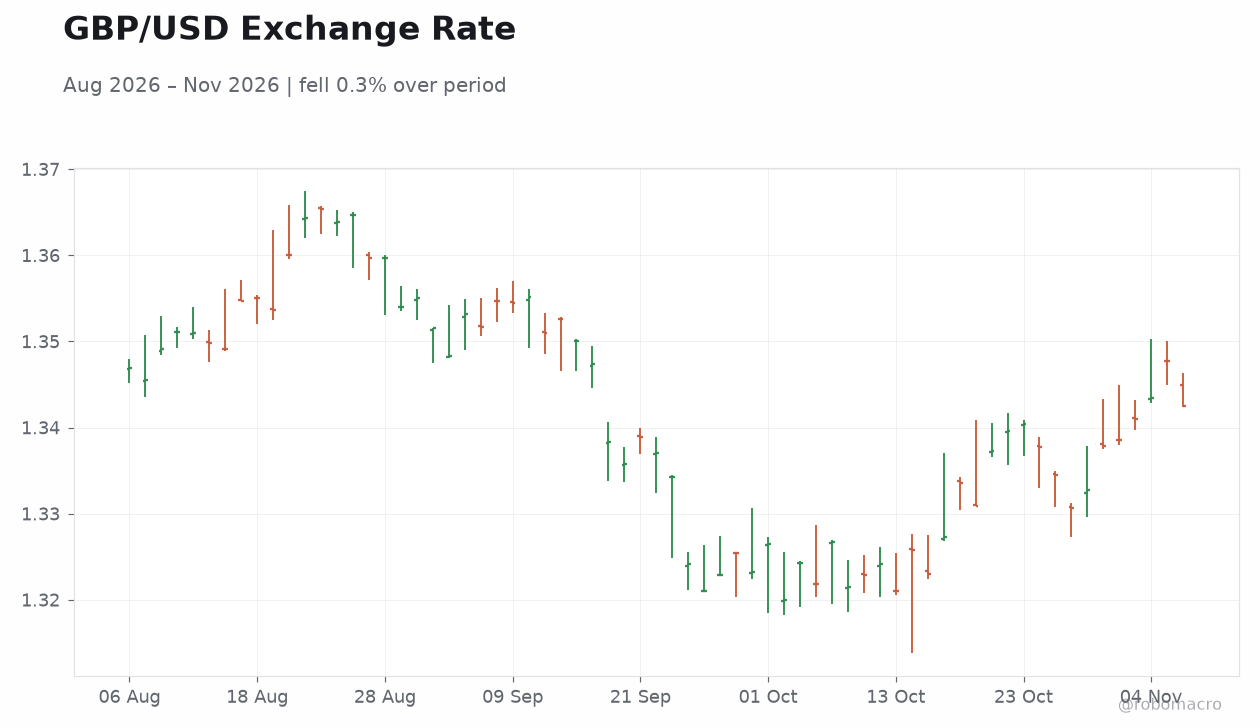
| GBP/USD | 1.34 | -0.39% |
| GBP/EUR | 1.20 | -0.07% |
| GBP/JPY | 211.81 | -0.75% |
| Brent Crude | 99.75 | +1.49% |
| Gold | 4,056.30 | -1.39% |
| UK Nat Gas | 2.98 | +1.22% |
| Bitcoin | 75,525.56 | -6.07% |
| UK 2Y Gilt | 4.58% | -6 bp |
| UK 10Y Gilt | 5.23% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| S&P Global Construction PMI | 46.10 | 46.10 | 43.60 |
| BoE Interest Rate Decision | 3.75 | 4 | 4 |
| BoE MPC Vote Cut | 0 | - | 0 |
| BoE MPC Vote Hike | 3 | - | 9 |
| BoE MPC Vote Unchanged | 6 | - | 0 |
| BoE Monetary Policy Report | - | - | - |
| MPC Meeting Minutes | - | - | - |
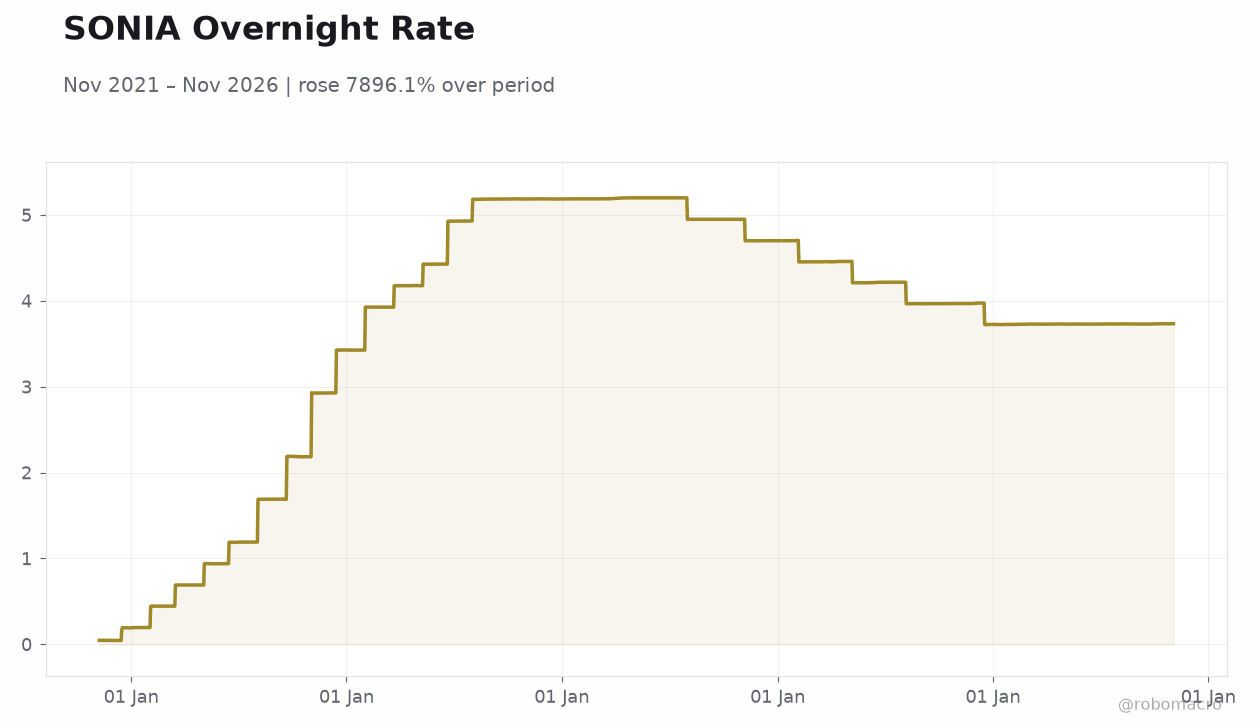 SONIA Overnight Rate | Type: macro_line | SONIA Overnight Rate: 3.734 (2026-11-03) | Range: 0.045–5.2 | Trend(6pt): 0.0467,3.927,5.2,4.217,3.735,3.734
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Lloyds House Price Index Month-over-Month | 0 | 0.10 | 02:00 |
| Lloyds House Price Index Year-over-Year | 0 | -0.30 | 02:00 |
| BoE Pill Speech | - | - | 07:15 |
- BoE raises Bank Rate to 4.00% in a unanimous 9-0 vote, first hike since 2023, signals more to come
- UK Construction PMI collapses to 43.6 vs 46.1 consensus, sharpest contraction in over a year
- Gilt curve twists: 10Y +5bp to 5.23%, 2Y -6bp to 4.58% as markets price peak rates
Yesterday's Recap
The Bank of England delivered a widely anticipated but hawkish 25bp hike, lifting Bank Rate to 4.00% with all nine MPC members voting for the increase — a unanimous split that removes any dovish dissent from the committee. The accompanying Monetary Policy Report projected CPI peaking near 5% next year, underpinning guidance that further tightening is likely. Sterling initially firmed on the unanimous vote but reversed to close down 0.39% at 1.34 against the dollar, suggesting the hike was fully priced and the guidance offered little incremental support.
Gilts twisted: the 2-year yield fell 6bp to 4.58% while the 10-year rose 5bp to 5.23%, a curve dynamic consistent with markets pricing a near-term peak in Bank Rate alongside elevated long-run inflation risk. The S&P Global Construction PMI printed 43.6 against a 46.1 consensus and prior, a stark contraction highlighting the toll of higher borrowing costs on the housing and commercial build sectors. Equities softened, with the FTSE 100 down 0.43% to 10,782.66 and the domestically-focused FTSE 250 off 0.86% to 24,702.00, the mid-cap index underperforming as rate-sensitive names bore the brunt.
The Day Ahead
Attention turns to the Lloyds House Price Index, with month-over-month consensus at 0.1% following a flat prior, and year-over-year expected at -0.3% — a soft print would reinforce the construction weakness and sharpen the narrative of a cooling housing market under rate pressure. BoE Chief Economist Huw Pill speaks at 07:15 ET, a high-impact event given his recent hawkish commentary; markets will parse his remarks for the pace and terminal level of further hikes following the unanimous vote. With no major tier-one data beyond these releases, price action will likely be driven by Pill's tone and gilt supply dynamics.
Sterling crosses remain the key transmission channel, with GBP/JPY down 0.75% to 211.81 reflecting broad risk-off. Traders should watch whether the 2s10s gilt curve steepens further as the market digests the "more likely" guidance.
Other Economic Notes
The unanimous vote and explicit warning that further hikes are likely mark a decisive shift in the BoE's reaction function, prioritising inflation control over growth support even as activity data deteriorate. ↓ p.2