UK Macro Daily(Beta Mode)
Gilts Rally as BoE Signals Patience
Market Snapshot
| Asset | Level | Change |
|---|---|---|
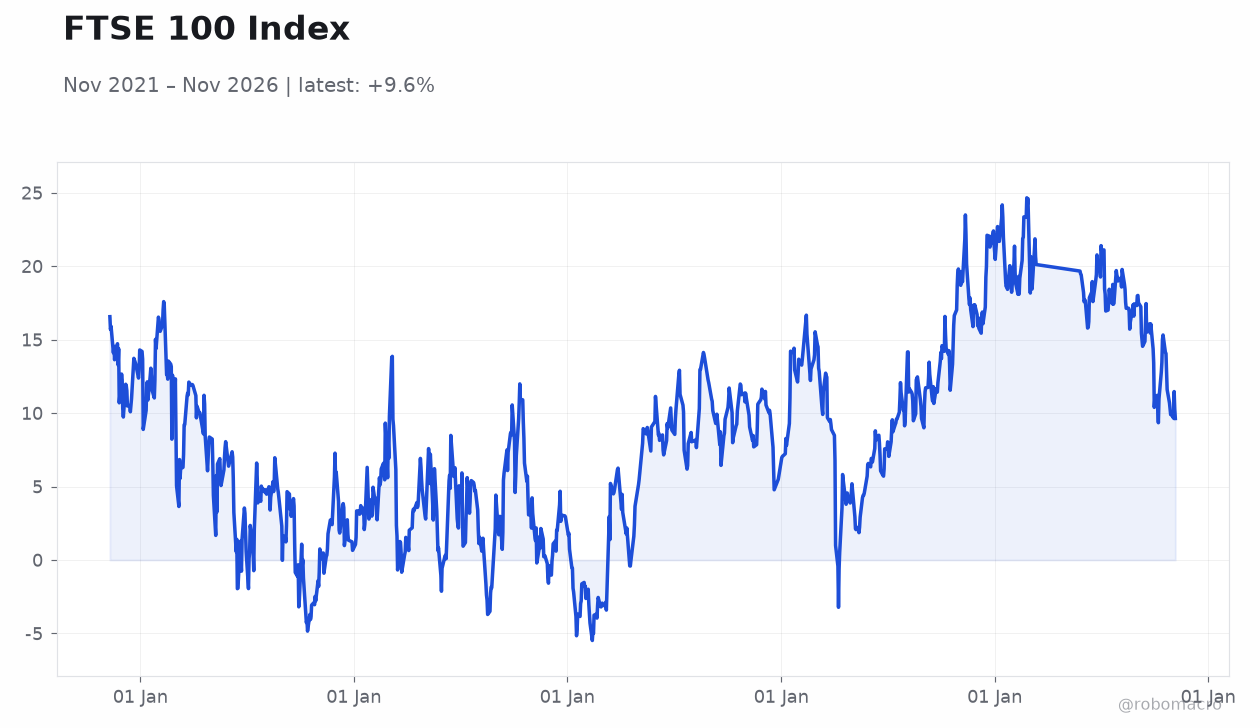
| FTSE 100 | 10,673.90 | -1.01% |
| FTSE 250 | 24,504.30 | -0.80% |
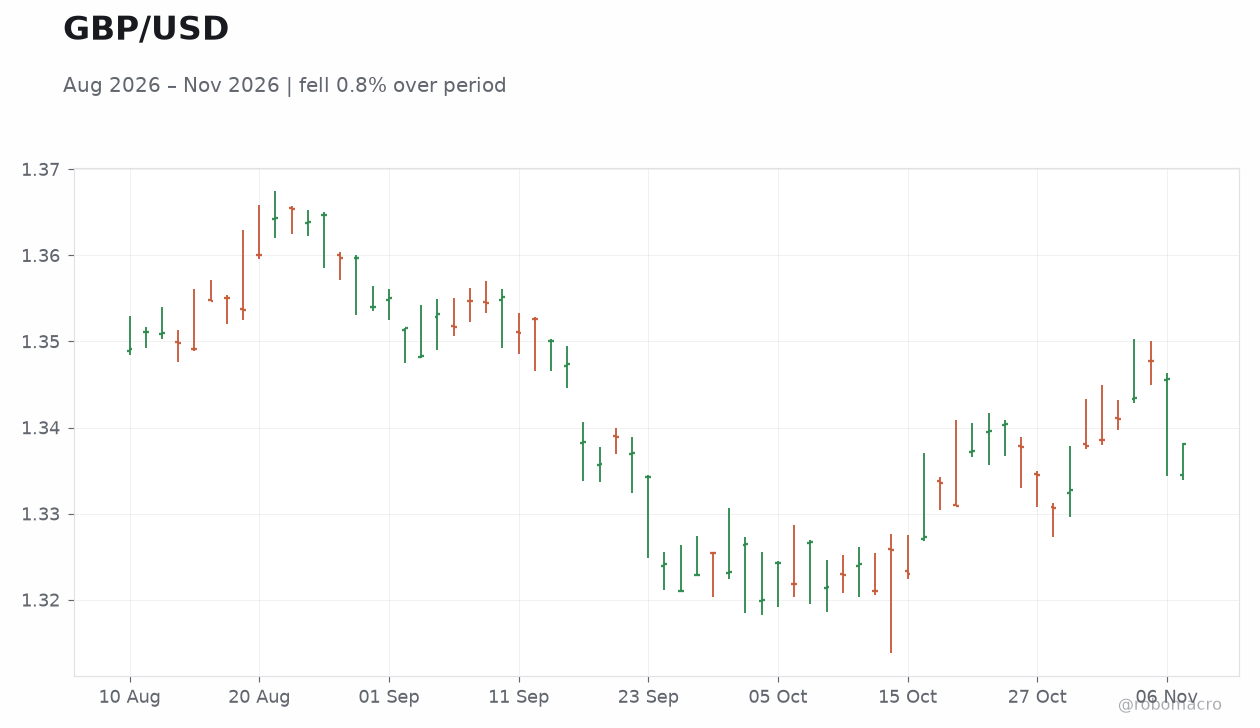
| GBP/USD | 1.34 | -0.56% |
| GBP/EUR | 1.20 | +0.01% |
| GBP/JPY | 211.74 | -0.07% |
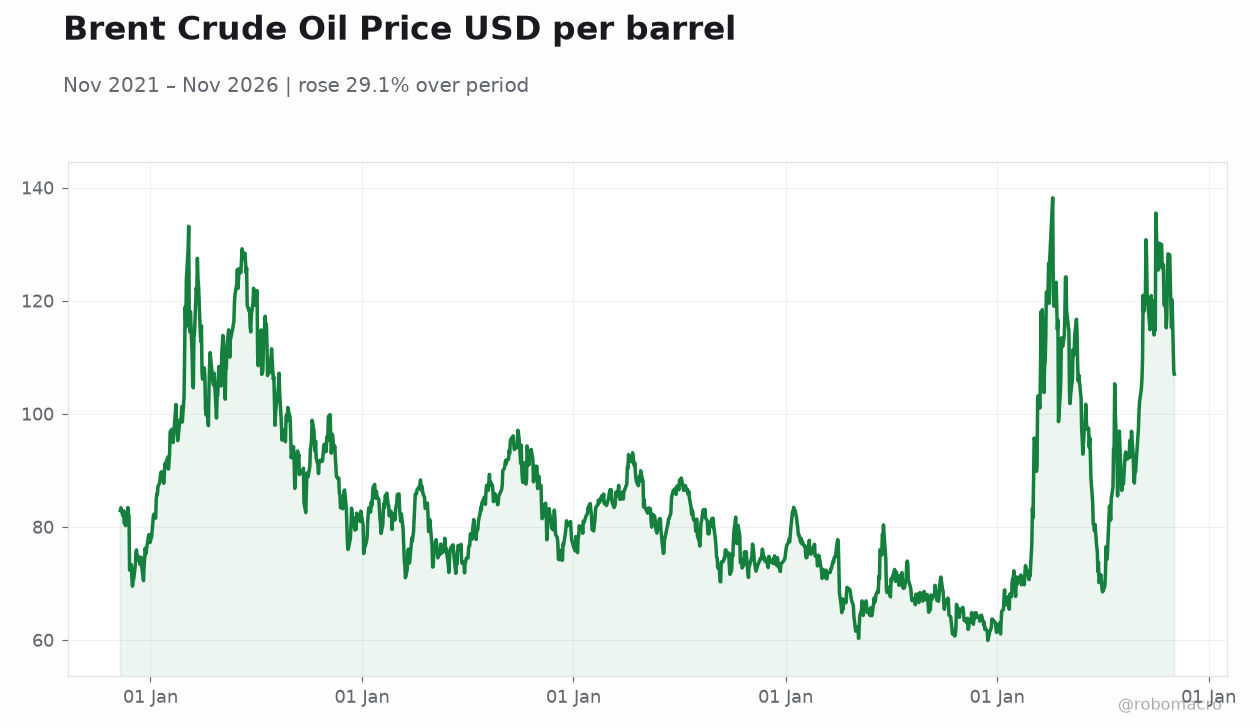
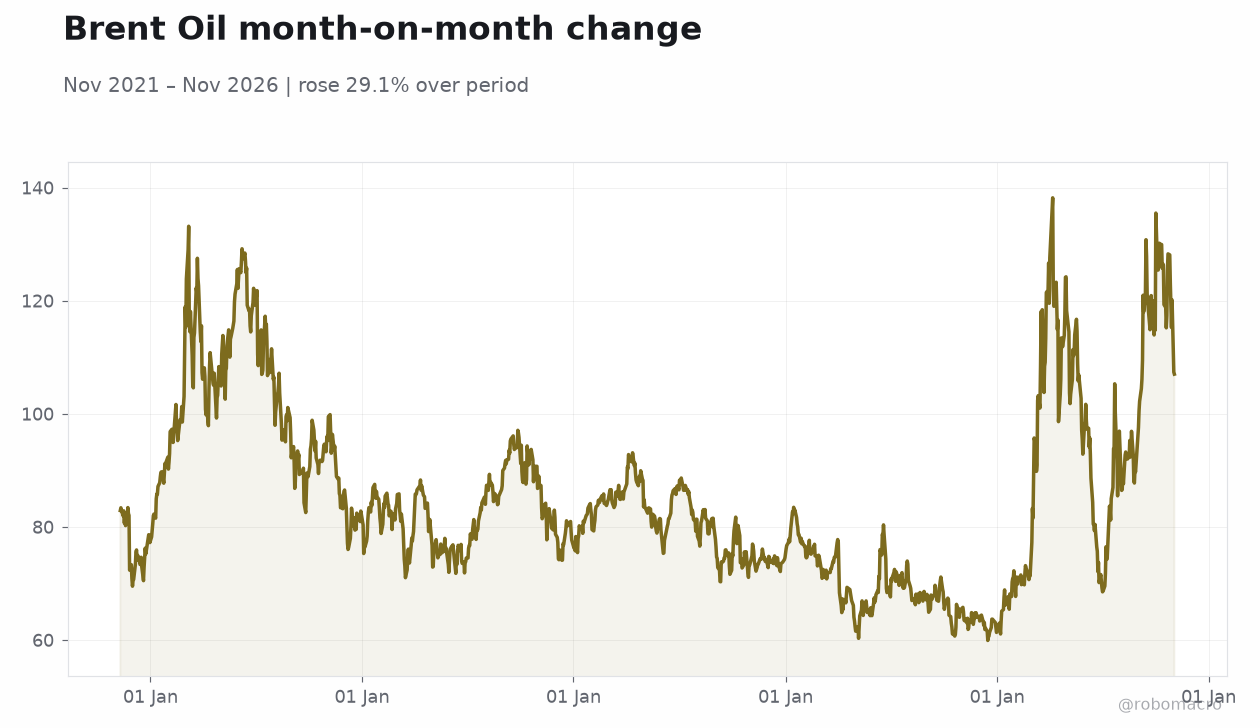
| Brent Crude | 97.10 | -1.24% |
| Gold | 4,131.60 | +1.39% |
| UK Nat Gas | 3.03 | +0.97% |
| Bitcoin | 74,377.16 | -1.81% |
| UK 2Y Gilt | 4.57% | -1 bp |
| UK 10Y Gilt | 5.15% | -8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
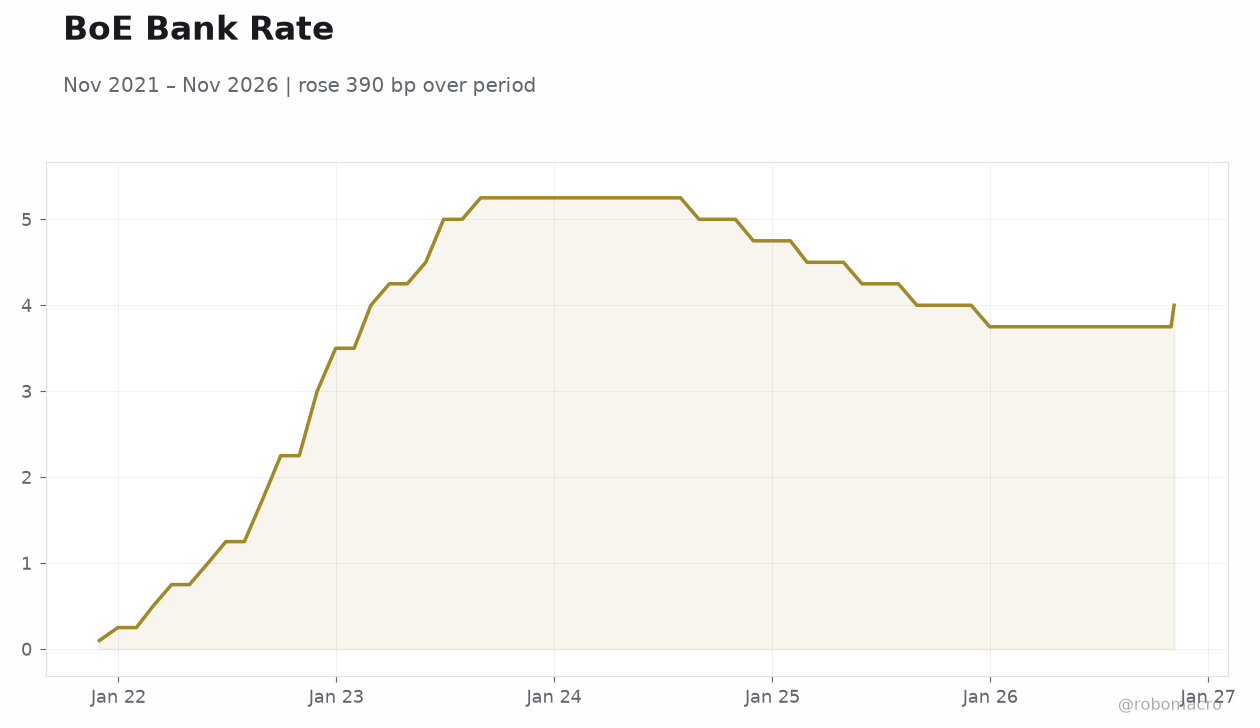 BoE Bank Rate | Type: macro_line | BoE Bank Rate (BIS): 4 (2026-11-05) | Range: 0.1–5.25 | Trend(5pt): 0.1,4,5.25,4,4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Gov Bailey Speech | - | - | 12:30 |
| BRC Retail Sales Monitor Year-over-Year | 1 | - | 19:01 |
| Tuesday (2026-11-10) | |||
| BoE Lombardelli Speech | - | - | 07:30 |
| BoE Pill Speech | - | - | 13:30 |
| Wednesday (2026-11-11) | |||
| RICS House Price Balance | -32 | -32 | 19:01 |
| Thursday (2026-11-12) | |||
| GDP Growth Quarter-over-Quarter Preliminary | 0.50 | 0.70 | 02:00 |
| GDP Growth Year-over-Year Preliminary | 1.40 | - | 02:00 |
- Long-end gilts rallied sharply, with the 10-year yield easing 8 bp to 5.15%, as markets digest the BoE's 4.00% Bank Rate hold and cautious forward guidance.
- Sterling softened against the dollar (GBP/USD 1.34, -0.56%) while holding steady versus the euro, reflecting broad risk-off sentiment and divergent rate expectations.
- Attention turns to BoE Governor Bailey's speech today and Thursday's preliminary Q3 GDP print, with consensus at 0.7% q/q versus 0.5% prior.
Yesterday's Recap
UK markets closed Friday in a pronounced risk-off posture, with the FTSE 100 shedding 1.01% to 10,673.90 and the FTSE 250 down 0.80% to 24,504.30. Gilt yields moved lower across the curve, with the 10-year easing 8 bp to 5.15% and the 2-year down 1 bp to 4.57%, a flattening bias consistent with growth concerns rather than inflation fears. Sterling depreciated 0.56% against the dollar to 1.34 but was essentially flat versus the euro at 1.20, suggesting the move was dollar-driven rather than UK-specific.
Commodities offered little relief: Brent crude fell 1.24% to $97.10, while gold rallied 1.39% to $4,131.60 and UK natural gas edged up 0.97% to 3.03. Bitcoin slipped 1.81% to $74,377, reinforcing the defensive tone across risk assets. No tier-one UK data releases were scheduled, leaving positioning and global cues to drive price action.
The Day Ahead
The domestic calendar pivots to Bank of England communication, with Governor Bailey speaking at 12:30 ET — a high-impact event that markets will parse for signals on the pace of future easing following the November 5 decision to hold Bank Rate at 4.00%. Overnight, the BRC Retail Sales Monitor (19:01 ET) provides an early read on consumer spending momentum, with the prior reading at 1% year-over-year. Tuesday brings a dense BoE speaker slate, with Lombardelli at 07:30 ET and Pill at 13:30 ET, both high-impact and likely to shape the rates narrative ahead of Thursday's GDP release.
Thursday's preliminary Q3 GDP data (02:00 ET) is the week's centerpiece: consensus expects 0.7% q/q versus 0.5% prior, alongside month-over-month GDP (consensus 0.0% vs 0.1% prior), industrial production (consensus -0.4% vs 0.8% prior), and the goods trade balance (consensus -£19.2bn vs -£18.01bn prior). Wednesday's RICS House Price Balance (19:01 ET) rounds out the housing picture, with consensus at -32, unchanged from prior.
Other Economic Notes
The UK macro backdrop remains fragile, with CPI at 3.50% as of September and unemployment at 4.70% as of July — a combination that keeps the BoE in a difficult policy bind. ↓ p.2