UK Macro Daily(Beta Mode)
Gilts Wobble as BoE Signals December Hike in Play
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,835.50 | +0.78% |
| FTSE 250 | 24,925.00 | +0.72% |
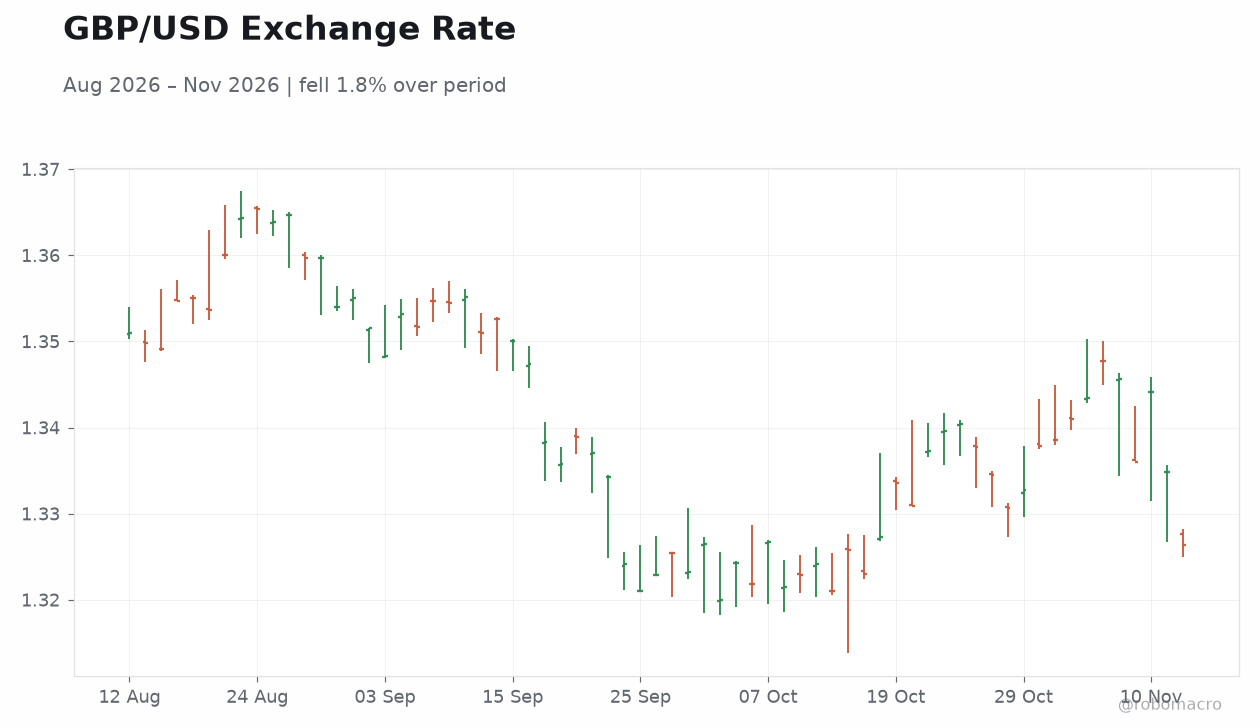
| GBP/USD | 1.33 | -0.68% |
| GBP/EUR | 1.20 | +0.12% |
| GBP/JPY | 211.89 | +0.02% |
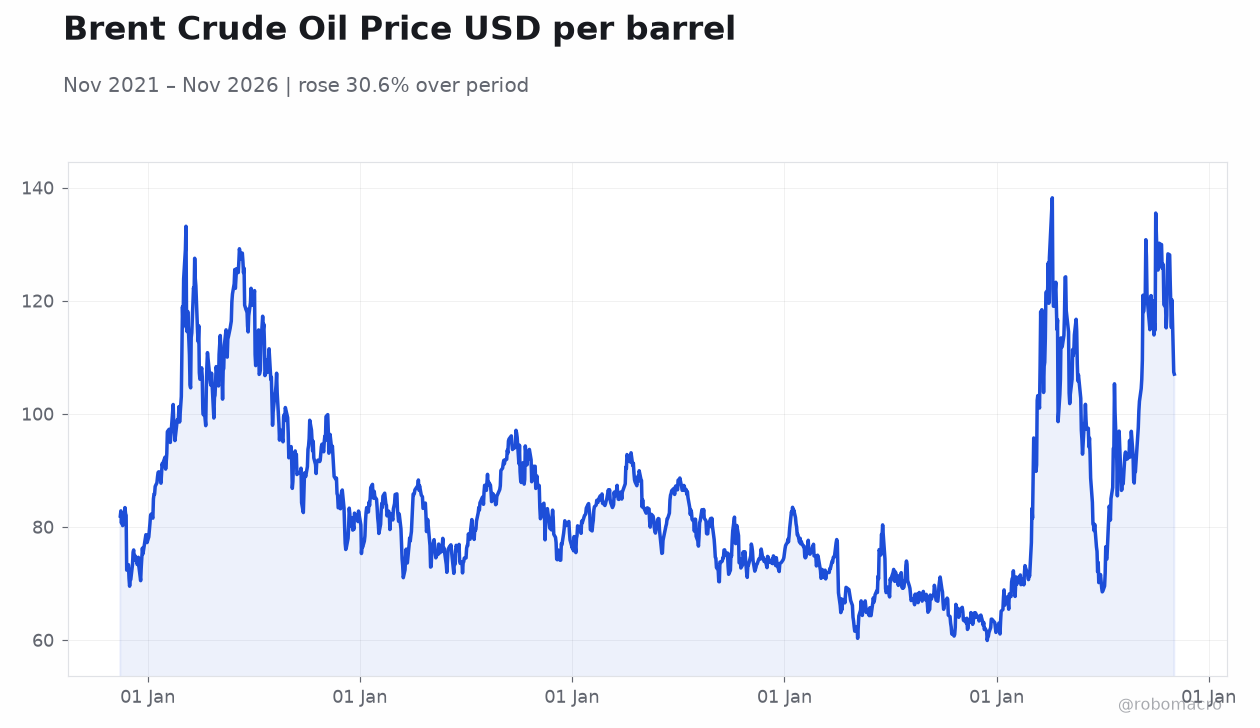
| Brent Crude | 92.64 | -0.13% |
| Gold | 3,973.00 | -0.69% |
| UK Nat Gas | 3.24 | +0.65% |
| Bitcoin | 73,520.05 | -0.27% |
| UK 2Y Gilt | 4.66% | +10 bp |
| UK 10Y Gilt | 5.13% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Gov Bailey Speech | - | - | - |
| BRC Retail Sales Monitor Year-over-Year | 1 | 1.20 | 1.10 |
| BoE Lombardelli Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| RICS House Price Balance | -32 | -32 | - |
| GDP Growth Quarter-over-Quarter Preliminary | 0.50 | 0.70 | - |
| GDP Growth Year-over-Year Preliminary | 1.40 | 1.90 | - |
| GDP Month-over-Month | 0.10 | 0 | - |
| Business Investment Quarter-over-Quarter Prel | 1.80 | - | - |
| GDP 3-Month Avg | 0.70 | 0.70 | - |
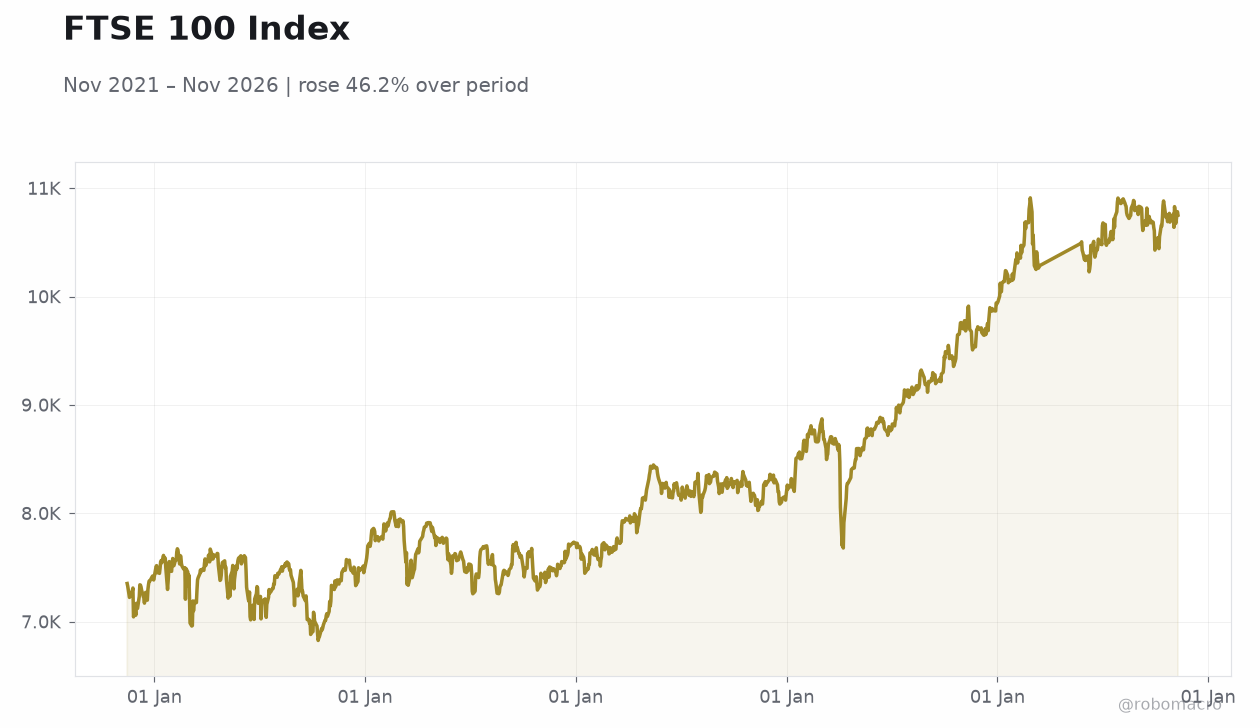 FTSE 100 Index | Type: macro_line | FTSE 100 Index: 1.075e+04 (2026-11-10) | Range: 6826–1.091e+04 | Trend(5pt): 7352,7772,7966,8736,1.075e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BoE's Lombardelli flags December rate rise as "in play," lifting 2-year gilt yields 10 bp to 4.66% while sterling slipped 0.68% against the dollar to 1.33.
- Q3 GDP preliminary print due today at 02:00 ET; consensus looks for 0.7% q/q versus 0.5% prior, with monthly GDP flat expected after 0.1% prior.
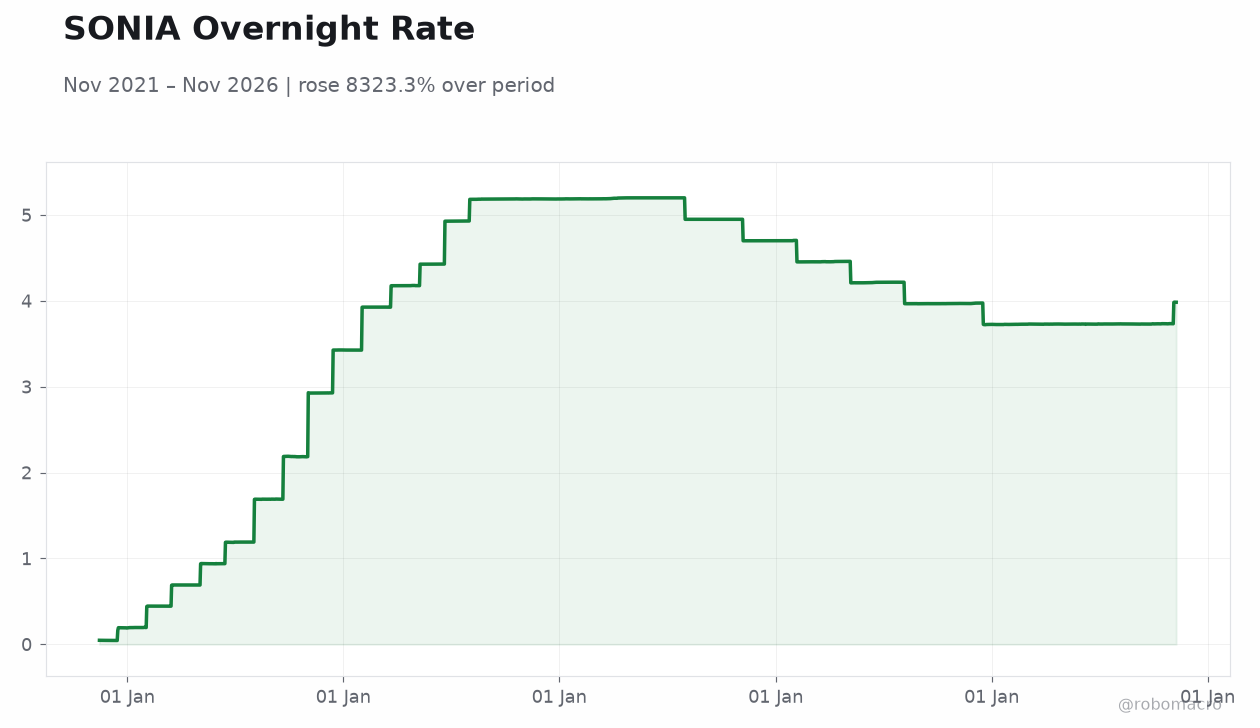
- NIESR forecasts UK inflation overshooting the 2% target for four more years, urging Bank Rate toward 5% — a hawkish backdrop for the 17 December MPC.
Yesterday's Recap
The UK data calendar delivered a mixed picture on 11 November. The BRC Retail Sales Monitor printed 1.1% year-over-year, below the 1.2% consensus and only marginally above the prior 1.0%, underscoring subdued consumer momentum. The RICS House Price Balance came in at -32, matching both consensus and the prior reading, confirming a still-soft housing market.
Sterling bore the brunt of hawkish MPC commentary, with GBP/USD falling 0.68% to 1.33 even as GBP/EUR firmed 0.12% to 1.20. Gilt curves twisted: the 2-year yield jumped 10 bp to 4.66% while the 10-year eased 1 bp to 5.13%, a bear-flattening move consistent with markets pricing a nearer-term hike. Equities shrugged off the rates signal, with the FTSE 100 up 0.78% to 10,835.50 and the FTSE 250 gaining 0.72% to 24,925.00.
Brent crude slipped 0.13% to $92.64 and gold fell 0.69% to $3,973.00.
The Day Ahead
The focus shifts squarely to this morning's GDP bundle at 02:00 ET. Preliminary Q3 GDP is expected at 0.7% q/q versus 0.5% prior, with the year-over-year reading consensus at 1.9% against 1.4% prior. Monthly GDP is seen flat at 0.0% after 0.1% prior, while the 3-month average is expected to hold at 0.7%.
Industrial production is forecast to contract 0.3% m/m after 0.8% prior, and manufacturing production is seen down 0.5% m/m following 1.2% prior. The goods trade balance is expected to widen to -£19.2bn from -£18.01bn, with business investment and non-EU trade detail also due. No further UK releases are scheduled for 13 November.
Other Economic Notes
The BRC print of 1.1% suggests retail spending is running below the pace policymakers would like to see as they weigh further tightening. The RICS balance stuck at -32 points to persistent weakness in housing activity, a channel through which higher Bank Rate transmits quickly. NIESR's projection that inflation overshoots target for four years — potentially until 2030 — frames the policy debate around credibility rather than growth support.
↓ p.2