UK Macro Daily(Beta Mode)
UK GDP Beats as BoE Signals Hike Bias
Market Snapshot
| Asset | Level | Change |
|---|---|---|
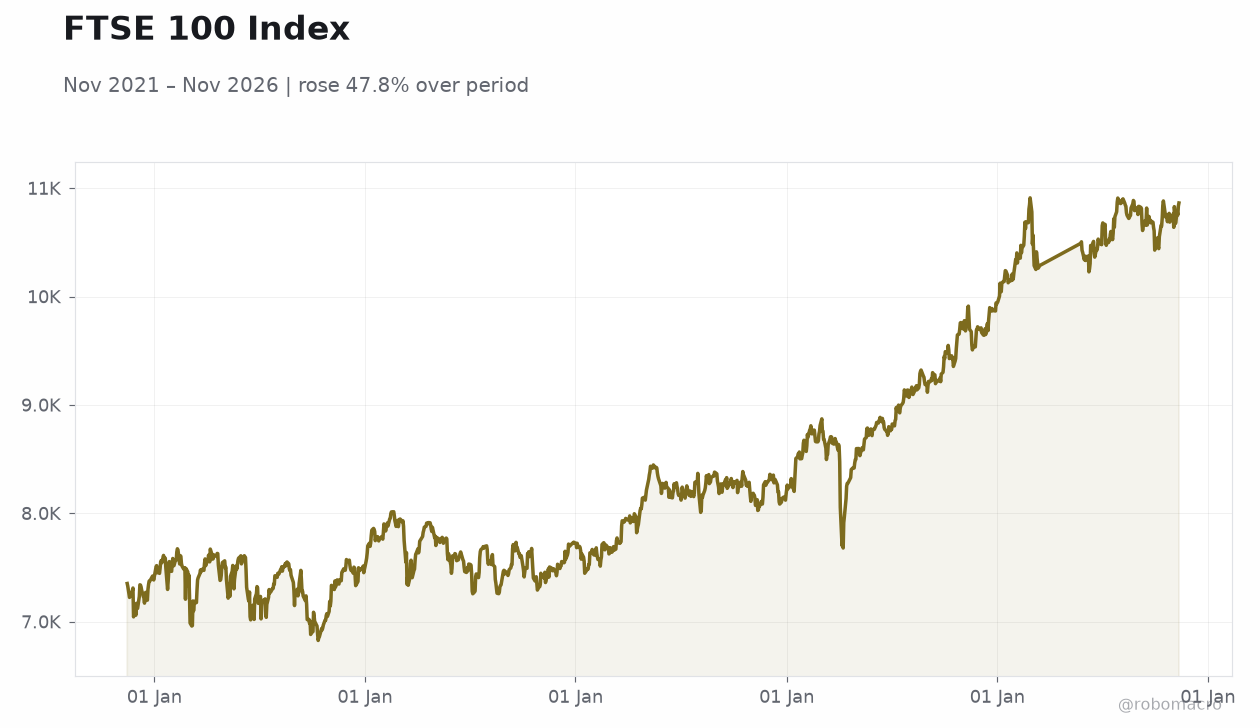
| FTSE 100 | 10,863.09 | +0.25% |
| FTSE 250 | 24,916.80 | -0.03% |
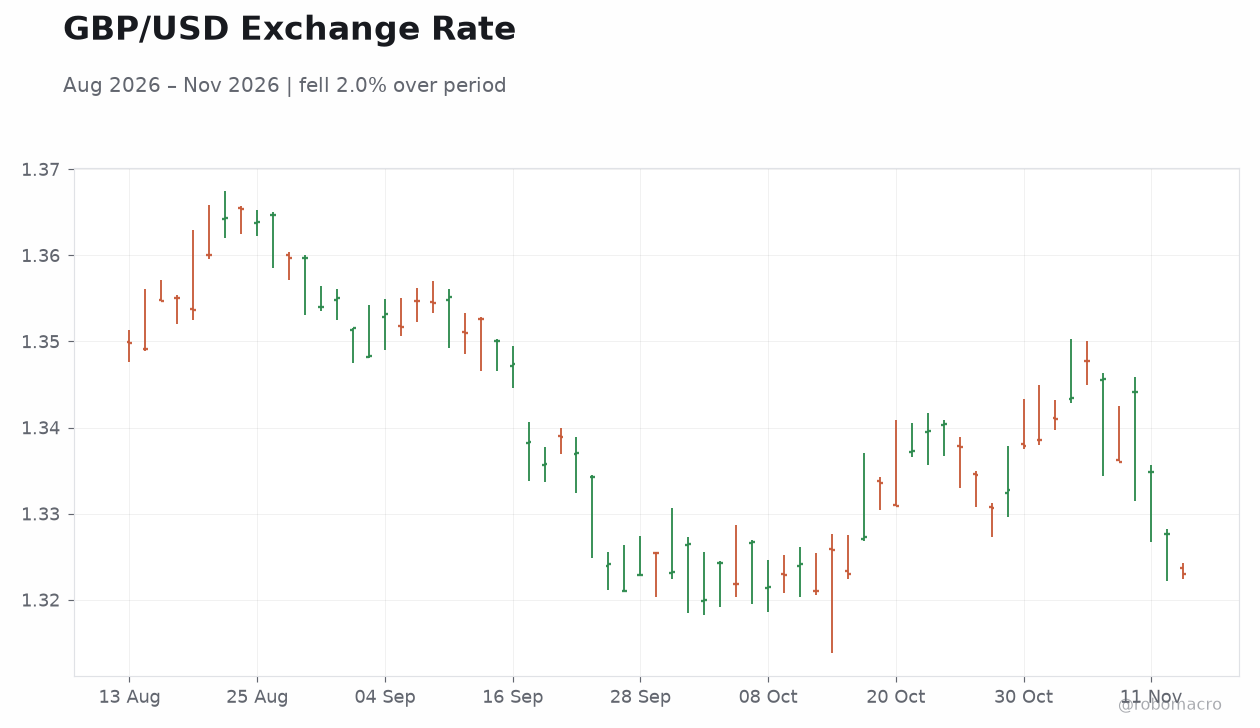
| GBP/USD | 1.32 | -0.37% |
| GBP/EUR | 1.20 | -0.07% |
| GBP/JPY | 211.60 | -0.22% |
| Brent Crude | 95.73 | -0.09% |
| Gold | 3,899.90 | +0.38% |
| UK Nat Gas | 3.31 | -1.02% |
| Bitcoin | 67,961.10 | -8.12% |
| UK 2Y Gilt | 4.71% | +5 bp |
| UK 10Y Gilt | 5.21% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Gov Bailey Speech | - | - | - |
| BRC Retail Sales Monitor Year-over-Year | 1 | 1.20 | 1.10 |
| BoE Lombardelli Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| RICS House Price Balance | -32 | -32 | -36 |
| GDP Growth Quarter-over-Quarter Preliminary | 0.50 | 0.70 | 0.70 |
| GDP Growth Year-over-Year Preliminary | 1.40 | 1.90 | 1.90 |
| GDP Month-over-Month | 0 | 0 | 0.20 |
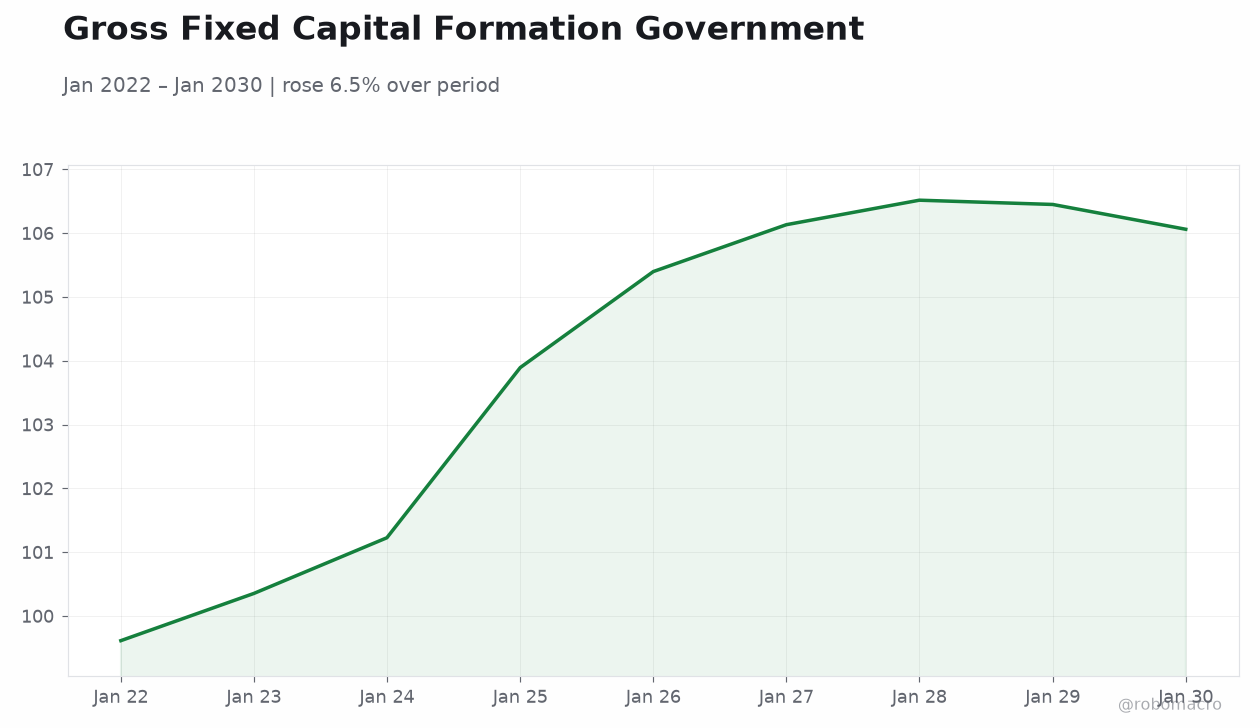
| Business Investment Quarter-over-Quarter Prel | 1.80 | - | 0.40 |
| GDP 3-Month Avg | 0.60 | 0.70 | 0.70 |
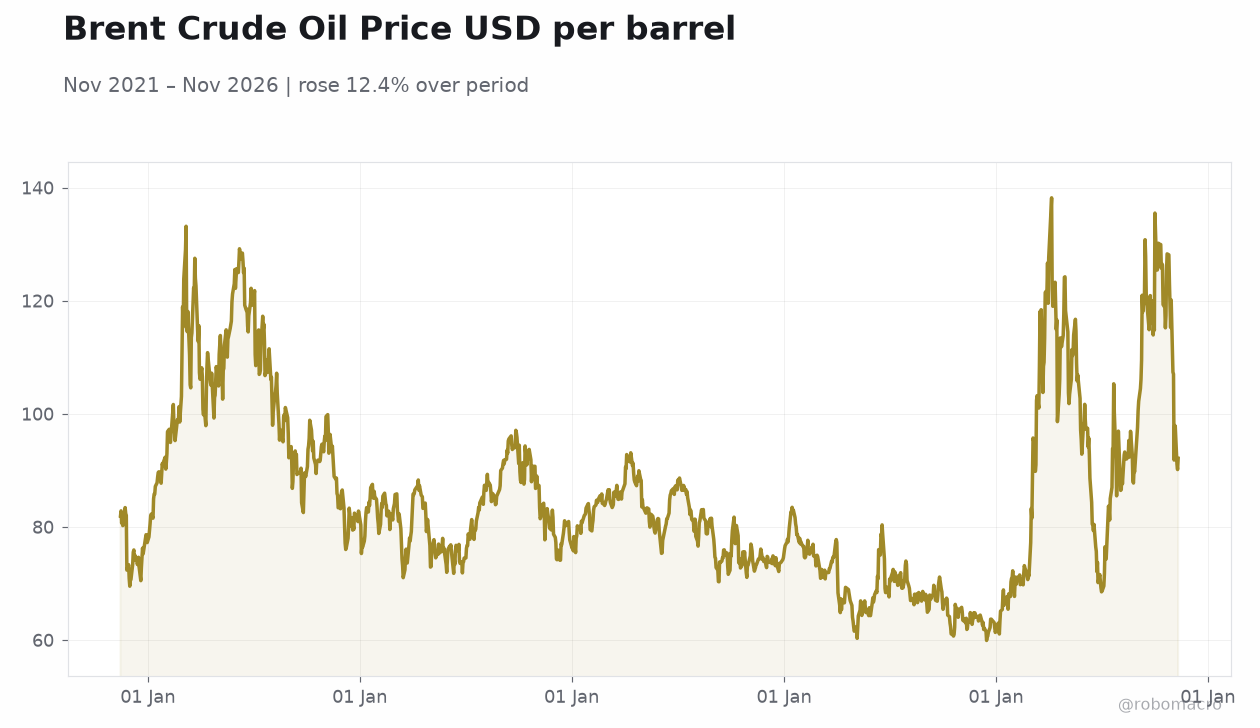 Brent Crude Oil Price USD per barrel | Type: macro_line | Brent Crude Oil Price USD per barrel: 92.14 (2026-11-11) | Range: 59.93–138.2 | Trend(6pt): 81.94,84.96,81.65,66.25,90.16,92.14
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- UK Q3 GDP rose 0.7% q/q and 1.9% y/y, matching consensus and marking the strongest expansion in 2.5 years, with monthly GDP up 0.2%.
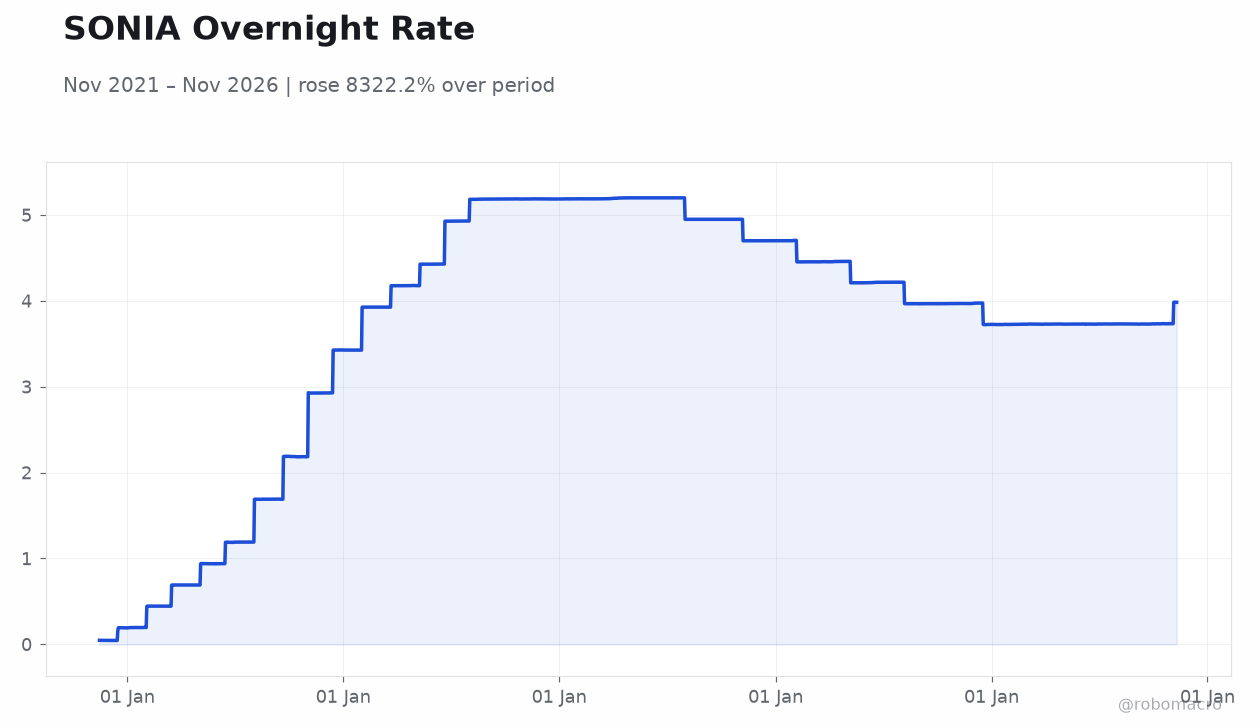
- BoE's Lombardelli signalled another rate rise is likely in the near term, reinforcing the hawkish tilt after the 5 November +25bp hike to 4.00%.
- Gilt curve steepened with 2Y up 5bp to 4.71% and 10Y up 2bp to 5.21%; sterling slipped 0.37% to 1.32 despite strong data.
Yesterday's Recap
UK Q3 GDP printed at 0.7% q/q and 1.9% y/y, both matching consensus and accelerating from 0.5% and 1.4% prior, with monthly GDP up 0.2%. The 3-month average also came in at 0.7%. Manufacturing production rose 0.7% m/m versus -0.5% consensus, and industrial production added 0.3% against expectations of a 0.3% decline.
Business investment grew just 0.4% q/q, a sharp slowdown from 1.8%. The goods trade deficit widened to £22.29bn from £19.61bn, with the non-EU gap at £8.99bn. RICS house price balance deteriorated to -36 from -32, and BRC retail sales came in at 1.1% versus 1.2% consensus.
Gilts sold off with the 2-year up 5bp to 4.71% and the 10-year up 2bp to 5.21%, while FTSE 100 rose 0.25% to 10,863 and sterling fell 0.37% to 1.32.
The Day Ahead
No UK data releases are scheduled for Friday, leaving markets to digest Thursday's GDP block and this week's heavy BoE speaker slate. Attention turns to positioning ahead of the 17 December MPC decision, with rate expectations likely to firm after Lombardelli's hawkish comments. Gilt traders will watch for follow-through in the front end after the 5bp 2-year sell-off.
Sterling crosses remain the key tell, with GBP/USD at 1.32 vulnerable if hawkish rhetoric fails to offset growth-driven risk appetite. External drivers, including global risk sentiment and energy prices, will dominate a thin domestic calendar.
Other Economic Notes
The Q3 GDP beat widens the gap with OBR forecasts and prompted the BoE to lift its growth outlook to 1.6%, per press reports. Business investment decelerating to 0.4% q/q is a concern given the government's growth agenda. The goods trade deficit widening to £22.29bn underscores persistent external imbalances.
Housing momentum remains weak, with RICS at -36, and retail sales growth of 1.1% suggests cautious consumer behaviour. AI-related demand is emerging as a genuine growth driver, though concentration risk bears watching.