UK Macro Daily(Beta Mode)
Gilt Selloff Deepens as BoE Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
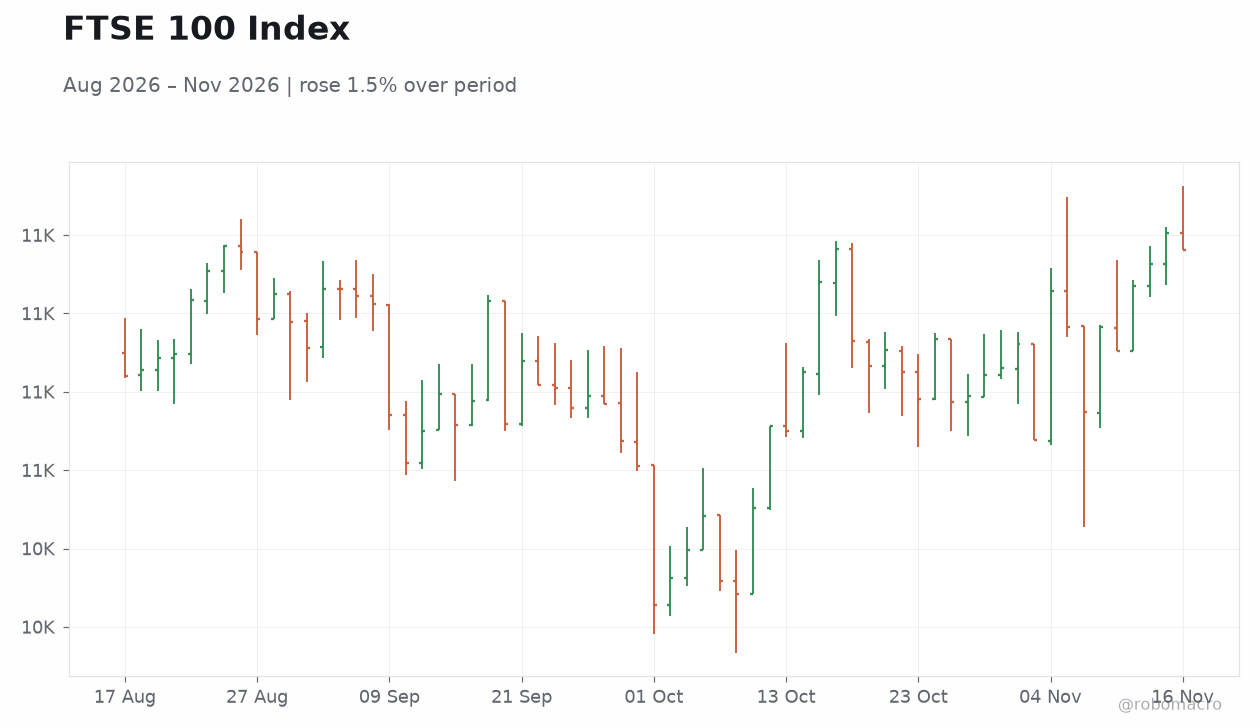
| FTSE 100 | 10,881.60 | -0.19% |
| FTSE 250 | 24,700.10 | -0.42% |
| GBP/USD | 1.32 | -0.13% |
| GBP/EUR | 1.20 | -0.04% |
| GBP/JPY | 210.17 | -0.47% |
| Brent Crude | 91.85 | -0.64% |
| Gold | 3,873.90 | +0.54% |
| UK Nat Gas | 3.11 | -0.51% |
| Bitcoin | 64,602.56 | -1.08% |
| UK 2Y Gilt | 4.74% | 0 bp |
| UK 10Y Gilt | 5.32% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 4.70 | - | - |
| Average Earnings incl. Bonus (3Mo/Yr) | 3.70 | - | - |
| Employment Change | 102,000 | - | - |
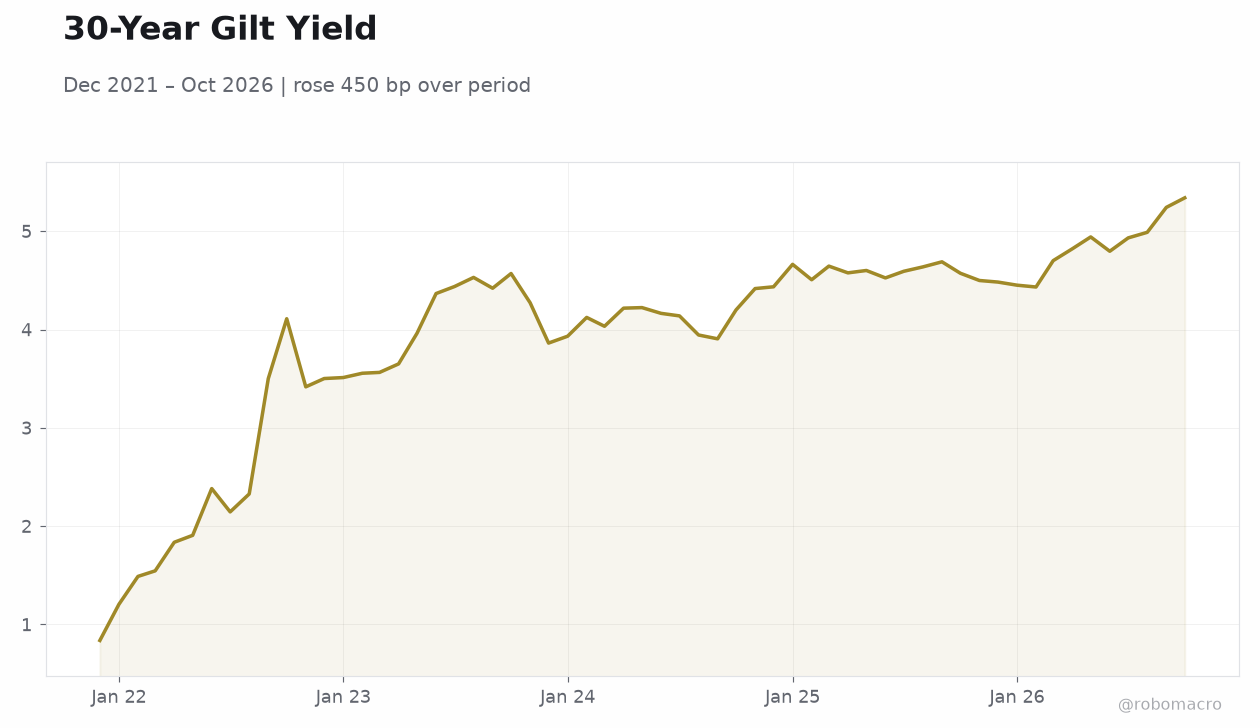 30-Year Gilt Yield | Type: macro_line | 30-Year Gilt Yield: 5.339 (2026-10-01) | Range: 0.8375–5.339 | Trend(6pt): 0.8375,3.555,4.217,4.525,4.989,5.339
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-11-18) | |||
| Inflation Rate Year-over-Year | 3.50 | - | 02:00 |
| Core Inflation Rate Year-over-Year | 2.80 | - | 02:00 |
| Inflation Rate Month-over-Month | 0.40 | - | 02:00 |
| Thursday (2026-11-19) | |||
| GFK Consumer Confidence Index | -24 | - | 19:01 |
| Friday (2026-11-20) | |||
| Retail Sales Month-over-Month | -0.40 | - | 02:00 |
| Retail Sales Year-over-Year | 0.80 | - | 02:00 |
| CBI Industrial Trends Orders | -32 | - | 06:00 |
- UK labour market data due today, with unemployment last at 4.7% and earnings growth at 3.7% 3m/yr
- October CPI lands tomorrow; headline last printed 3.5% YoY with core at 2.8%
- 10-year gilt yield jumped 6 bp to 5.32% as markets price a December BoE hike
Yesterday's Recap
UK assets traded defensively into the new week, with the FTSE 100 shedding 0.19% to 10,881.60 and the mid-cap FTSE 250 down 0.42% to 24,700.10. Sterling weakened across the board, with GBP/USD slipping 0.13% to 1.32 and GBP/JPY falling 0.47% to 210.17, while GBP/EUR held near 1.20. The standout move was in the gilt market, where the 10-year yield rose 6 bp to 5.32% even as the 2-year held at 4.74%.
The curve steepening reflects a market increasingly convinced the Bank of England will tighten again before year-end, with the next MPC decision set for 17 December. Brent crude eased 0.64% to $91.85 and UK natural gas fell 0.51% to 3.11, offering limited relief on the inflation front. Gold gained 0.54% to $3,873.90 as a modest risk-off tone persisted.
The Day Ahead
The focus shifts squarely to the UK labour market, with the headline unemployment rate, average earnings including bonuses, and employment change all scheduled for release. Unemployment was last reported at 4.7%, and any further deterioration would complicate the BoE's hawkish stance given the current 4.00% Bank Rate. Average earnings growth of 3.7% 3m/yr remains the key wage-pressure gauge for the MPC.
Tomorrow brings the critical October CPI release, with headline last at 3.5% YoY and core at 2.8% — a hot print would cement December hike expectations. Later in the week, GfK consumer confidence (previous -24) and Friday's retail sales (previous -0.4% MoM) will round out the domestic data flow.
Other Economic Notes
The UK consumer outlook remains fragile, with GfK confidence stuck deep in negative territory at -24 and retail sales having contracted 0.4% month-on-month in the prior reading. The labour market is the pivotal variable: with unemployment at 4.7% and vacancies softening, the tension between wage growth and employment cooling will determine how far the MPC can tighten. Sterling's slide to its weakest level against the dollar since mid-October, despite relatively firm UK activity data, suggests markets are pricing relative policy divergence rather than UK-specific weakness.
The steepening gilt curve — with 10-year yields at 5.32% while the 2-year sits at 4.74% — signals investors demanding greater term premium amid fiscal and inflation uncertainty.