UK Macro Daily(Beta Mode)
Unemployment Falls, Inflation Test Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,689.90 | -1.76% |
| FTSE 250 | 24,392.80 | -1.24% |
| GBP/USD | 1.32 | -0.00% |
| GBP/EUR | 1.20 | +0.12% |
| GBP/JPY | 210.00 | -0.15% |
| Brent Crude | 92.03 | -1.19% |
| Gold | 3,781.20 | -2.15% |
| UK Nat Gas | 3.17 | -1.06% |
| Bitcoin | 64,600.81 | -0.39% |
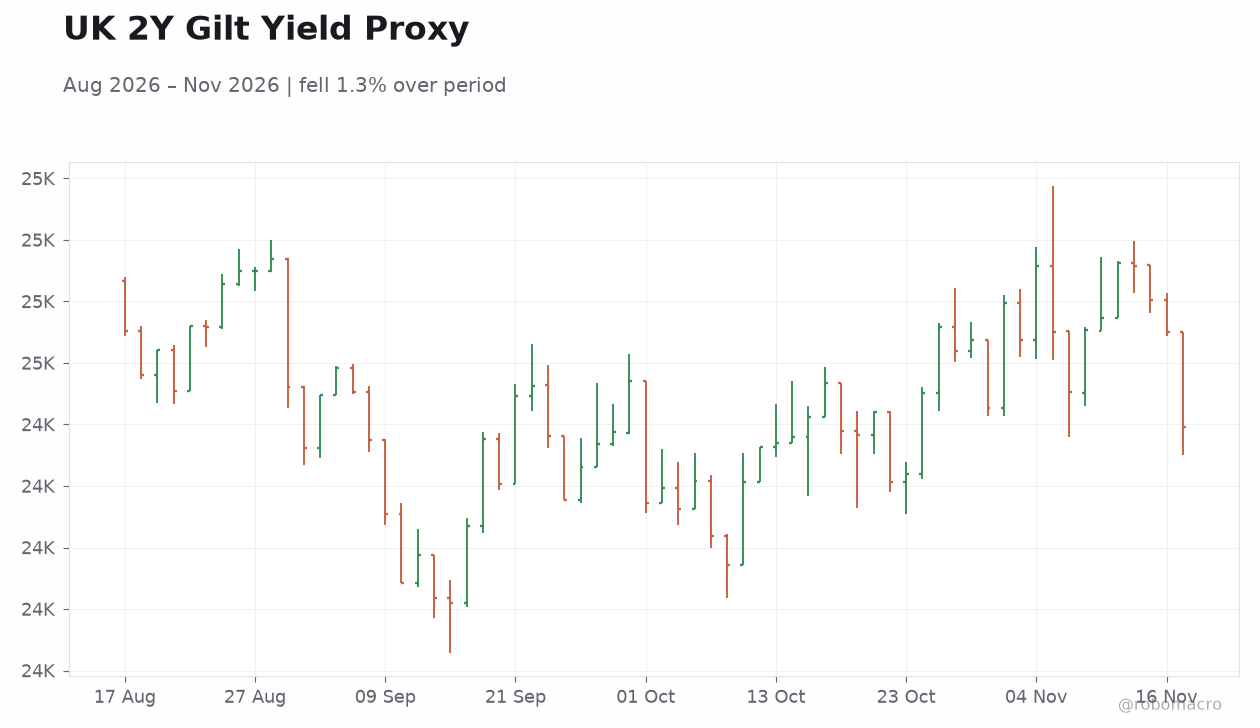
| UK 2Y Gilt | 4.77% | +3 bp |
| UK 10Y Gilt | 5.33% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 4.70 | 4.70 | 4.60 |
| Average Earnings incl. Bonus (3Mo/Yr) | 3.70 | - | 3.60 |
| Employment Change | 102,000 | - | 156,000 |
| BoE Mills Speech | - | - | - |
| Inflation Rate Year-over-Year | 3.50 | 3.70 | - |
| Core Inflation Rate Year-over-Year | 2.80 | 2.80 | - |
| Inflation Rate Month-over-Month | 0.40 | 0.50 | - |
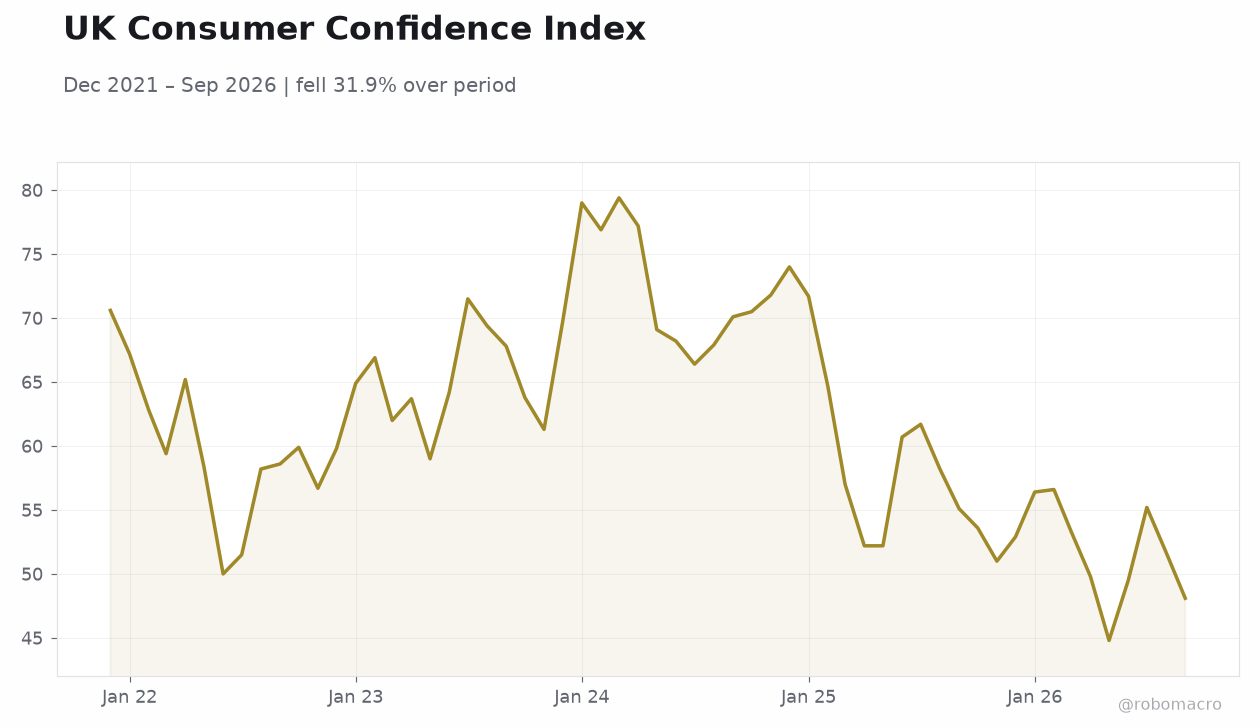 UK Consumer Confidence Index | Type: macro_line | Consumer Confidence: 48.1 (2026-09-01) | Range: 44.8–79.4 | Trend(6pt): 70.6,66.9,77.2,60.7,51.7,48.1
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Mutton Speech | - | - | 03:30 |
| BoE Braddick Speech | - | - | 09:00 |
| Thursday (2026-11-19) | |||
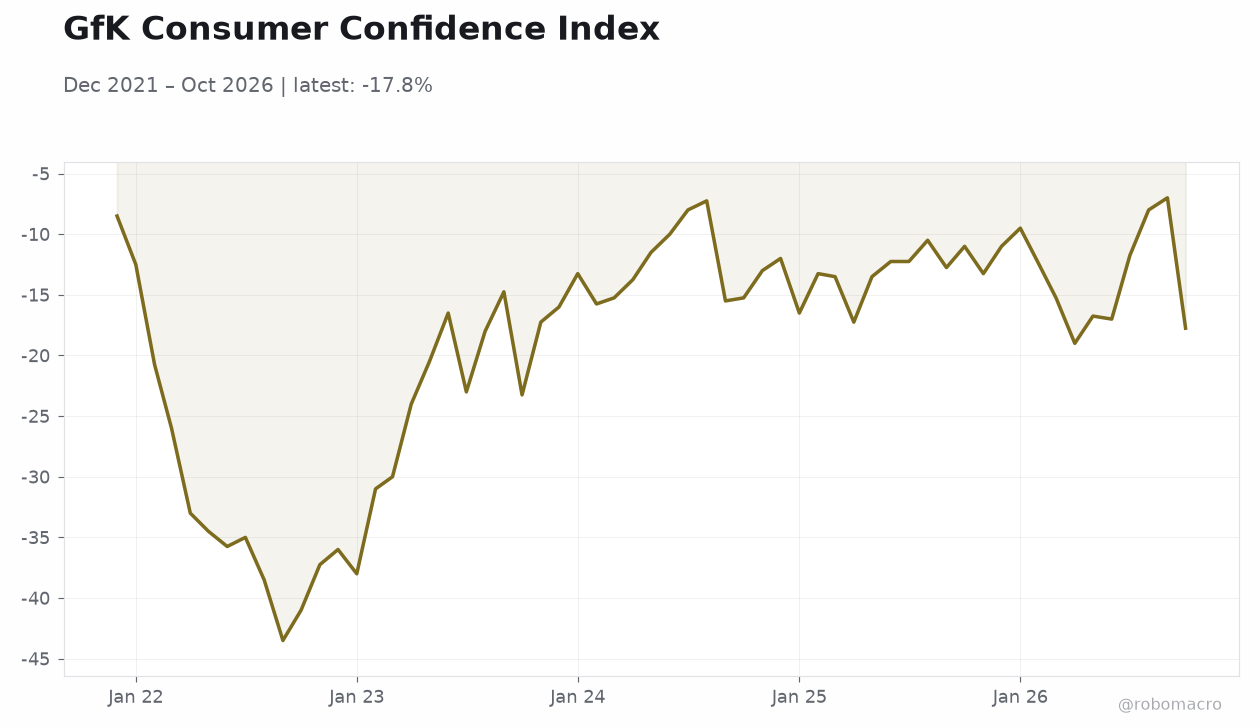
| GFK Consumer Confidence Index | -24 | -22 | 19:01 |
| Friday (2026-11-20) | |||
| Retail Sales Month-over-Month | -0.40 | 0 | 02:00 |
| Retail Sales Year-over-Year | 0.80 | - | 02:00 |
| CBI Industrial Trends Orders | -32 | -29 | 06:00 |
- UK unemployment fell to 4.6% in the latest release, below the 4.7% consensus, while employment rose by 156,000
- Sterling held near 1.32 against the dollar as gilt yields edged higher ahead of today's October CPI print
- Markets await October CPI at 3.7% consensus, with two BoE speeches scheduled and retail sales due Friday
Yesterday's Recap
The UK labour market delivered a mixed picture on 17 November. Headline unemployment fell to 4.6% from 4.7%, beating consensus, while employment change rose by 156,000, a solid improvement on the prior 102,000. However, average earnings including bonus slowed to 3.6% from 3.7%, signalling easing wage pressure.
Despite the ostensibly tighter labour market, UK assets sold off broadly: the FTSE 100 dropped 1.76% to 10,689.90 and the FTSE 250 fell 1.24% to 24,392.80. Gilt yields moved higher, with the 2-year up 3 bp to 4.77% and the 10-year up 1 bp to 5.33%. Sterling was roughly flat against the dollar at 1.32 but firmed 0.12% against the euro to 1.20.
BoE's Mills spoke late in the session, with markets parsing commentary for signals on the rate path.
The Day Ahead
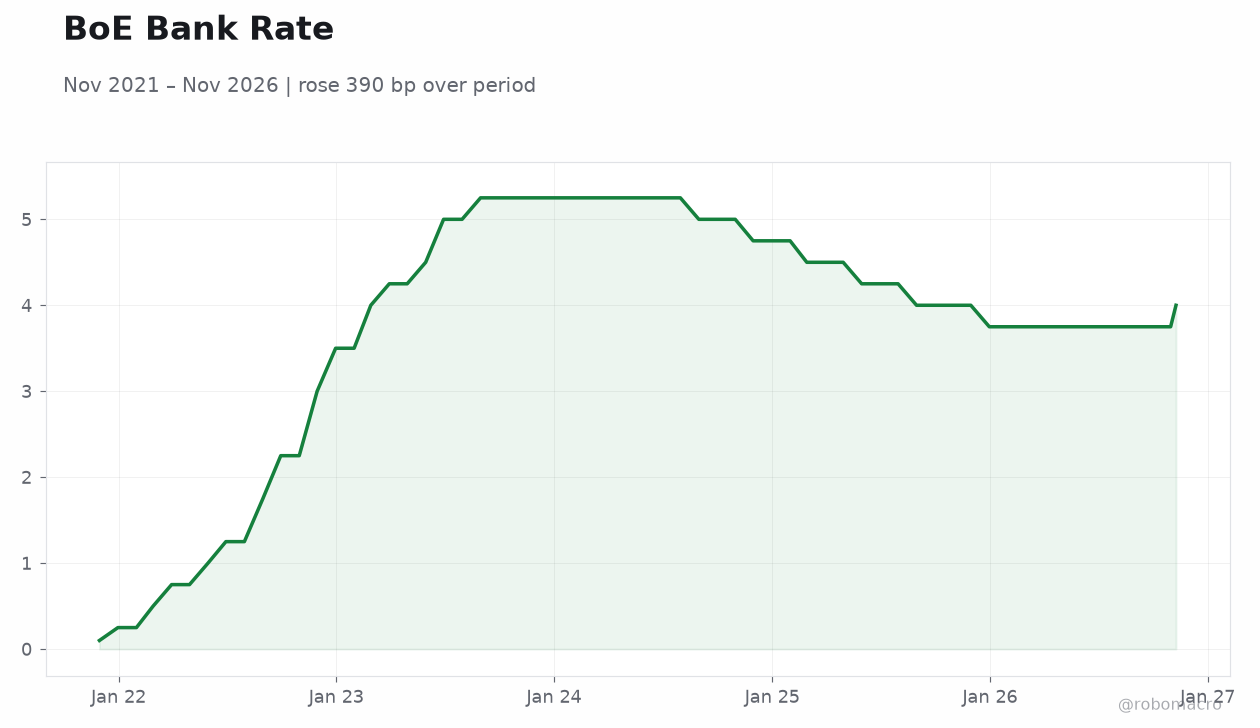
The critical event is October CPI at 02:00 ET, with headline year-over-year consensus at 3.7%, up from 3.5% previously, and month-over-month expected at 0.5%. Core inflation is seen steady at 2.8%. A print at or above consensus would reinforce the case for the BoE's recent tightening bias and likely pressure gilts further.
Two BoE speakers are scheduled: Mutton at 03:30 ET and Braddick at 09:00 ET, both high-impact, and markets will watch for any pushback against or endorsement of the hawkish tone. Later in the week, GFK consumer confidence (Thursday) and Friday's retail sales — expected flat month-over-month after a 0.4% decline — will gauge household resilience.
Other Economic Notes
The labour data carries caveats, with the FT noting warnings over data quality even as employment improved. Firms are reportedly planning the largest round of job cuts since the pandemic, a forward-looking signal that may temper optimism over the headline unemployment decline. Productivity data confirmed a third-quarter boost, offering some offset to weak activity indicators.
Niesr has warned that the BoE's cautious approach to rate rises could prolong high borrowing costs. Goldman Sachs has raised the question of whether the UK economy can beat expectations again in 2027, suggesting upside risks to growth forecasts remain live.