UK Macro Daily(Beta Mode)
Inflation Climbs, BoE Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,551.17 | -1.30% |
| FTSE 250 | 24,364.20 | -0.12% |
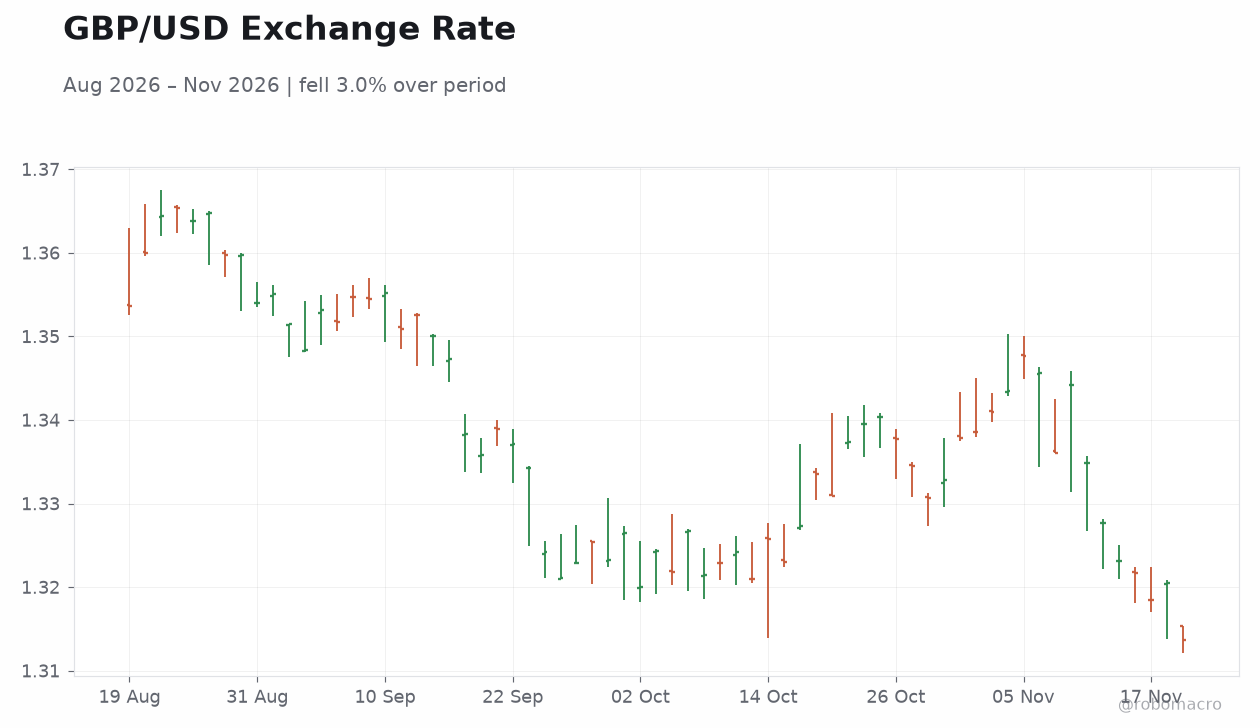
| GBP/USD | 1.31 | -0.52% |
| GBP/EUR | 1.20 | -0.32% |
| GBP/JPY | 209.56 | -0.50% |
| Brent Crude | 89.31 | -2.87% |
| Gold | 3,737.80 | -0.11% |
| UK Nat Gas | 3.37 | -0.03% |
| Bitcoin | 63,371.09 | -2.35% |
| UK 2Y Gilt | 4.79% | +2 bp |
| UK 10Y Gilt | 5.37% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 4.70 | 4.70 | 4.60 |
| Average Earnings incl. Bonus (3Mo/Yr) | 3.70 | - | 3.60 |
| Employment Change | 102,000 | - | 156,000 |
| BoE Mills Speech | - | - | - |
| Inflation Rate Year-over-Year | 3.50 | 3.70 | 3.60 |
| Core Inflation Rate Year-over-Year | 2.80 | 2.80 | 2.80 |
| Inflation Rate Month-over-Month | 0.40 | 0.50 | 0.50 |
| BoE Mutton Speech | - | - | - |
| BoE Braddick Speech | - | - | - |
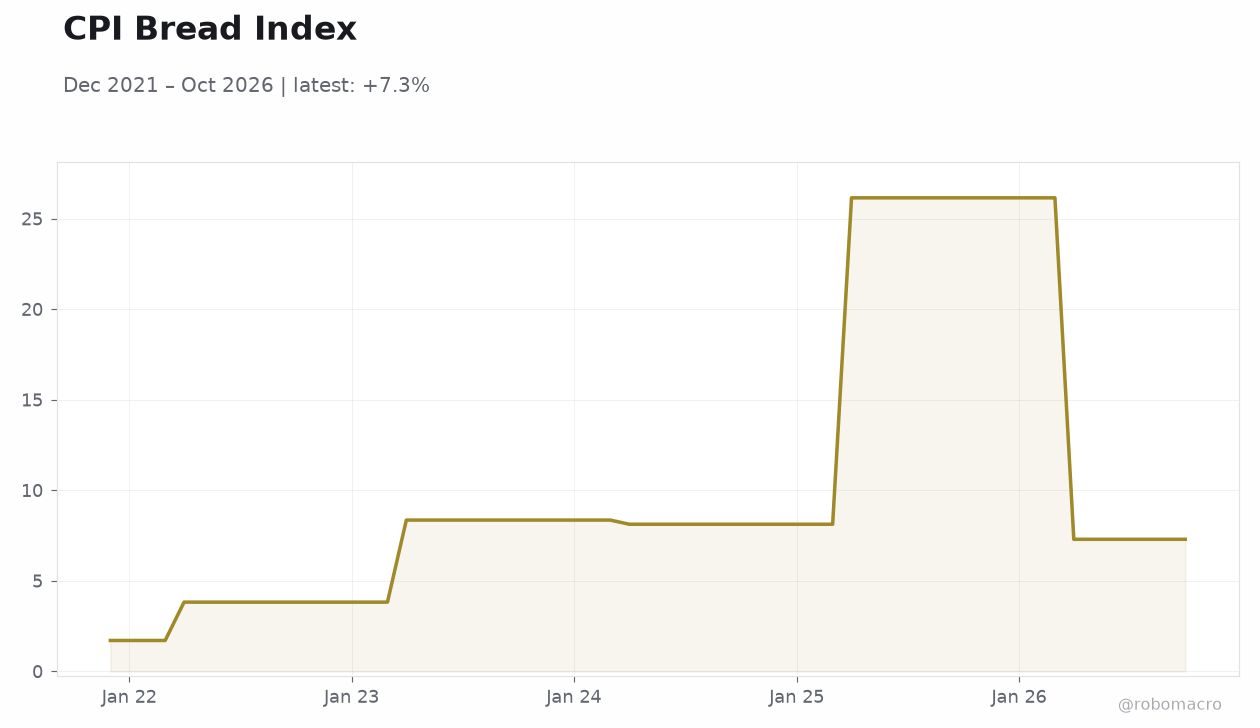 CPI Bread Index | Type: macro_line | CPI Bread YoY (%): 7.295 (2026-10-01) | Range: 1.708–26.15 | Trend(5pt): 1.708,3.825,8.126,26.15,7.295
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GFK Consumer Confidence Index | -24 | -22 | 19:01 |
| Friday (2026-11-20) | |||
| Retail Sales Month-over-Month | -0.40 | 0 | 02:00 |
| Retail Sales Year-over-Year | 0.80 | - | 02:00 |
| CBI Industrial Trends Orders | -32 | -29 | 06:00 |
- UK October CPI rose to 3.6% YoY, a one-year high, with core steady at 2.8% and MoM at 0.5%, keeping pressure on the Bank of England.
- Unemployment fell to 4.6% while employment rose 156,000 and average earnings eased to 3.6%, a mixed labour picture.
- Gilts sold off, with 10Y at 5.37% (+4bp) and 2Y at 4.79% (+2bp); sterling slipped 0.52% against the dollar to 1.31.
Yesterday's Recap
UK labour data released 17 November showed the headline unemployment rate at 4.6%, below the 4.7% consensus, with employment change at 156,000 and average earnings including bonus easing to 3.6% from 3.7%. October CPI, released 18 November, printed at 3.6% YoY against a 3.7% consensus and up from 3.5% previously, a one-year high, while core inflation held at 2.8% and the monthly rate came in at 0.5% as expected. Sterling fell 0.52% against the dollar to 1.31 and 0.32% against the euro to 1.20, with GBP/JPY down 0.50% to 209.56.
The FTSE 100 dropped 1.30% to 10,551.17 and the FTSE 250 slipped 0.12% to 24,364.20. Gilt yields pushed higher, the 10-year rising 4bp to 5.37% and the 2-year up 2bp to 4.79%. Brent crude fell 2.87% to $89.31, gold eased 0.11% to $3,737.80 and Bitcoin dropped 2.35% to $63,371.
BoE speeches from Mills, Mutton and Braddick rounded out a heavy UK calendar.
The Day Ahead
The GFK consumer confidence index for November is due at 19:01 ET, with consensus at -22 versus -24 previously. Friday 20 November brings October retail sales at 02:00 ET, where the MoM consensus is flat at 0% following a -0.4% prior, alongside the YoY series with a prior of 0.8%. CBI industrial trends orders for November are scheduled for 06:00 ET, with consensus at -29 against -32 previously.
These releases will be watched closely for signs of consumer resilience and manufacturing weakness after the inflation surprise. No further BoE speakers are scheduled in the immediate window.
Other Economic Notes
The combination of rising headline inflation and falling unemployment complicates the policy path, with the labour market showing tentative stabilisation even as earnings growth cools. Core inflation holding at 2.8% suggests underlying price pressure remains sticky, limiting room for complacency. Consumer confidence remains deeply negative, and the retail sales print will test whether households are retrenching further.
CBI orders data will gauge whether the industrial sector is stabilising after a prolonged contraction. The inflation outlook is increasingly testing market confidence in the BoE's price target.