UK Macro Daily(Beta Mode)
Inflation Stays Hot as Confidence Slumps
Market Snapshot
| Asset | Level | Change |
|---|---|---|
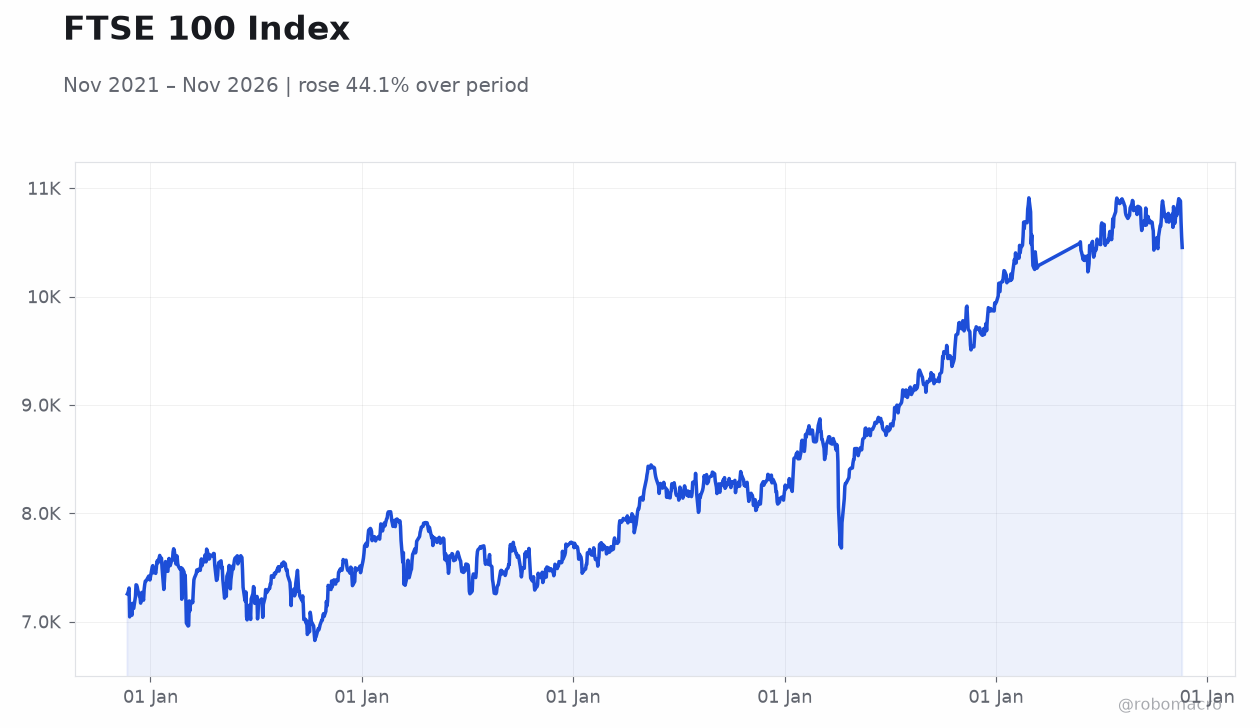
| FTSE 100 | 10,452.70 | -0.93% |
| FTSE 250 | 24,192.20 | -0.71% |
| GBP/USD | 1.31 | -0.22% |
| GBP/EUR | 1.19 | -0.38% |
| GBP/JPY | 208.82 | -0.34% |
| Brent Crude | 89.88 | -2.28% |
| Gold | 3,561.40 | -3.37% |
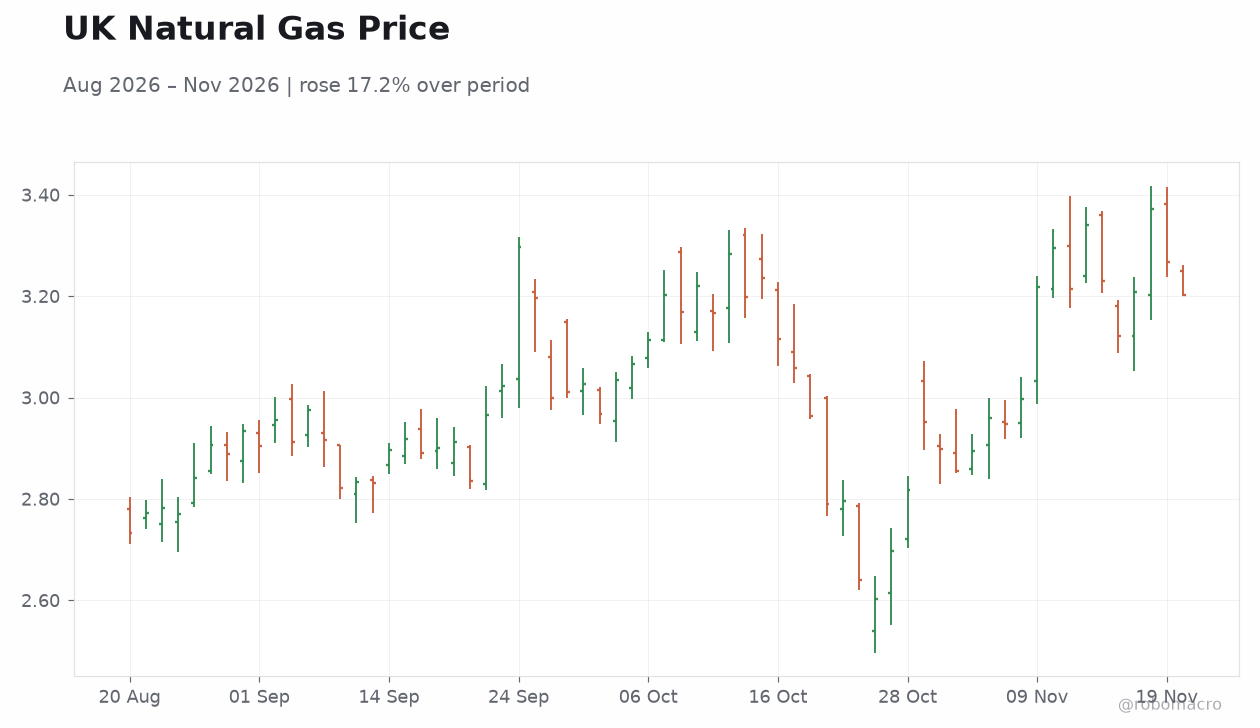
| UK Nat Gas | 3.20 | -2.05% |
| Bitcoin | 61,943.81 | -1.66% |
| UK 2Y Gilt | 4.71% | -8 bp |
| UK 10Y Gilt | 5.29% | -8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 4.70 | 4.70 | 4.60 |
| Average Earnings incl. Bonus (3Mo/Yr) | 3.70 | - | 3.60 |
| Employment Change | 102,000 | - | 156,000 |
| BoE Mills Speech | - | - | - |
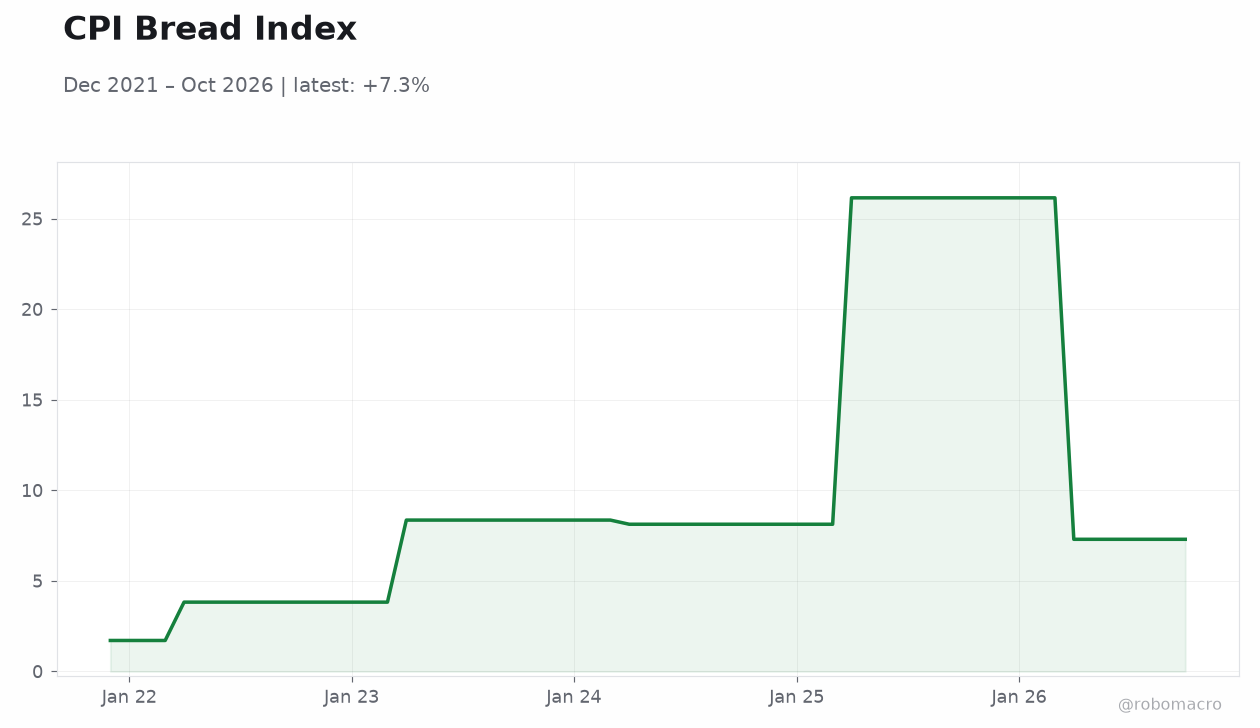
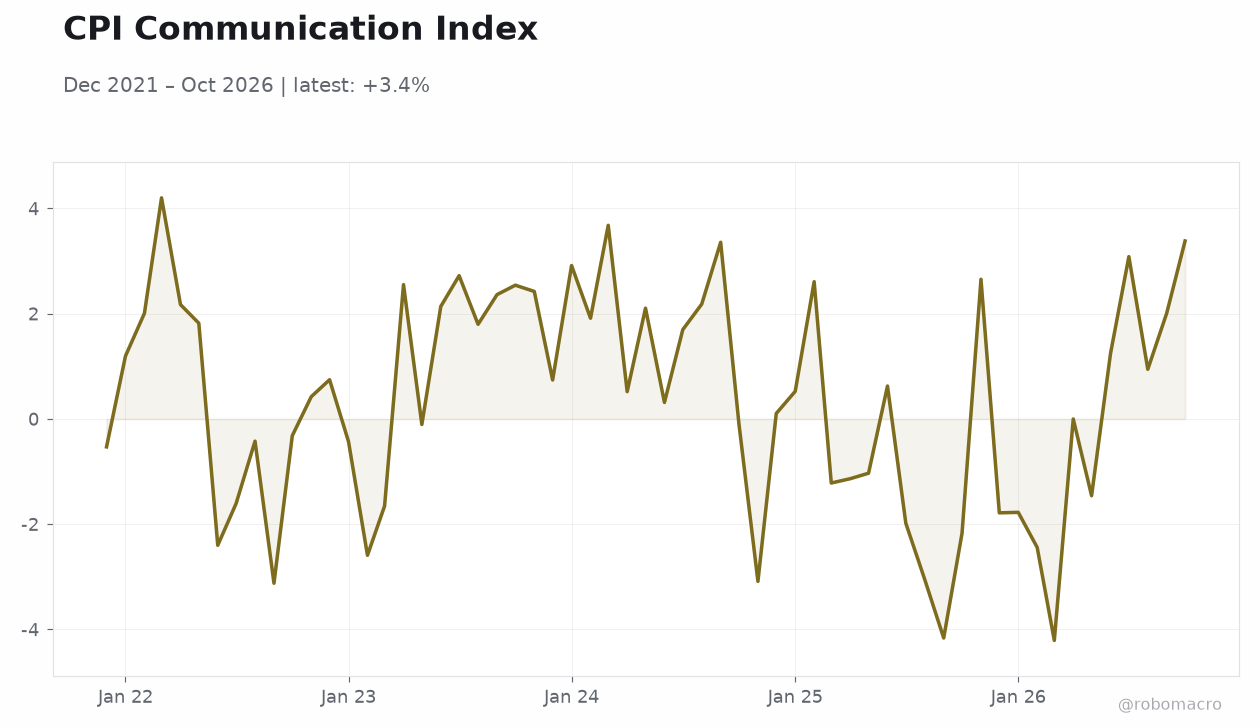
| Inflation Rate Year-over-Year | 3.50 | 3.70 | 3.60 |
| Core Inflation Rate Year-over-Year | 2.80 | 2.80 | 2.80 |
| Inflation Rate Month-over-Month | 0.40 | 0.50 | 0.50 |
| BoE Mutton Speech | - | - | - |
| BoE Braddick Speech | - | - | - |
| CBI Industrial Trends Orders | -32 | -29 | -12 |
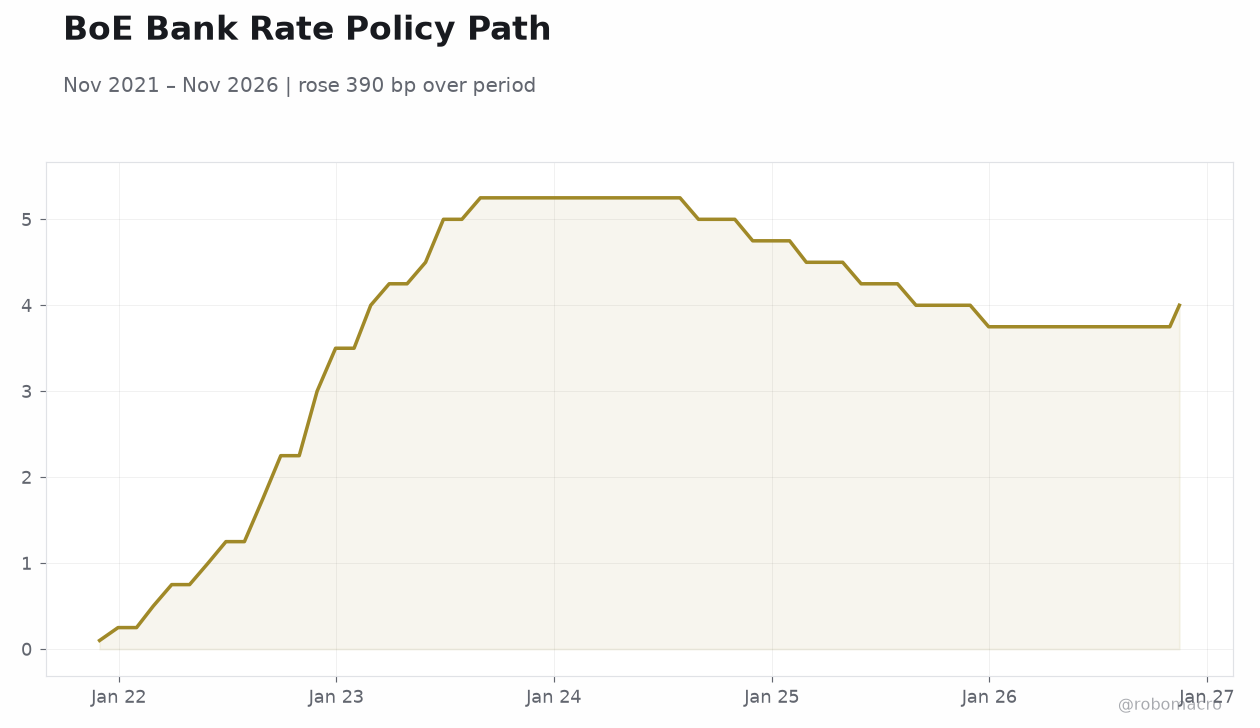 BoE Bank Rate Policy Path | Type: macro_line | Policy Rate (%): 4 (2026-11-16) | Range: 0.1–5.25 | Trend(5pt): 0.1,4,5.25,4,4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- October CPI rose 3.6% YoY, below the 3.7% consensus but still well above target, with core inflation steady at 2.8%
- Unemployment unexpectedly fell to 4.6% while wage growth slowed to 3.6%, painting a mixed labour picture
- Gilts rallied 8bp across the curve even as equities sold off on weak consumer confidence and BoE inflation warnings
Yesterday's Recap
October CPI printed at 3.6% YoY versus consensus of 3.7%, easing from the prior 3.5% but remaining materially above the 2% target; the monthly reading came in at 0.5% as expected, while core inflation held at 2.8%. Earlier in the week, the unemployment rate unexpectedly declined to 4.6% against a 4.7% consensus, and employment change jumped to 156,000, though average earnings including bonuses slowed to 3.6% from 3.7%. The CBI Industrial Trends Orders gauge improved sharply to -12 from -32 previously, comfortably beating the -29 consensus and signalling a less severe contraction in manufacturing order books.
GfK consumer confidence for November printed at -22 versus -24 prior, in line with consensus. Despite the sticky inflation backdrop, gilts rallied with both the 2-year and 10-year yields easing 8bp to 4.71% and 5.29% respectively. Equities were weaker, with the FTSE 100 down 0.93% to 10,452.70 and the FTSE 250 off 0.71%, while sterling softened across the board, GBP/USD falling 0.22% to 1.31.
Commodities were broadly lower, with Brent crude down 2.28% to $89.88 and gold tumbling 3.37% to $3,561.40.
The Day Ahead
The focus shifts to this morning's October retail sales release at 07:00 ET, with consensus expecting flat month-on-month growth following the prior 0.4% contraction, and year-on-year consensus of 1.7% versus 0.8% previously. No further BoE speakers are scheduled after yesterday's Lombardelli appearance, leaving markets to digest this week's dense data flow. Attention will increasingly turn to the 17 December MPC decision, the final meeting of the year, where the committee must weigh persistent services inflation against a softening labour market.
With the Bank Rate at 4.00% following November's 25bp hike, the bar for a near-term reversal remains high given CPI still sits at 3.6%.
Other Economic Notes
The combination of falling unemployment, robust employment growth and decelerating wage growth suggests the labour market is cooling gradually rather than cracking, which complicates the BoE's easing calculus. Consumer confidence remains deeply negative, and the FTSE 100's slide alongside weakening sentiment points to household caution feeding through to discretionary spending. ↓ p.2