US Macro Daily(Beta Mode)
Yields Diverge as Equities Finish Mixed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,650.50 | +0.17% |
| Nasdaq 100 | 29,644.17 | +0.67% |
| Dow Jones | 51,682.64 | -0.18% |
| Russell 2000 | 2,860.40 | -0.50% |
| USD/JPY | 157.24 | +0.71% |
| EUR/USD | 1.15 | +0.09% |
| GBP/USD | 1.34 | +0.22% |
| Gold | 4,381.80 | -0.97% |
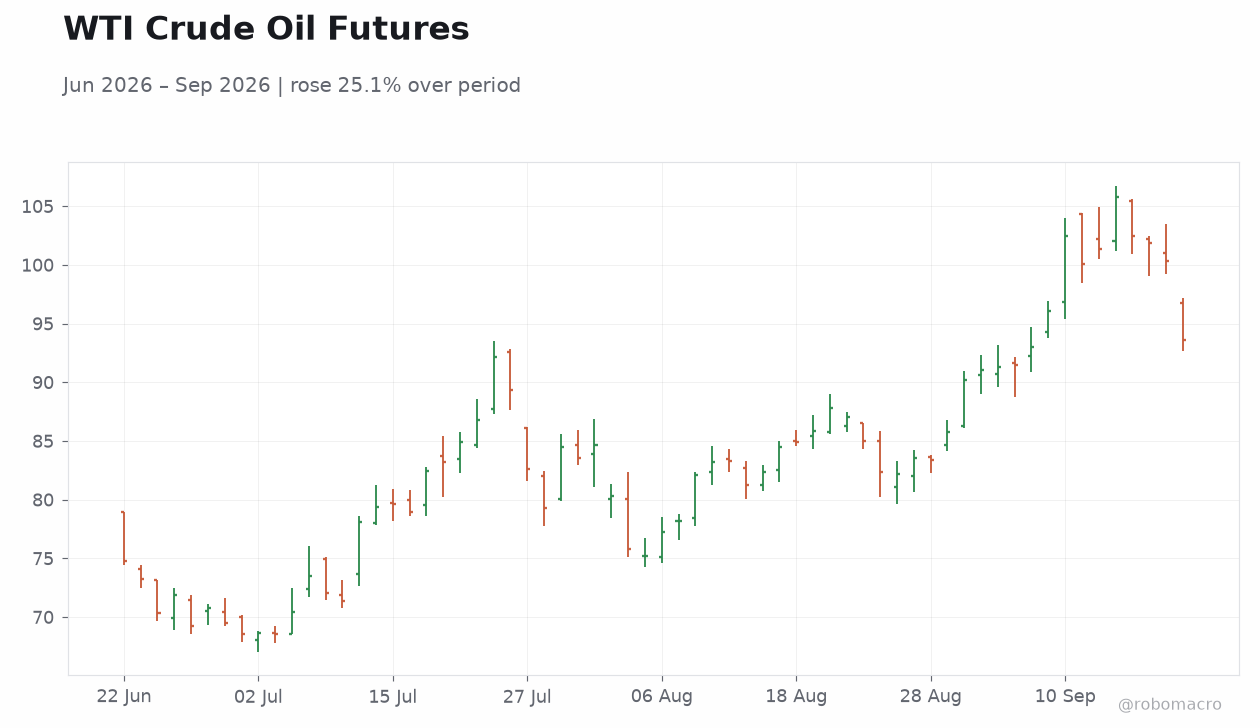
| WTI Crude | 93.61 | -6.67% |
| Bitcoin | 84,530.00 | +4.17% |
| US 2Y Treasury | 4.74% | +7 bp |
| US 10Y Treasury | 4.94% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Goolsbee | - | - | - |
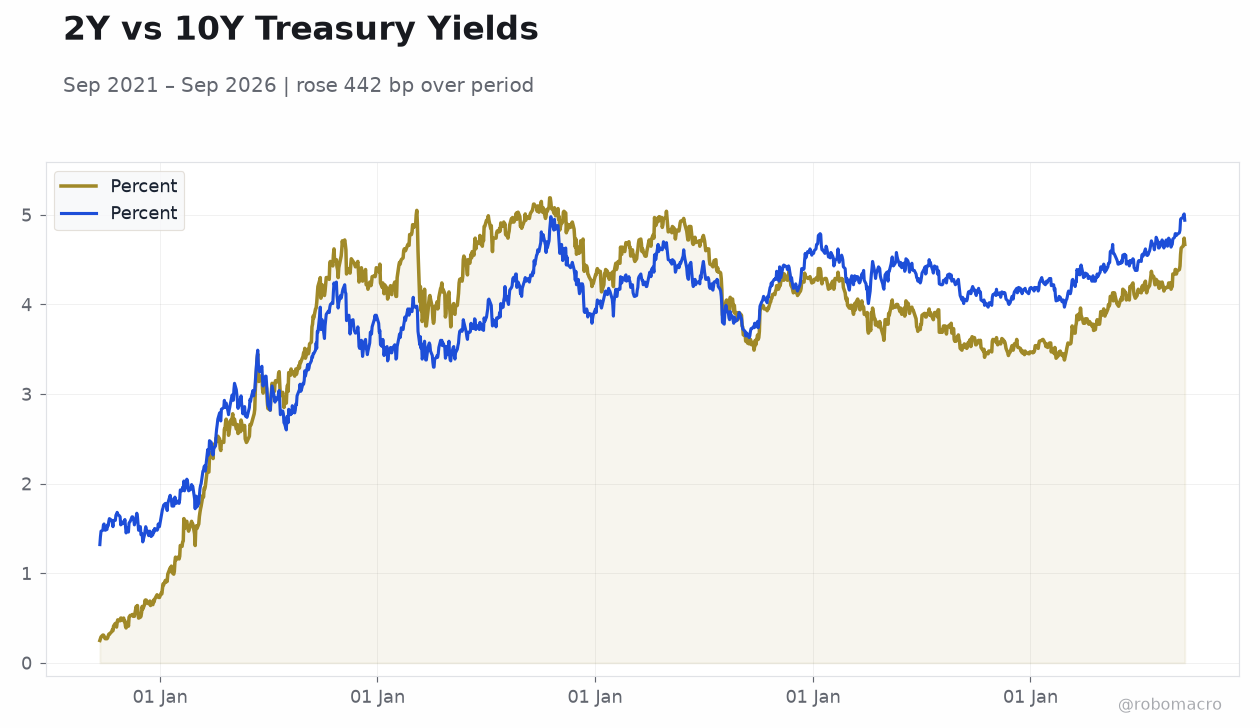 2Y vs 10Y Treasury Yields | Type: macro_line | Percent: 4.67 (2026-09-17) | Range: 0.25–5.19 | Trend(6pt): 0.25,4.21,4.59,3.94,4.74,4.67 | Percent: 4.94 (2026-09-17) | Range: 1.32–5.01 | Trend(6pt): 1.32,3.68,4.27,4.38,5.01,4.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Chicago Fed National Activity Index | -0.08 | - | 04:30 |
| Tuesday (2026-09-22) | |||
| ADP Employment Change Weekly | 16,250 | - | 04:15 |
| Speech by Fed's Williams | - | - | 06:05 |
| Speech by Fed's Jefferson | - | - | 06:20 |
| Speech by Fed's Barkin | - | - | 09:00 |
| API Weekly Crude Oil Stocks | 7.1m | - | 12:30 |
| Wednesday (2026-09-23) | |||
| MBA 30-Year Mortgage Rate | 6.97 | - | 03:00 |
| S&P Global Composite PMI Flash | 56 | - | 05:45 |
- Equities closed mixed with Nasdaq 100 up 0.67% while Dow fell 0.18%
- 2-year yield rose 7 bp to 4.74% as 10-year eased 7 bp to 4.94%
- Attention turns to Chicago Fed index and upcoming Fed speeches
Yesterday's Recap
Equity indices finished mixed on September 20. The S&P 500 rose 0.17% to 7,650.50 while the Nasdaq 100 gained 0.67% to 29,644.17. The Dow Jones declined 0.18% to 51,682.64 and the Russell 2000 fell 0.50% to 2,860.40.
WTI Crude dropped 6.67% to 93.61 and gold declined 0.97% to 4,381.80. Bitcoin advanced 4.17% to 84,530.00. The 2-year Treasury yield increased 7 bp to 4.74% while the 10-year yield declined 7 bp to 4.94%.
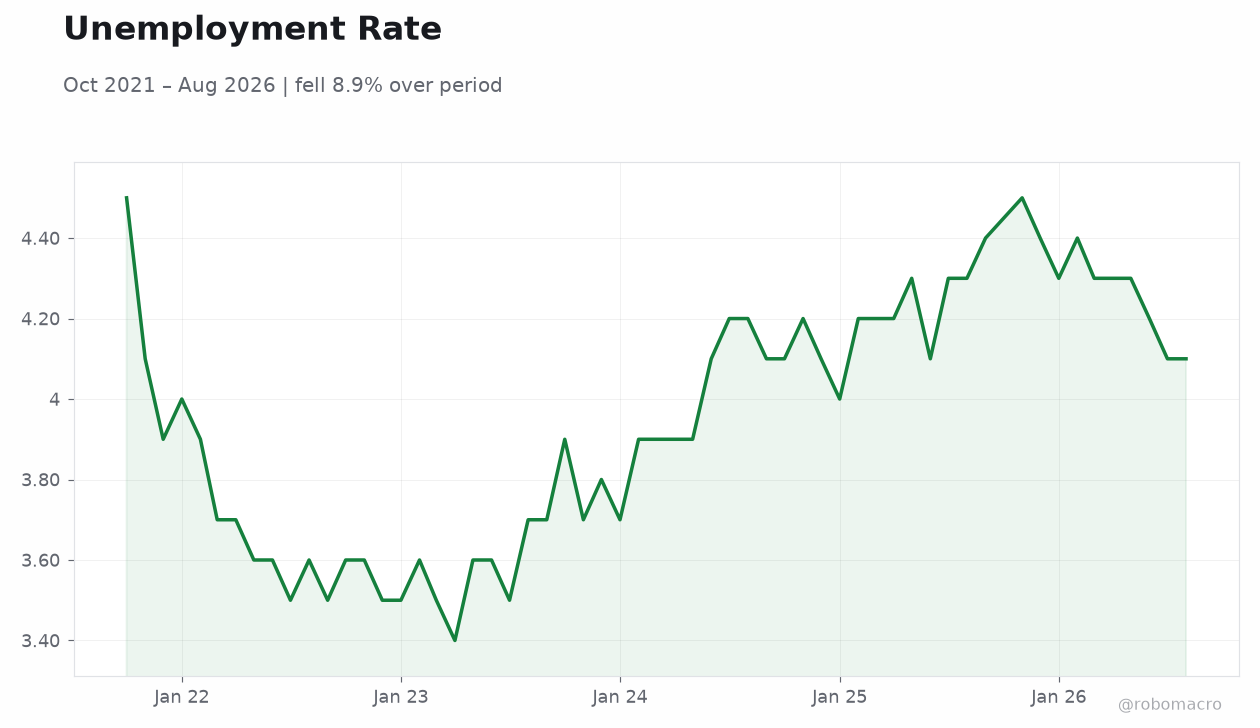
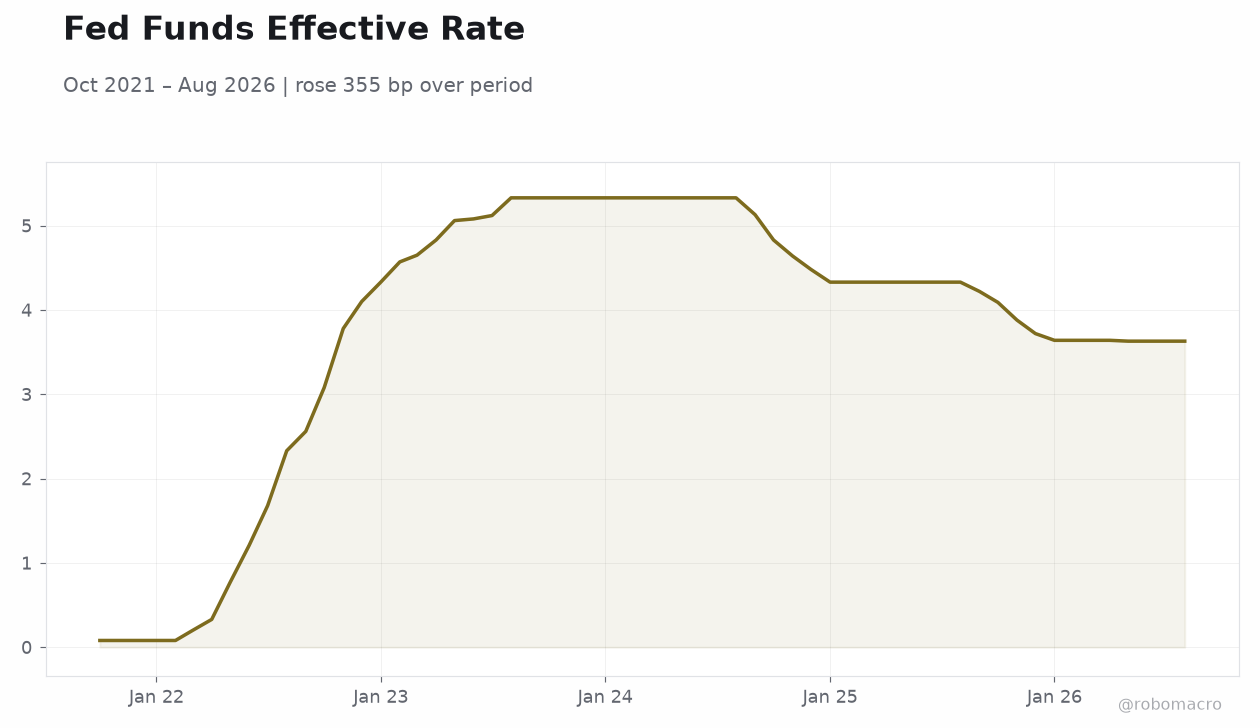
USD/JPY climbed 0.71% to 157.24. The only scheduled event was a medium-impact speech by Fed's Goolsbee with no data releases reported. Broader market moves occurred against a backdrop of moderate US GDP growth at 1.50% QoQ SAAR and 2.10% YoY, retail sales up 6.01% YoY, unemployment at 4.10%, and CPI at 3.40% YoY, with the Fed Funds Rate at 3.88%.
The Day Ahead
The Chicago Fed National Activity Index releases at 04:30 ET today with no consensus available. Tomorrow brings the ADP Employment Change Weekly at 04:15 ET along with speeches from Fed's Williams, Jefferson, and Barkin. API Weekly Crude Oil Stocks follow at 12:30 ET.
Wednesday features S&P Global Composite, Manufacturing, and Services PMI flashes at 05:45 ET with Manufacturing consensus at 53.5 and Services at 56.0. EIA inventory data also prints that morning. These releases will provide fresh signals on activity and inflation expectations ahead of further Fed commentary.
Market participants will watch for any revisions to prior readings that could alter views on the pace of expansion given the latest GDP and retail sales figures.
Other Economic Notes
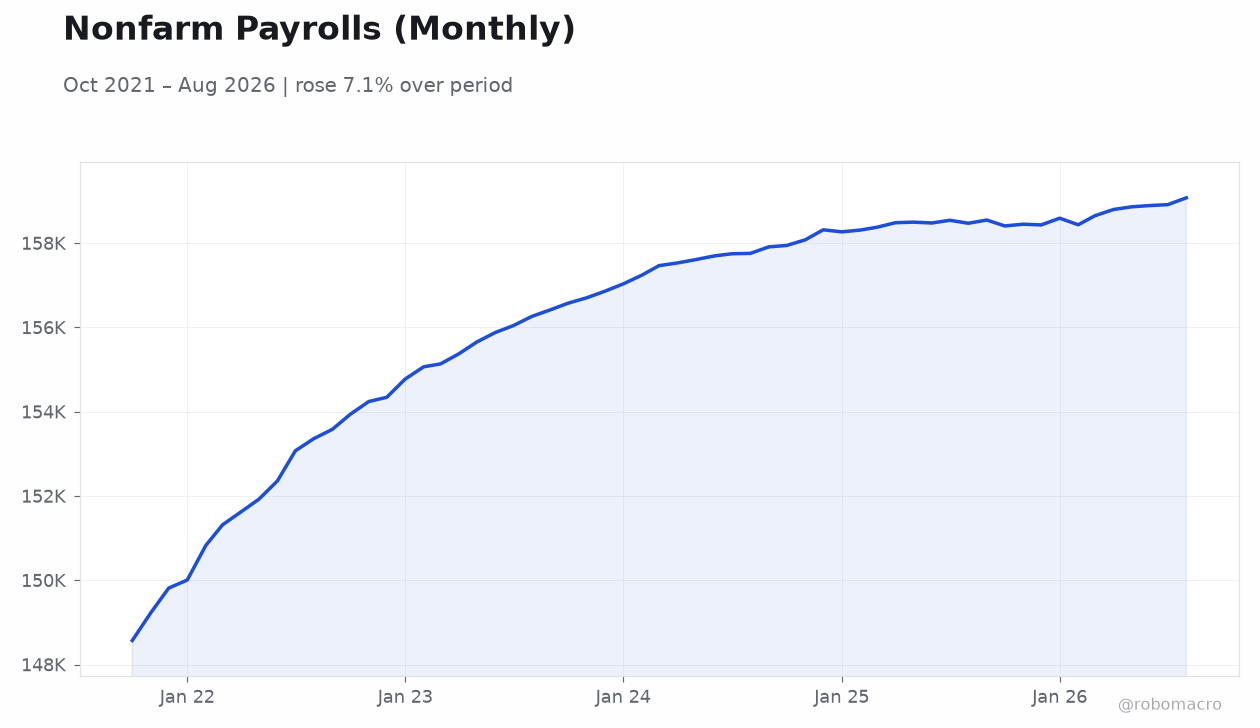
US GDP growth registered 1.50% QoQ SAAR and 2.10% YoY in the latest reading. Retail sales expanded 6.01% YoY while unemployment held at 4.10%. CPI inflation stood at 3.40% YoY.
The Fed Funds Rate remains at 3.88%. These figures indicate moderate expansion alongside contained price pressures and a stable labor market. Market participants will monitor whether incoming PMI prints confirm this trajectory or signal shifts in momentum.
The combination of steady growth and anchored inflation supports expectations that policy will remain data-dependent without abrupt adjustments.