US Macro Daily(Beta Mode)
Equities Rally as Yields Rise Despite Soft Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
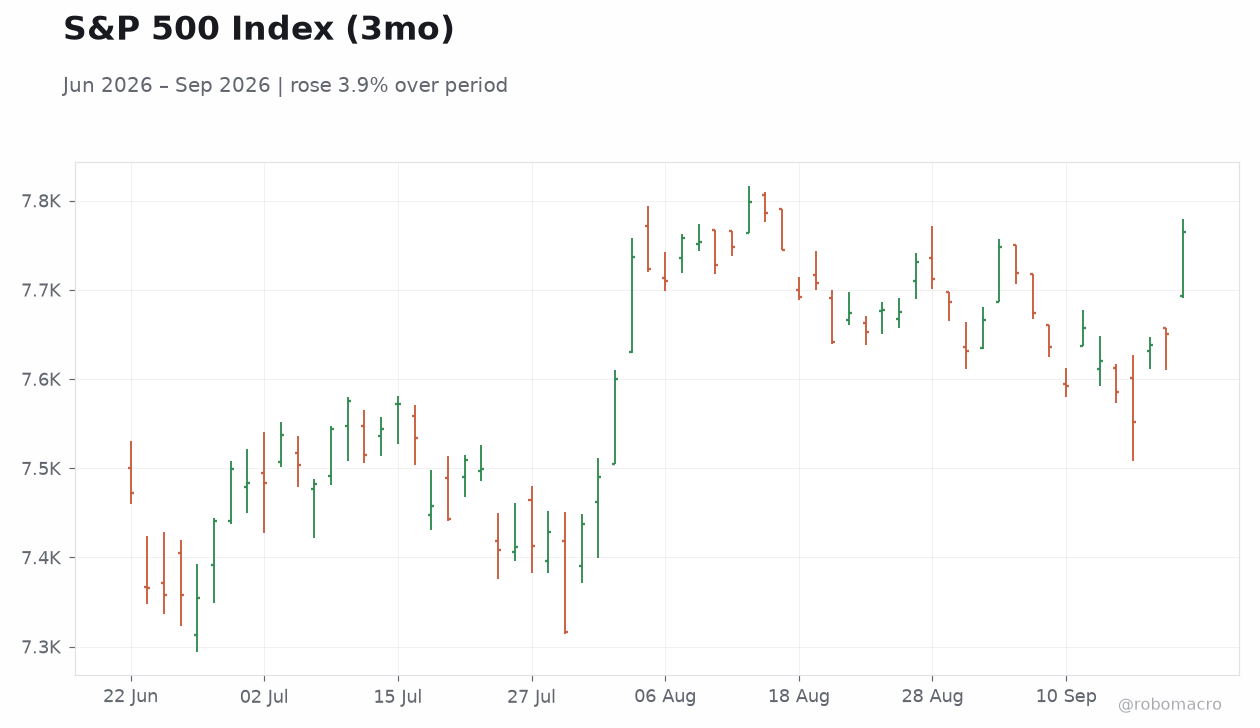
| S&P 500 | 7,764.70 | +1.49% |
| Nasdaq 100 | 30,482.35 | +2.83% |
| Dow Jones | 52,048.83 | +0.71% |
| Russell 2000 | 2,875.36 | +0.52% |
| USD/JPY | 157.05 | +0.59% |
| EUR/USD | 1.15 | -0.11% |
| GBP/USD | 1.34 | -0.18% |
| Gold | 4,360.80 | -0.53% |
| WTI Crude | 90.10 | -5.93% |
| Bitcoin | 85,961.21 | -0.74% |
| US 2Y Treasury | 4.74% | +7 bp |
| US 10Y Treasury | 5.01% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Goolsbee | - | - | - |
| Chicago Fed National Activity Index | 0.08 | - | -0.04 |
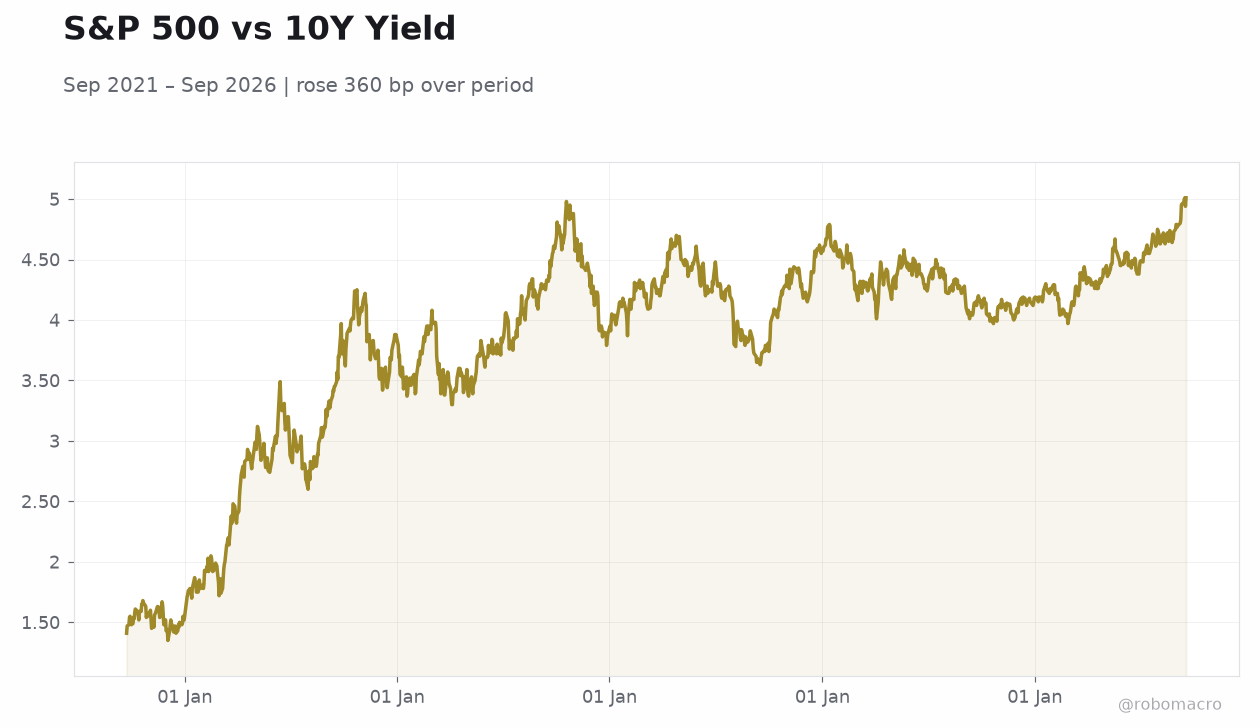 S&P 500 vs 10Y Yield | Type: macro_line | 10Y Yield %: 5.01 (2026-09-18) | Range: 1.35–5.01 | Trend(6pt): 1.41,3.67,4.27,4.38,4.94,5.01
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ADP Employment Change Weekly | 16,250 | - | 04:15 |
| Speech by Fed's Williams | - | - | 06:05 |
| Speech by Fed's Jefferson | - | - | 06:20 |
| Speech by Fed's Barkin | - | - | 09:00 |
| API Weekly Crude Oil Stocks | 7.1m | - | 12:30 |
- S&P 500 rises 1.49% while 10-year yield reaches 5.01%
- Chicago Fed index slips to -0.04, signaling softer activity
- WTI crude falls 5.93% to $90.10 ahead of inventory data
Yesterday's Recap
US equity indices posted broad gains on September 21, with the S&P 500 closing at 7,764.70, up 1.49%, the Nasdaq 100 surging 2.83% to 30,482.35, the Dow Jones advancing 0.71% to 52,048.83, and the Russell 2000 rising 0.52% to 2,875.36. Treasury yields increased, with the 2-year reaching 4.74% and the 10-year hitting 5.01%, both up 7 basis points. The Chicago Fed National Activity Index printed -0.04, weaker than the prior 0.08 reading.
WTI crude declined sharply to 90.10, down 5.93%, while gold eased 0.53% to 4,360.80 and Bitcoin fell 0.74% to 85,961.21. In FX, USD/JPY climbed 0.59% to 157.05, EUR/USD slipped 0.11% to 1.15, and GBP/USD declined 0.18% to 1.34. A medium-impact speech by Chicago Fed President Goolsbee occurred but produced limited immediate market reaction.
The Day Ahead
Markets will focus on the ADP Employment Change Weekly release at 4:15 ET, which follows the prior 16,250 reading and may influence near-term labor views. Three Federal Reserve speakers appear today: Williams at 6:05 ET, Jefferson at 6:20 ET, and Barkin at 9:00 ET, each likely to address inflation persistence and the policy path. The API Weekly Crude Oil Stocks report at 12:30 ET will precede the EIA inventory data tomorrow and could drive energy price volatility.
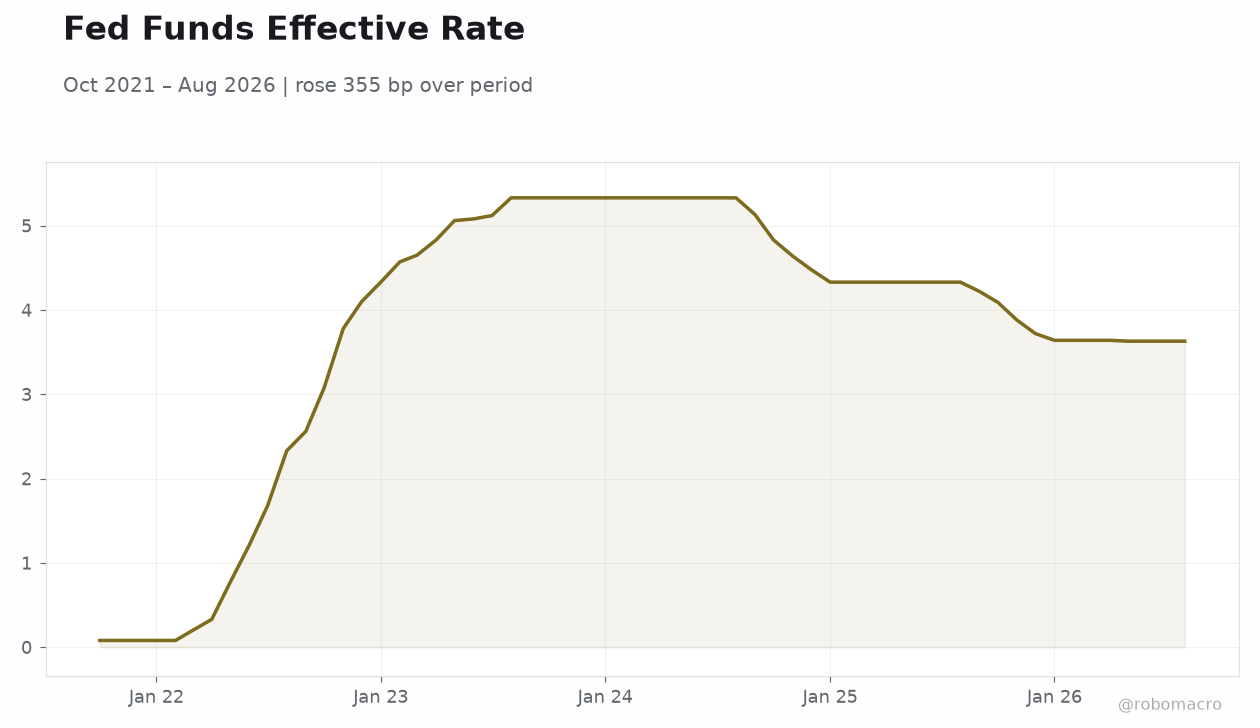
With the Fed Funds rate at 3.88% and CPI YoY at 3.40%, any hawkish commentary may reinforce expectations for a higher terminal rate. Equity sentiment remains tied to growth signals, while USD crosses will react to yield differentials.
Other Economic Notes
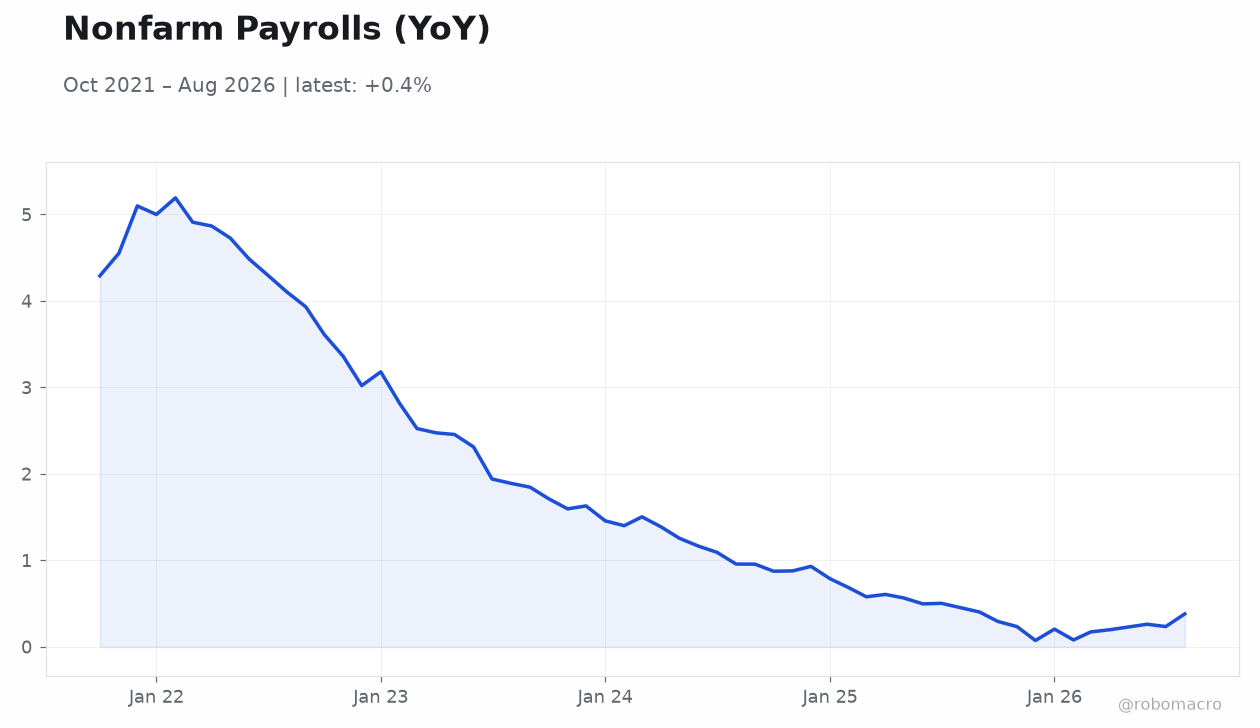
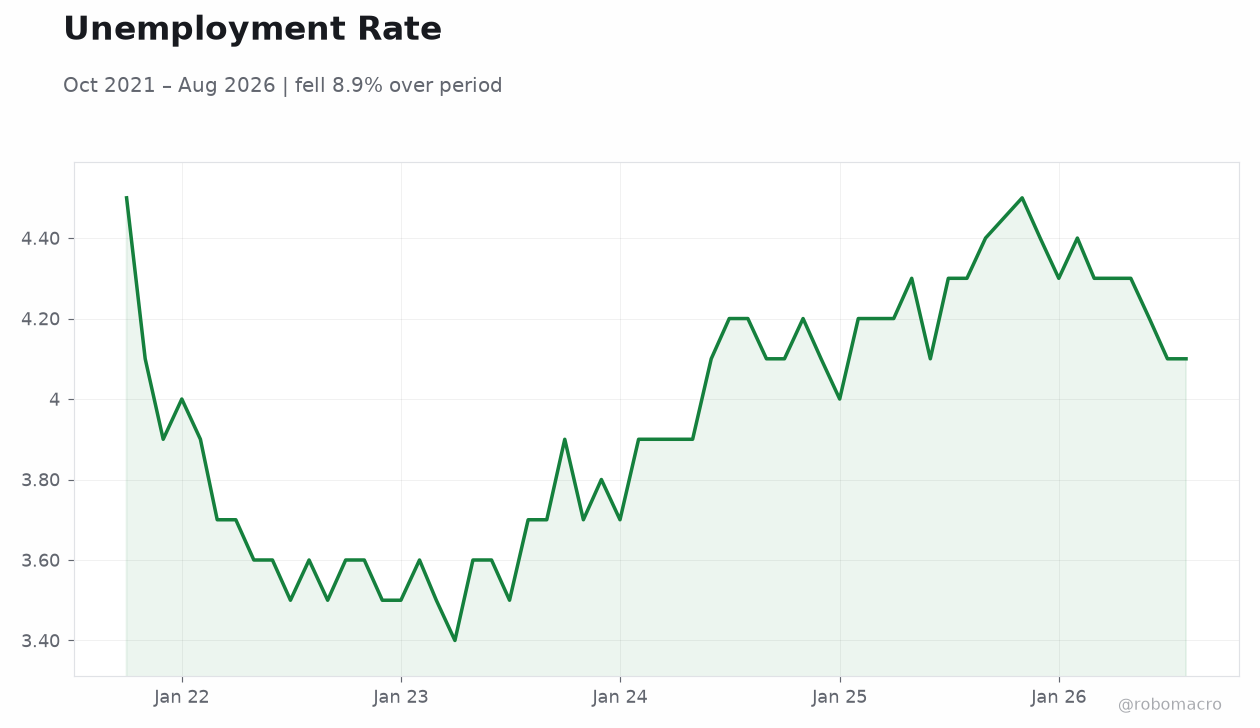
US GDP growth registered 1.50% QoQ SAAR and 2.10% YoY in the latest reading, while retail sales expanded 6.01% YoY and unemployment stood at 4.10%. These figures, alongside the 3.40% CPI print, indicate an economy that continues to run above trend despite cooling in some activity gauges. Rising Treasury yields reflect investor reassessment of growth and inflation risks, with the 10-year at 5.01% pricing in a more restrictive policy stance for longer.
Energy price weakness may provide some relief to headline inflation but leaves core measures elevated.
Global Macro News
US-China trade commitments show uneven progress ahead of any potential Trump-Xi meeting, keeping tariff and supply-chain risks in focus for US manufacturers. ↓ p.2