US Macro Daily(Beta Mode)
Yields Rise as Data Calendar Stays Quiet
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,758.65 | -0.08% |
| Nasdaq 100 | 30,597.17 | +0.38% |
| Dow Jones | 51,737.16 | -0.60% |
| Russell 2000 | 2,886.42 | +0.38% |
| USD/JPY | 157.83 | +0.29% |
| EUR/USD | 1.14 | -0.39% |
| GBP/USD | 1.33 | -0.59% |
| Gold | 4,351.20 | -0.58% |
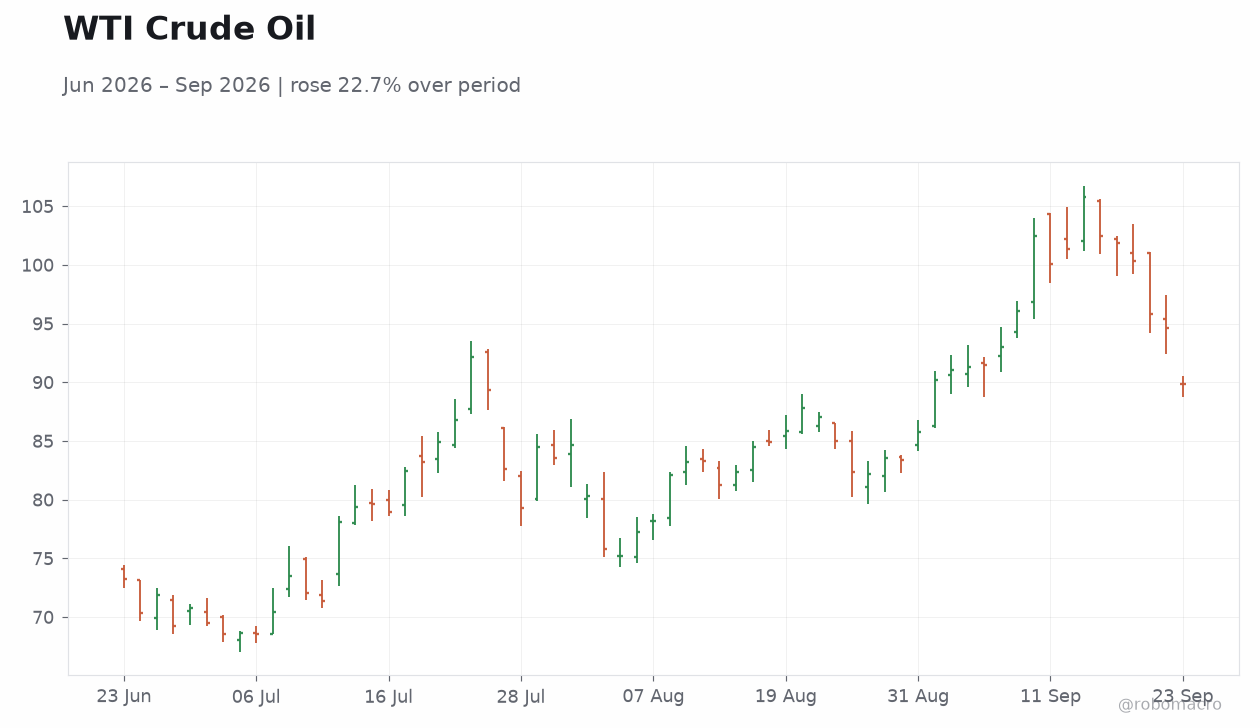
| WTI Crude | 89.97 | -4.88% |
| Bitcoin | 85,935.62 | -0.27% |
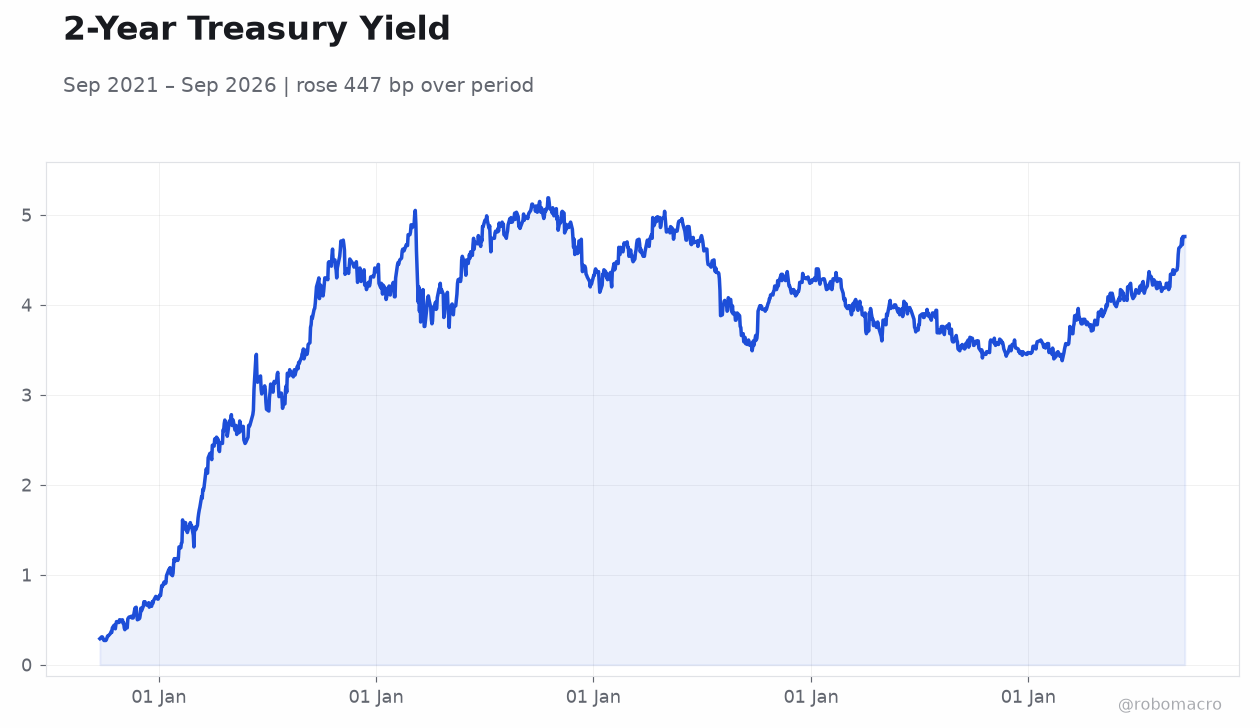
| US 2Y Treasury | 4.74% | +7 bp |
| US 10Y Treasury | 5.01% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
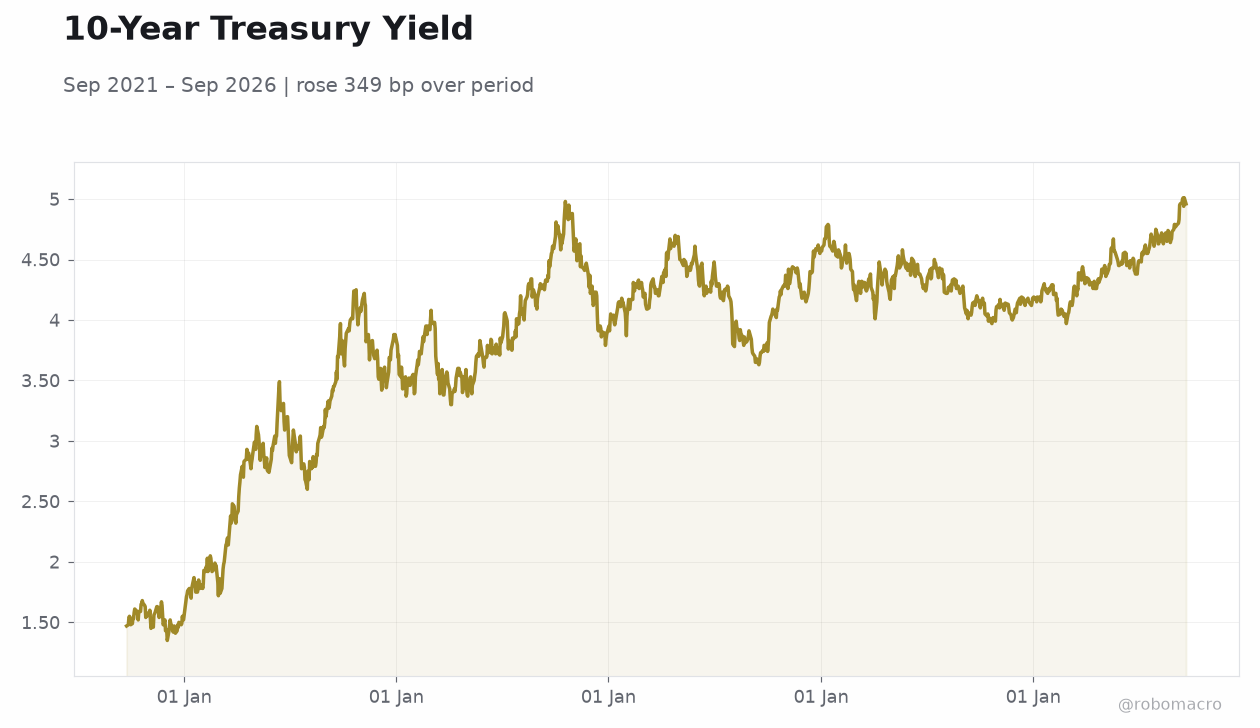 10-Year Treasury Yield | Type: macro_line | Percent: 4.96 (2026-09-21) | Range: 1.35–5.01 | Trend(6pt): 1.47,3.75,4.22,4.34,5.01,4.96
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Equities mixed as Nasdaq 100 gains 0.38% while Dow falls 0.60%
- 2-year and 10-year Treasury yields each climb 7 bp to 4.74% and 5.01%
- WTI crude drops 4.88% to $89.97 with no US data releases
Yesterday's Recap
Equity markets closed mixed on September 22. The S&P 500 edged down 0.08% to 7,758.65 while the Nasdaq 100 advanced 0.38% to 30,597.17. The Dow Jones declined 0.60% to 51,737.16 and the Russell 2000 rose 0.38% to 2,886.42.
Treasury yields increased across the curve with the 2-year yield rising 7 bp to 4.74% and the 10-year yield also adding 7 bp to 5.01%. WTI crude fell sharply by 4.88% to $89.97 and gold slipped 0.58% to $4,351.20. The USD/JPY pair advanced 0.29% to 157.83 while EUR/USD declined 0.39% to 1.14.
No economic data releases occurred.
The Day Ahead
No US economic releases or Federal Reserve events are scheduled for September 23. Markets will monitor any updates on the pending Paramount-Warner Bros. Discovery merger following the settlement of state lawsuits.
Traders will also track oil price movements after the sharp decline. Equity futures point to a muted open with attention on Treasury yield direction. Broader sentiment remains shaped by the absence of fresh inflation or growth figures.
Other Economic Notes
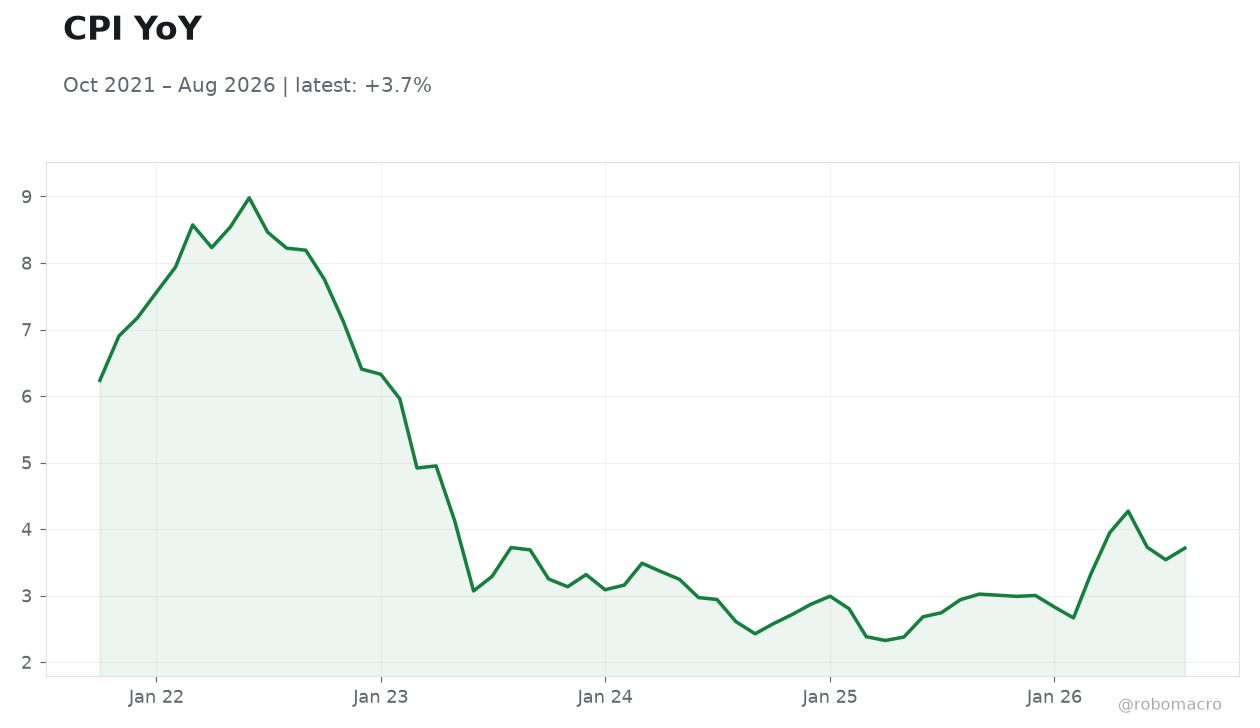
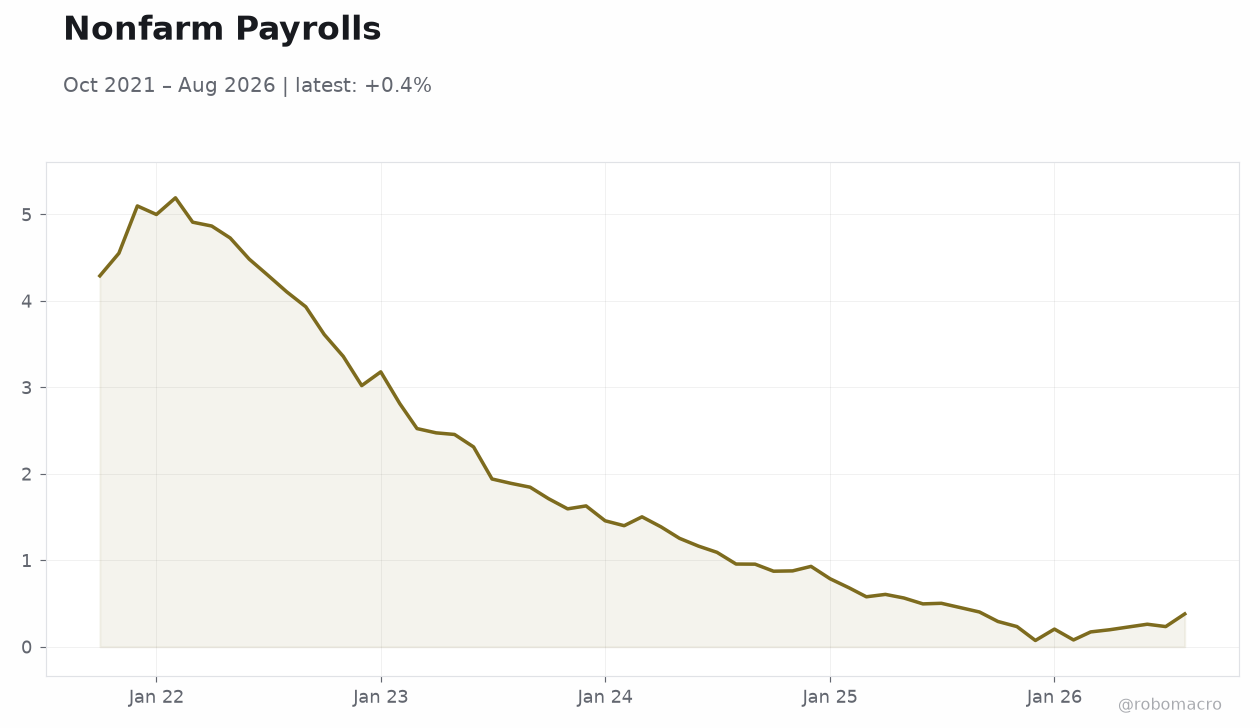
US GDP growth registered 1.50% QoQ SAAR and 2.10% YoY in the latest reading. Retail sales expanded 6.01% YoY while the unemployment rate stood at 4.10%. CPI inflation held at 3.40% YoY.
These figures underscore a moderate growth environment with contained but persistent price pressures. The Fed funds rate remains at 3.88%. Market participants continue to assess how sticky inflation interacts with the ongoing AI-driven expansion.
Global Macro News
Oil prices declined further on speculation of progress in US-Iran talks. The yen showed limited hawkish signals, keeping USD/JPY near 157.60 and highlighting policy divergence with the Federal Reserve. New Zealand’s central bank flagged risks to households and housing from its inflation fight.
UK foreign currency reserves data drew limited immediate market reaction. Global equities advanced in London as oil weakness supported sentiment. The strength of the US dollar continued to weigh on gold prices.
↓ p.2