US Macro Daily(Beta Mode)
Yields Climb on Hawkish Fed Signals
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,706.03 | -0.68% |
| Nasdaq 100 | 30,470.29 | -0.41% |
| Dow Jones | 51,511.59 | -0.44% |
| Russell 2000 | 2,838.66 | -1.65% |
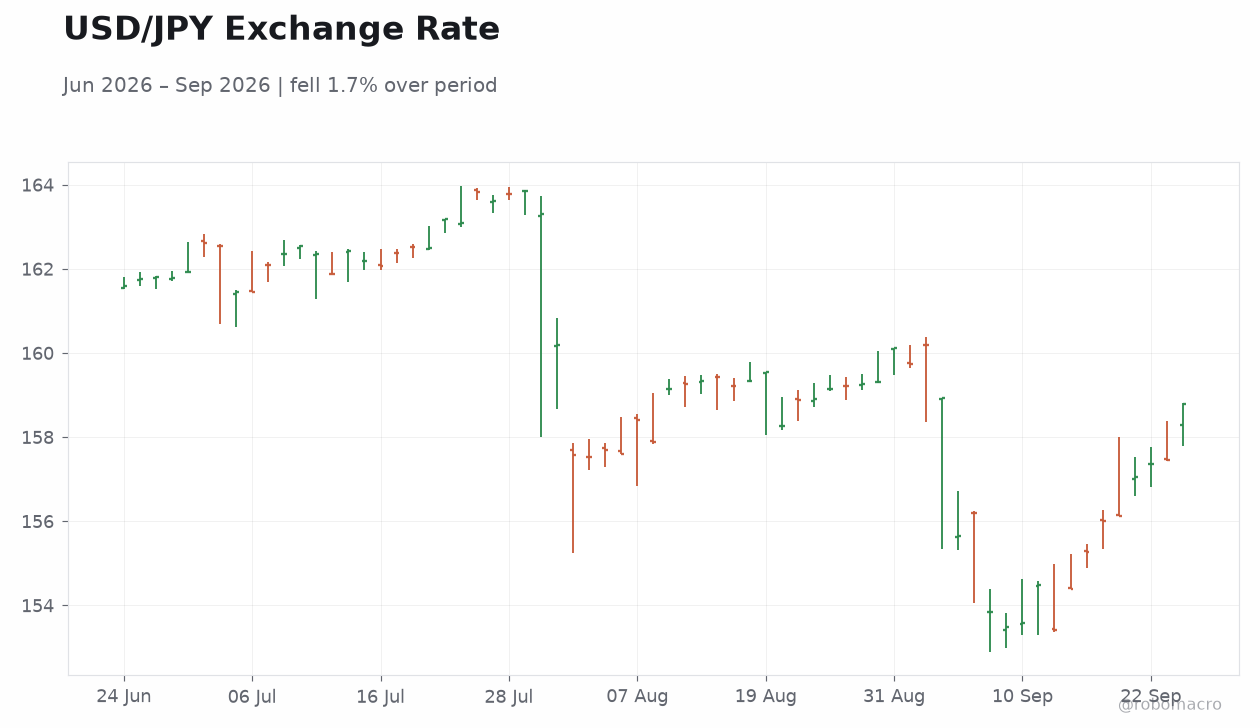
| USD/JPY | 158.78 | +0.83% |
| EUR/USD | 1.14 | -0.61% |
| GBP/USD | 1.32 | -0.86% |
| Gold | 4,300.00 | -0.43% |
| WTI Crude | 93.42 | +1.37% |
| Bitcoin | 83,482.06 | -1.07% |
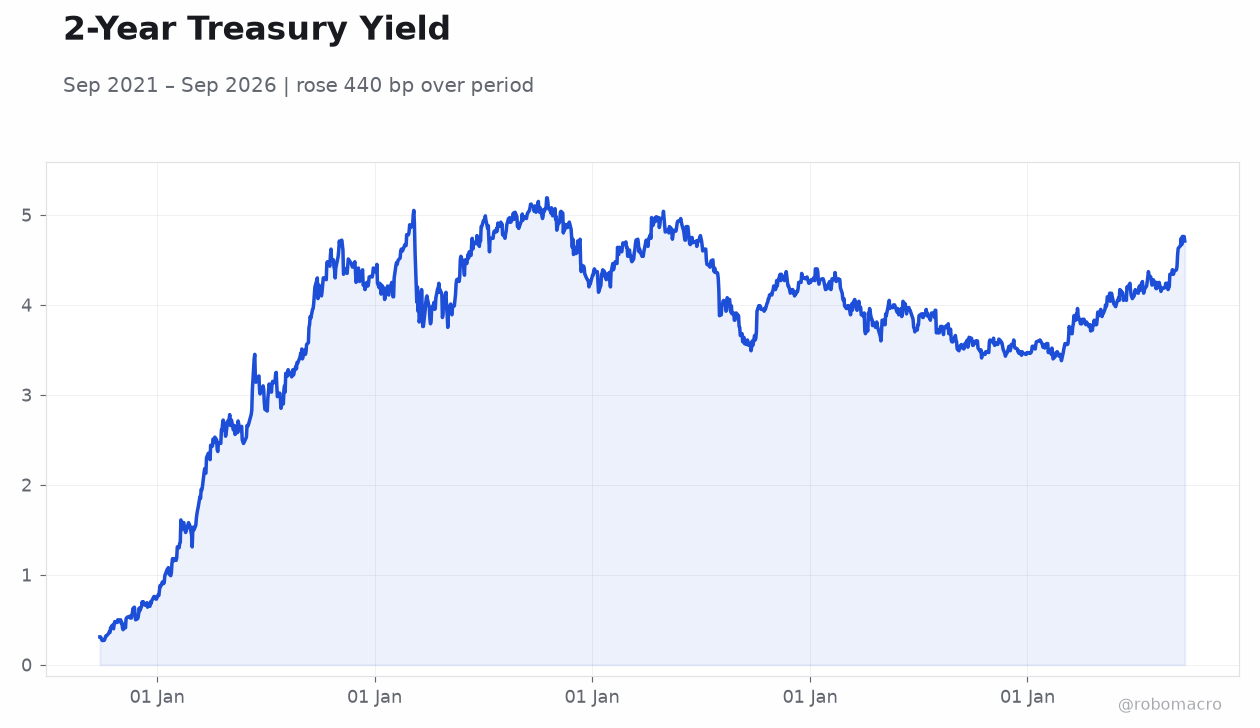
| US 2Y Treasury | 4.74% | +7 bp |
| US 10Y Treasury | 5.01% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
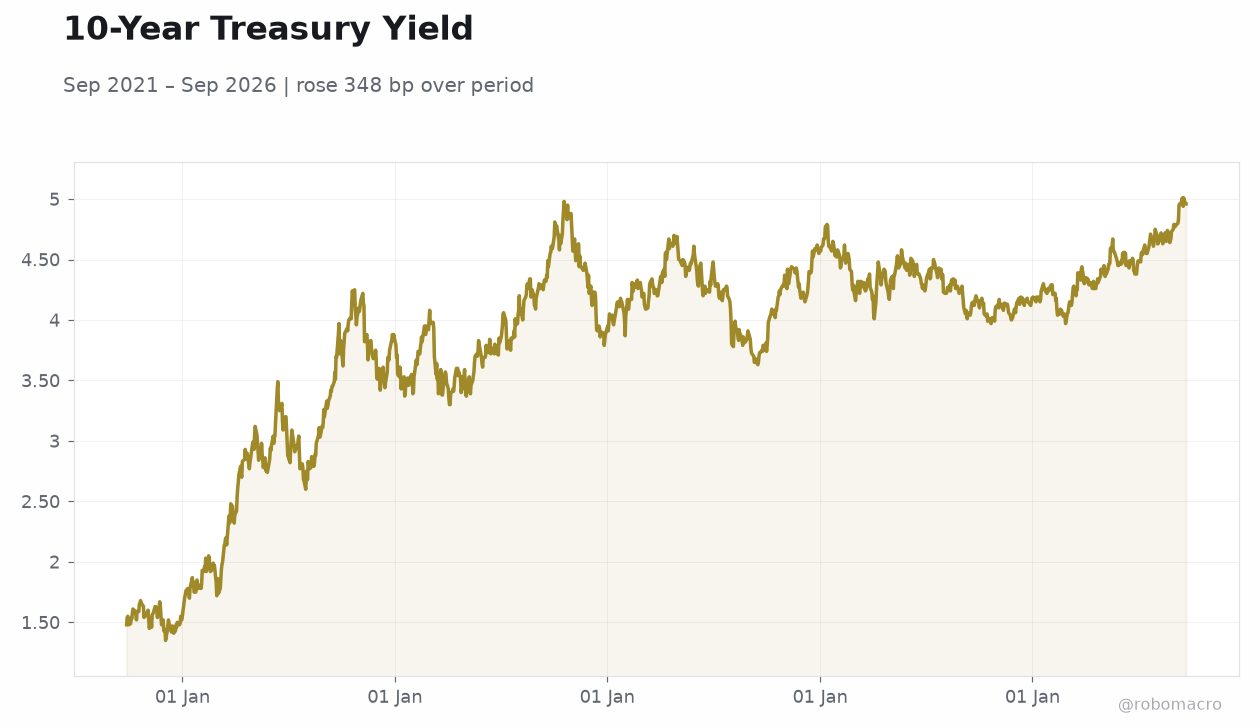 10-Year Treasury Yield | Type: macro_line | Percent: 4.96 (2026-09-22) | Range: 1.35–5.01 | Trend(5pt): 1.48,3.84,4.25,4.3,4.96
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Equities fall as 10-year yield hits 5.01%
- No US data releases reported yesterday
- USD strengthens versus euro and yen
Yesterday's Recap
Equity indices closed lower across the board. The S&P 500 fell 0.68% to 7,706.03 while the Nasdaq 100 declined 0.41% to 30,470.29. The Dow Jones slipped 0.44% to 51,511.59 and the Russell 2000 dropped 1.65% to 2,838.66.
Treasury yields rose sharply, with the 2-year yield climbing 7 bp to 4.74% and the 10-year yield advancing 7 bp to 5.01%. In FX markets, USD/JPY rose 0.83% to 158.78 while EUR/USD fell 0.61% to 1.14 and GBP/USD declined 0.86% to 1.32. WTI Crude gained 1.37% to 93.42 as gold eased 0.43% to 4,300.00.
Bitcoin declined 1.07% to 83,482.06. No US economic releases occurred. The Canadian dollar fell below 71 cents versus the USD amid widening rate differentials and broad dollar strength.
The Day Ahead
The US economic calendar remains empty for today. No CPI, retail sales, or employment figures are scheduled. Markets will monitor any unscheduled Fed commentary for shifts in forward guidance.
Geopolitical developments and oil price movements may influence sentiment. Treasury auctions and corporate earnings could provide secondary market drivers. Traders will watch USD crosses for continued reaction to yield differentials.
External flows tied to commodity trends and global risk appetite are expected to dominate price action in the absence of fresh domestic data.
Other Economic Notes
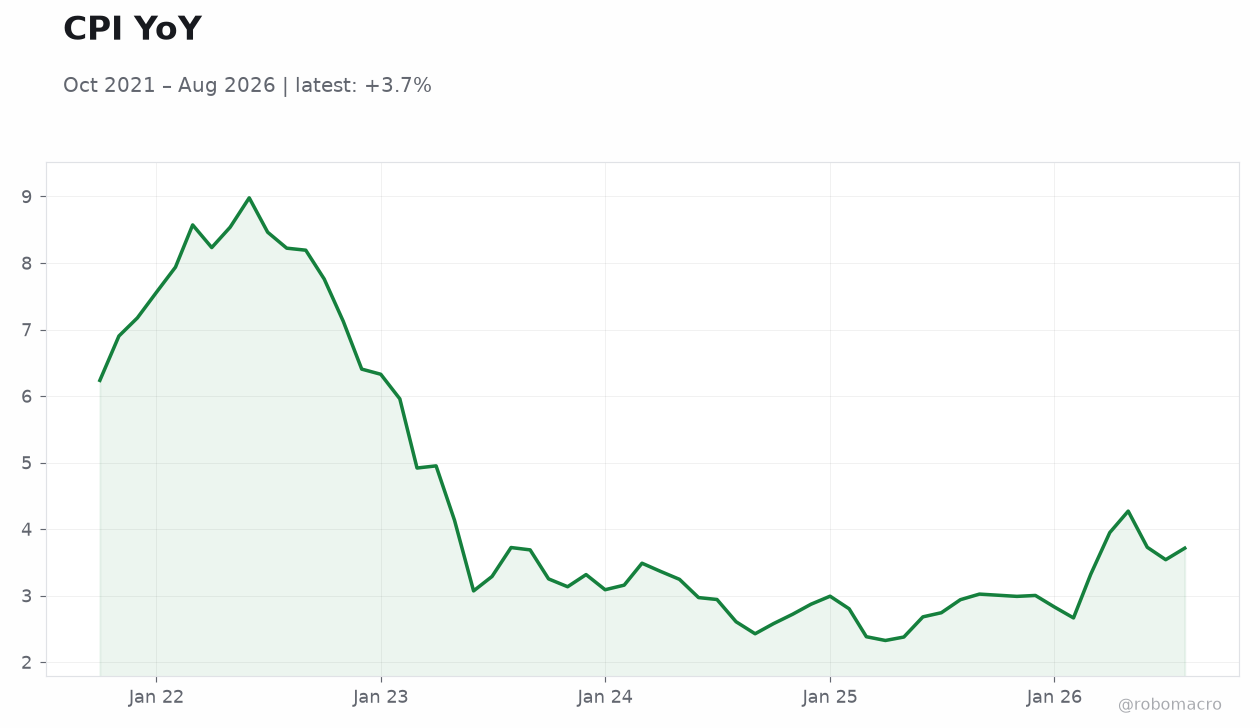
The IMF highlighted that AI-related investments added 0.5 percentage point to US GDP growth last year, underscoring productivity gains amid persistent inflation. Retail sales rose 6.01% year-over-year through August while GDP expanded 2.10% on an annual basis in the first quarter. Unemployment held at 4.10% and CPI stood at 3.40% year-over-year in August.
These figures support views of a resilient economy entering a higher-rate environment. Sticky inflation and faster growth have prompted markets to price firmer policy ahead. The US and China extended their trade truce by two months.