PMI Surge Lifts Yields, Sparks Hawkish Fed Signals
-0.04 Chicago Fed National20,000 ADP Employment Change1.8m API Weekly Crude Oil7.12 MBA 30-Year Mortgage Rate58.40 S&P Global Composite PMI
S&P 5007,704.13-0.02%
US 10Y Treasury5.18%+7 bp
WTI Crude93.06-1.64%
Gold4,342.10+1.03%
Market Snapshot
| Asset | Level | Change |
|---|
| S&P 500 | 7,704.13 | -0.02% |
| Nasdaq 100 | 30,478.86 | +0.03% |
| Dow Jones | 51,349.98 | -0.31% |
| Russell 2000 | 2,835.57 | -0.11% |
| USD/JPY | 157.82 | -0.28% |
| EUR/USD | 1.14 | +0.18% |
| GBP/USD | 1.32 | +0.02% |
| Gold | 4,342.10 | +1.03% |
| WTI Crude | 93.06 | -1.64% |
| Bitcoin | 84,760.88 | +0.45% |
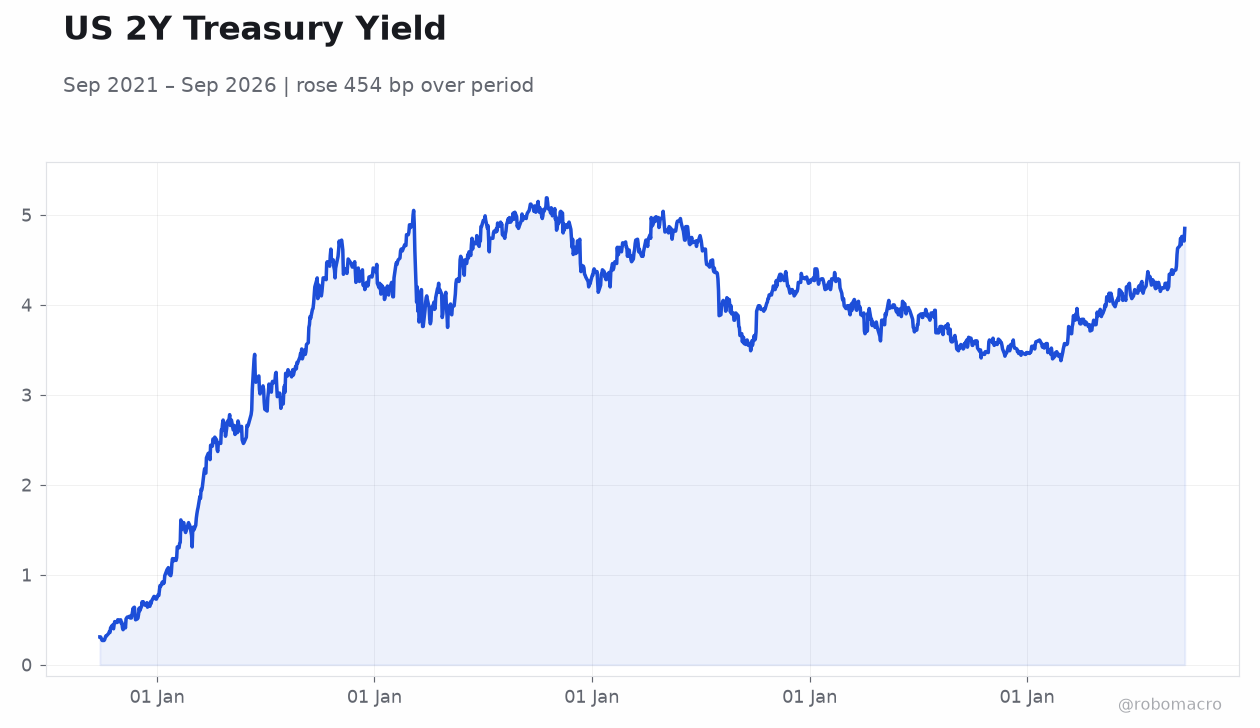
| US 2Y Treasury | 4.85% | +14 bp |
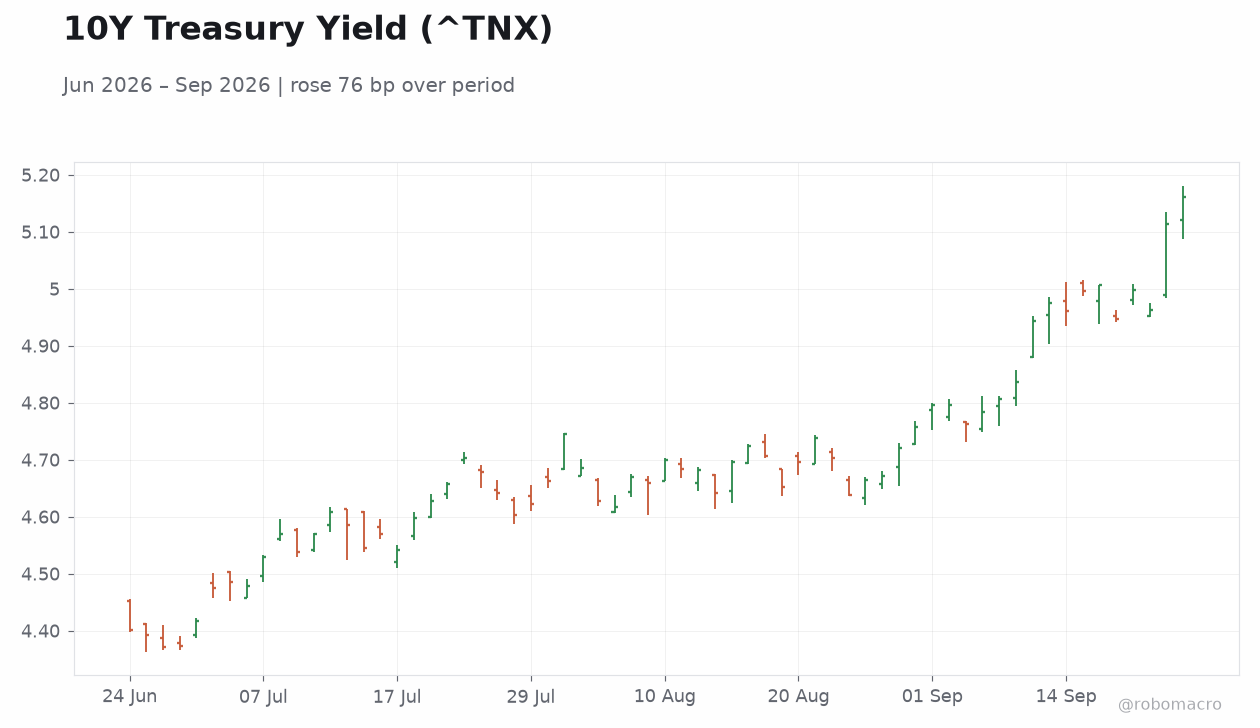
| US 10Y Treasury | 5.18% | +7 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| Fed Goolsbee Speech | - | - | - |
| Chicago Fed National Activity Index | 0.08 | - | -0.04 |
| ADP Employment Change Weekly | 16,250 | - | 20,000 |
| Speech by Fed's Williams | - | - | - |
| Speech by Fed's Jefferson | - | - | - |
| Speech by Fed's Barkin | - | - | - |
| API Weekly Crude Oil Stocks | 7.1m | -500,000 | 1.8m |
| MBA 30-Year Mortgage Rate | 6.97 | - | 7.12 |
| S&P Global Composite PMI Flash | 56 | - | 58.40 |
| S&P Global Manufacturing PMI Flash | 53.90 | 53.60 | 57 |
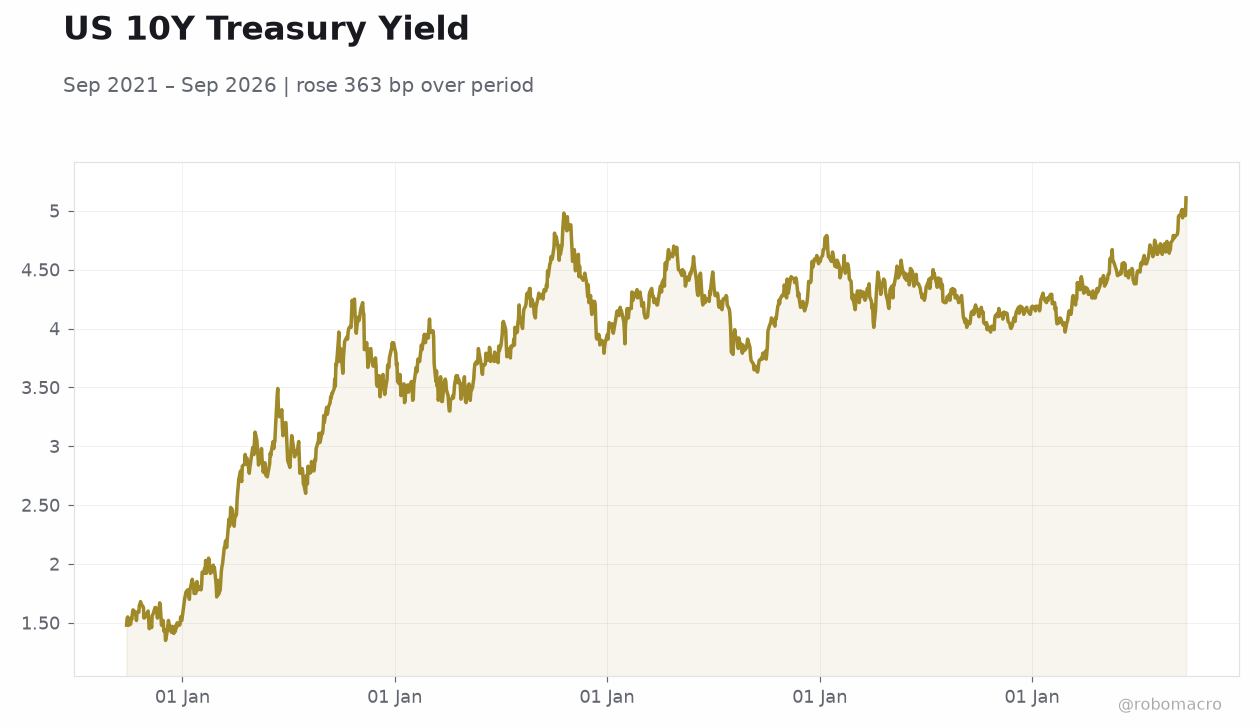 US 10Y Treasury Yield | Type: macro_line | Yield %: 5.11 (2026-09-23) | Range: 1.35–5.11 | Trend(6pt): 1.48,3.84,4.25,4.3,4.96,5.11
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| Durable Goods Orders Month-over-Month | 1.10 | -0.40 | 04:30 |
| Durable Goods Orders Ex Transp Month-over-Month | 0.40 | 0.60 | 04:30 |
| Speech by Fed's Schmid | - | - | 05:20 |
| Michigan Consumer Sentiment Final | 51.70 | 47.60 | 06:00 |
| Fed Hammack Speech | - | - | 10:00 |
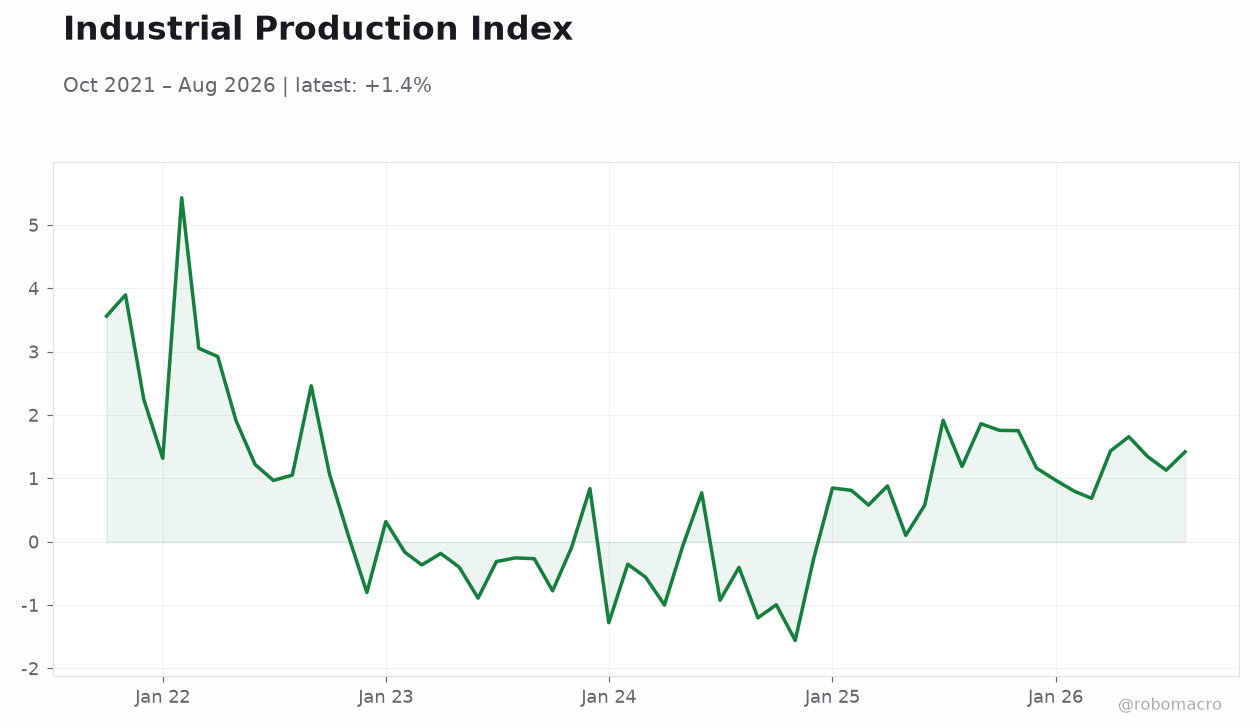
- S&P Global flash PMIs beat expectations across manufacturing and services, signaling stronger growth
- US 2-year Treasury yield jumped 14 bp to 4.85% while 10-year rose 7 bp to 5.18%
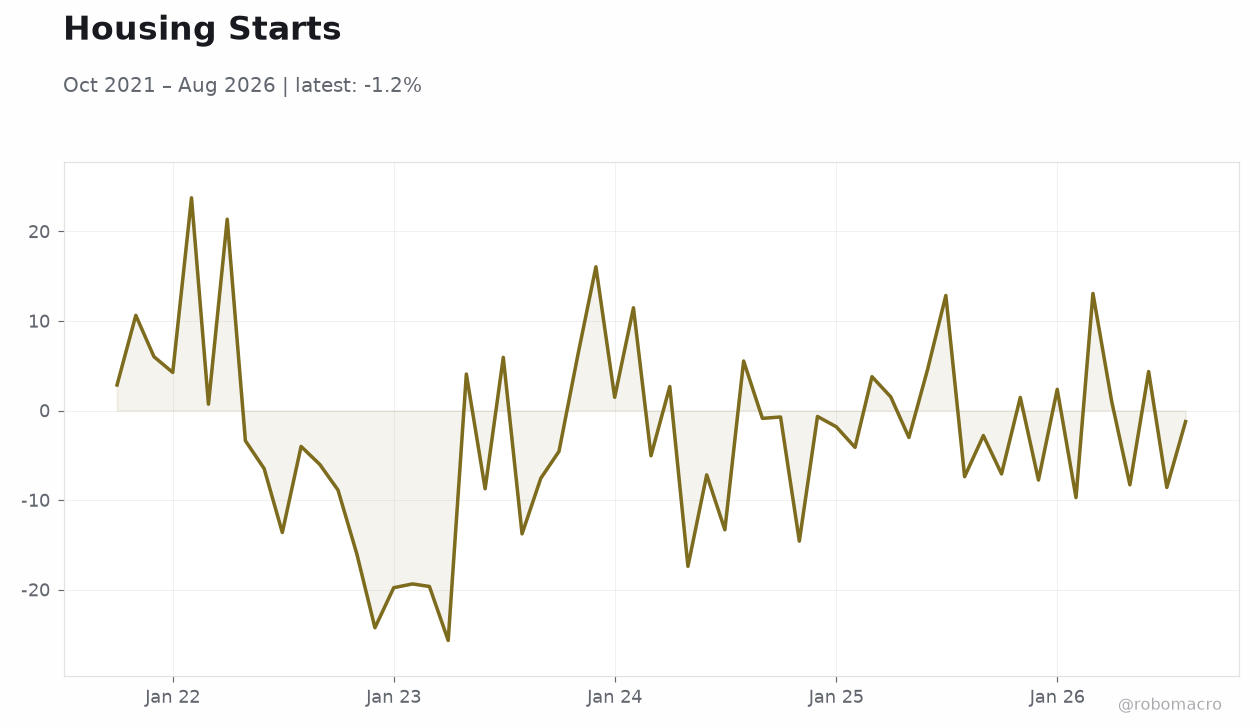
- Mortgage rates climbed to 7.12%, adding pressure on housing affordability
Yesterday's Recap
Equity indices closed mixed with the S&P 500 at 7,704.13, down 0.02 percent, while the Nasdaq 100 edged up 0.03 percent to 30,478.86 and the Dow Jones fell 0.31 percent to 51,349.98. The Russell 2000 slipped 0.11 percent to 2,835.57. Treasury yields rose sharply as the 2-year yield increased 14 basis points to 4.85 percent and the 10-year yield gained 7 basis points to 5.18 percent.
S&P Global flash PMIs exceeded forecasts, with the composite at 58.4, manufacturing at 57.0 versus a 53.6 consensus, and services at 58.7. The Chicago Fed National Activity Index printed negative 0.04 against a prior 0.08. EIA crude inventories rose 2.969 million barrels, far above the expected draw, while gasoline stocks fell 1.686 million barrels.
The MBA 30-year mortgage rate increased to 7.12 percent from 6.97 percent. Multiple Federal Reserve speakers including Goolsbee, Williams, Jefferson, Barkin and Barr addressed audiences without altering policy signals. Gold advanced 1.03 percent to 4,342.10 while WTI crude declined 1.64 percent to 93.06.
Broader context shows resilient activity amid 3.4 percent CPI and 4.1 percent unemployment, with GDP growth at 1.5 percent quarter-over-quarter.
The Day Ahead
Durable Goods Orders are scheduled for release with consensus expectations of a 0.4 percent decline after a 1.1 percent prior gain. The ex-transportation component is projected to rise 0.6 percent. Michigan Consumer Sentiment final reading is expected at 47.6, down from 51.7.
Federal Reserve speakers Schmid and Hammack are set to address audiences. Market participants will monitor any comments on inflation risks and the path for policy rates given the recent hawkish tone from officials. Oil inventory data and any updates on geopolitical developments will also influence sentiment.
The 3.88 percent Fed funds rate remains the anchor, supported by 2.1 percent year-over-year GDP expansion and steady retail sales growth of 6.01 percent.
Page 1
Never miss an issue
Subscribe to US Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.