US Macro Daily(Beta Mode)
Yields Surge as Dallas Fed Index Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,683.69 | -0.77% |
| Nasdaq 100 | 30,276.81 | -1.08% |
| Dow Jones | 51,481.51 | -0.67% |
| Russell 2000 | 2,817.91 | -0.69% |
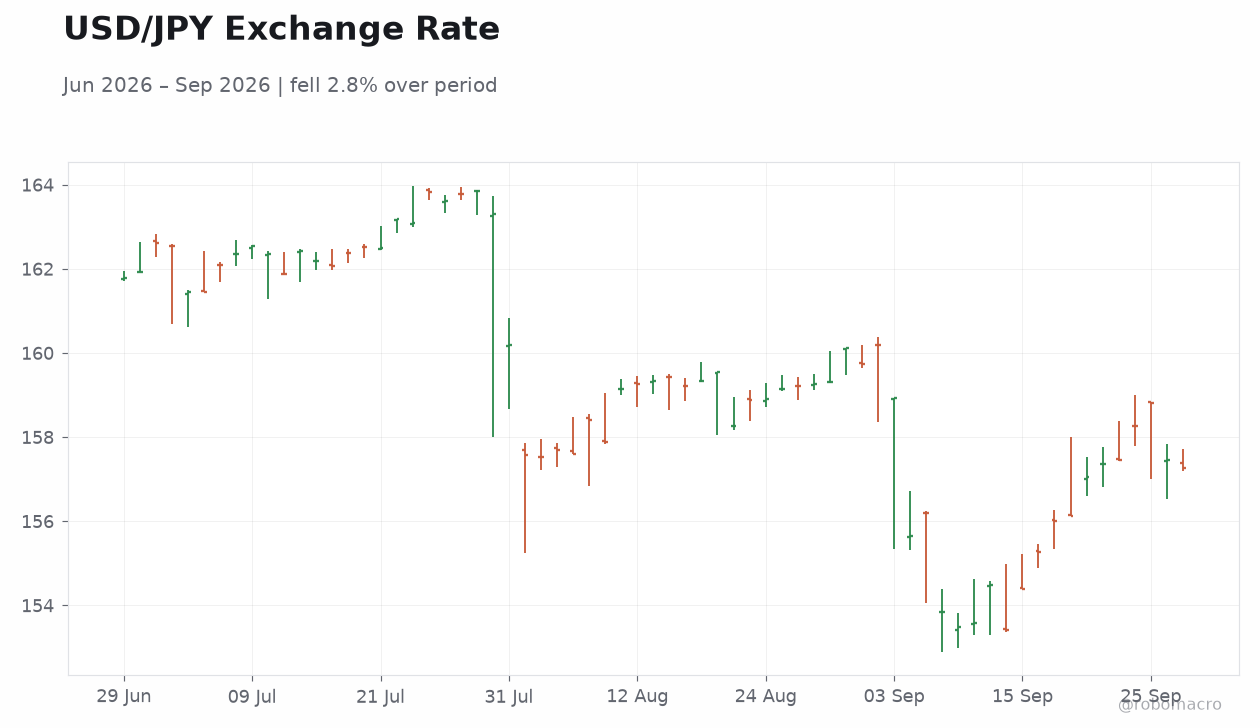
| USD/JPY | 157.23 | -0.15% |
| EUR/USD | 1.14 | -0.23% |
| GBP/USD | 1.32 | +0.06% |
| Gold | 4,183.50 | +0.36% |
| WTI Crude | 92.07 | -0.57% |
| Bitcoin | 84,010.94 | +0.61% |
| US 2Y Treasury | 4.85% | +14 bp |
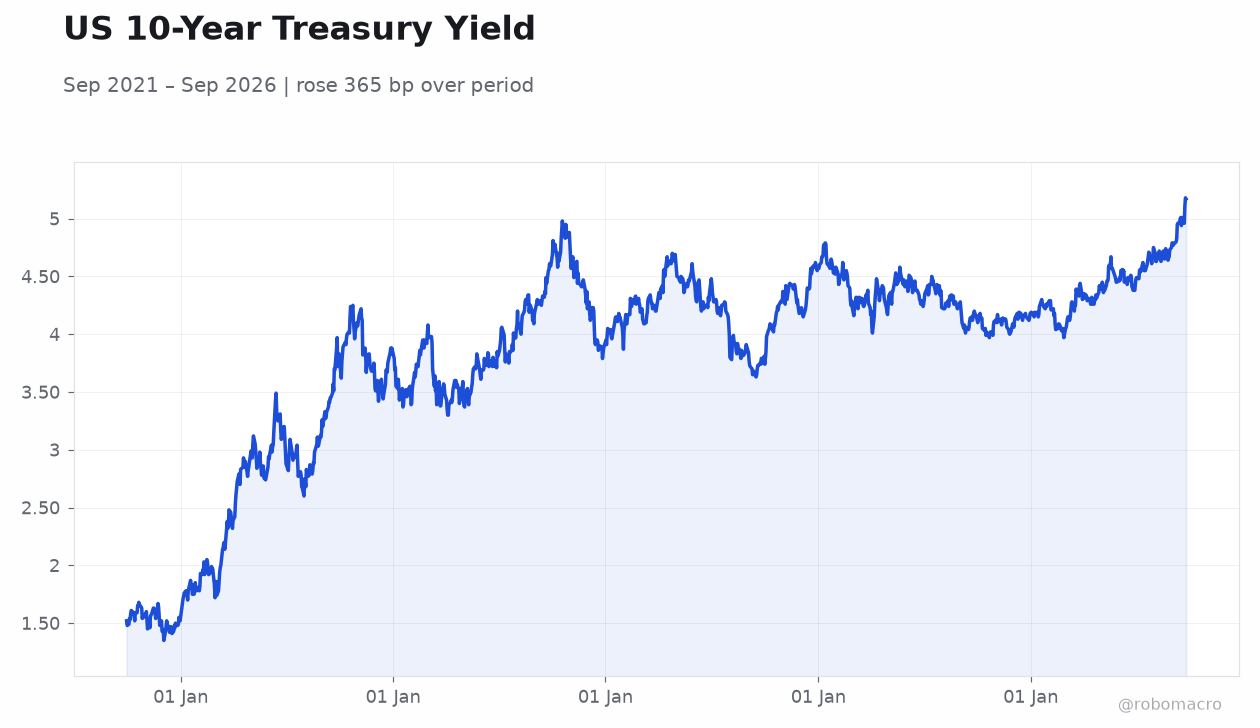
| US 10Y Treasury | 5.24% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | - |
| Un General Assembly | - | - | - |
| Dallas Fed Manufacturing Index | 11.60 | - | 9.80 |
| Speech by Fed's Barkin | - | - | - |
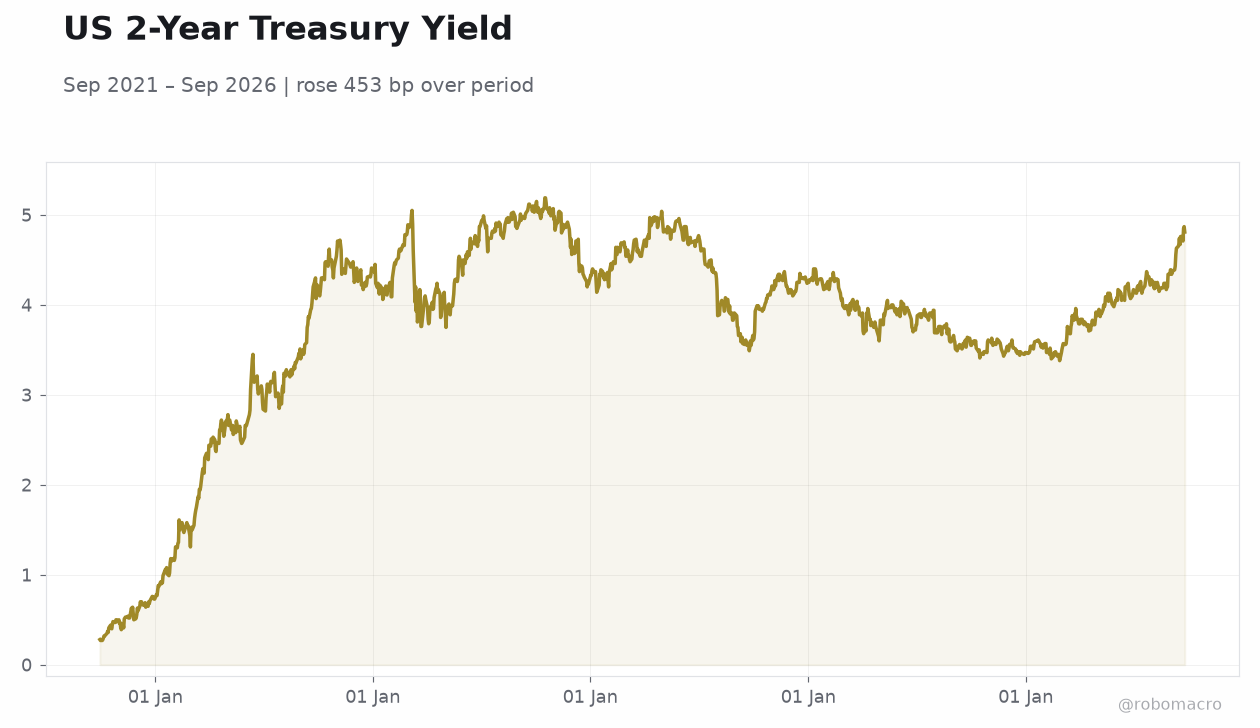 US 2-Year Treasury Yield | Type: macro_line | Yield (%): 4.81 (2026-09-25) | Range: 0.27–5.19 | Trend(6pt): 0.28,4.41,4.59,3.73,4.87,4.81
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P/Case-Shiller Home Price Year-over-Year | 2.10 | 2.20 | 05:00 |
| JOLTs Job Openings | 7.3m | 7.2m | 06:00 |
| Cb Consumer Confidence | 89.40 | - | 06:00 |
| Fed Goolsbee Speech | - | - | 09:00 |
| Speech by Fed's Musalem | - | - | 09:30 |
| Speech by Fed's Williams | - | - | 10:00 |
| API Weekly Crude Oil Stocks | 1.8m | -1.9m | 12:30 |
- US 2-year yield jumps 14 bp to 4.85% while equities fall across benchmarks
- Dallas Fed Manufacturing Index slips to 9.8 from 11.6 in September
- Markets focus on JOLTs openings and three Fed speeches for policy signals
Yesterday's Recap
Equities declined across major US indices on September 28. The S&P 500 fell 0.77% to 7,683.69, the Nasdaq 100 dropped 1.08% to 30,276.81, the Dow Jones eased 0.67% to 51,481.51, and the Russell 2000 declined 0.69% to 2,817.91. Treasury yields rose sharply, with the 2-year yield climbing 14 bp to 4.85% and the 10-year yield adding 7 bp to 5.24%.
WTI Crude fell 0.57% to $92.07 while gold advanced 0.36% to $4,183.50. The Dallas Fed Manufacturing Index printed 9.8, below the prior reading of 11.6. Medium-impact speeches from Fed officials Bowman and Barkin occurred alongside the UN General Assembly, with no immediate market-moving comments released.
Currency pairs showed limited movement, as USD/JPY eased 0.15% to 157.23 and EUR/USD declined 0.23% to 1.14. The Fed funds rate sits at 3.88%.
The Day Ahead
S&P/Case-Shiller Home Price YoY is due at 5:00 ET with consensus at 2.2% versus the prior 2.1%. JOLTs Job Openings at 6:00 ET carries high impact, with consensus at 7.23 million against the previous 7.271 million. CB Consumer Confidence follows at the same time.
High-impact Fed speeches from Goolsbee at 9:00 ET, Musalem at 9:30 ET, and Williams at 10:00 ET will draw attention for any fresh policy signals. API Weekly Crude Oil Stocks close the session at 12:30 ET. Markets will parse the JOLTs print and Goolsbee remarks for clues on labor demand and rate trajectory amid the recent rise in real yields.
Other Economic Notes
US GDP growth registered 1.50% QoQ SAAR in the latest reading, with the year-over-year pace at 2.10%. Unemployment stands at 4.10% while retail sales expanded 6.01% YoY. CPI inflation holds at 3.40% YoY, keeping pressure on real yields that have climbed this week.
These figures underscore a moderate expansion with cooling labor market momentum. Rising Treasury yields reflect investor reassessment of the policy path amid persistent price pressures. The committee maintains a data-dependent stance focused on labor and inflation outcomes.