US Macro Daily(Beta Mode)
Home Prices Beat, JOLTs Miss as Yields Climb
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,670.84 | -0.17% |
| Nasdaq 100 | 30,339.33 | +0.21% |
| Dow Jones | 51,349.92 | -0.26% |
| Russell 2000 | 2,807.92 | -0.35% |
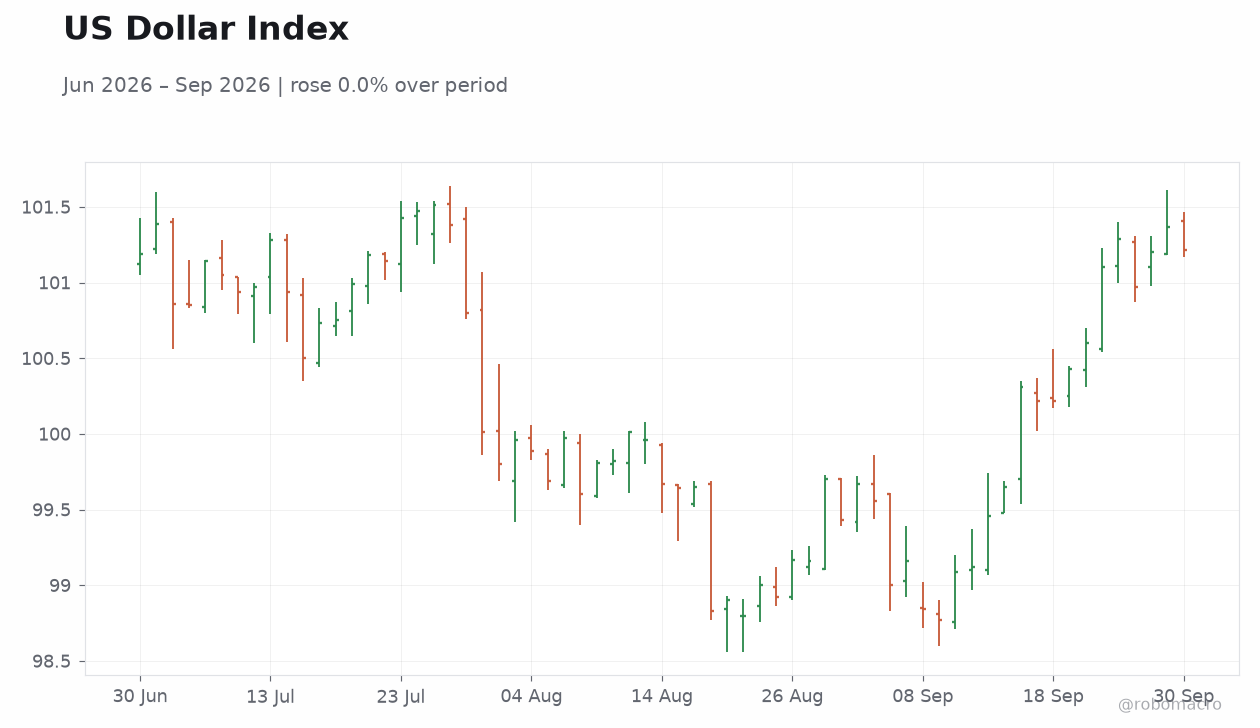
| USD/JPY | 157.06 | -0.19% |
| EUR/USD | 1.14 | -0.09% |
| GBP/USD | 1.33 | +0.27% |
| Gold | 4,214.70 | +0.84% |
| WTI Crude | 90.33 | +1.06% |
| Bitcoin | 83,805.58 | +0.22% |
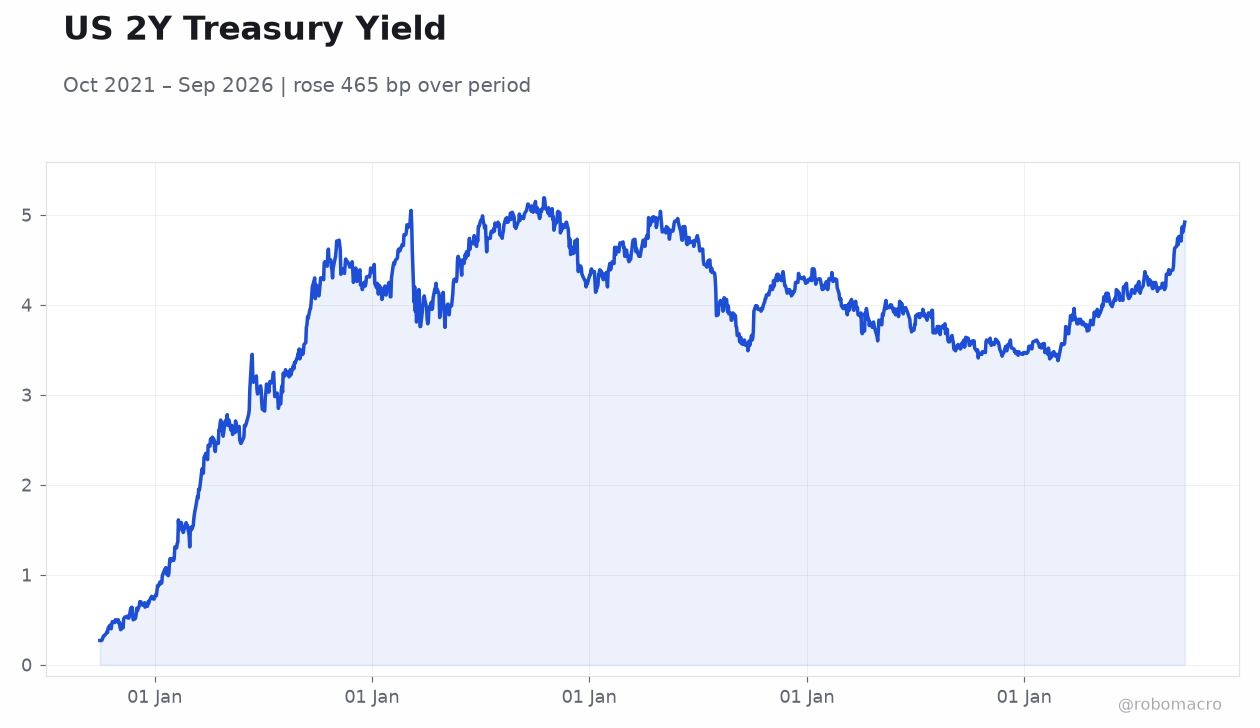
| US 2Y Treasury | 4.85% | +14 bp |
| US 10Y Treasury | 5.26% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | - |
| Un General Assembly | - | - | "" |
| Dallas Fed Manufacturing Index | 11.60 | - | 9.80 |
| Speech by Fed's Barkin | - | - | - |
| S&P/Case-Shiller Home Price Year-over-Year | 2.20 | 2.20 | 2.50 |
| JOLTs Job Openings | 7.3m | 7.2m | 7.1m |
| Cb Consumer Confidence | 88.60 | - | 81.90 |
| Fed Goolsbee Speech | - | - | - |
| Speech by Fed's Musalem | - | - | - |
| Speech by Fed's Williams | - | - | - |
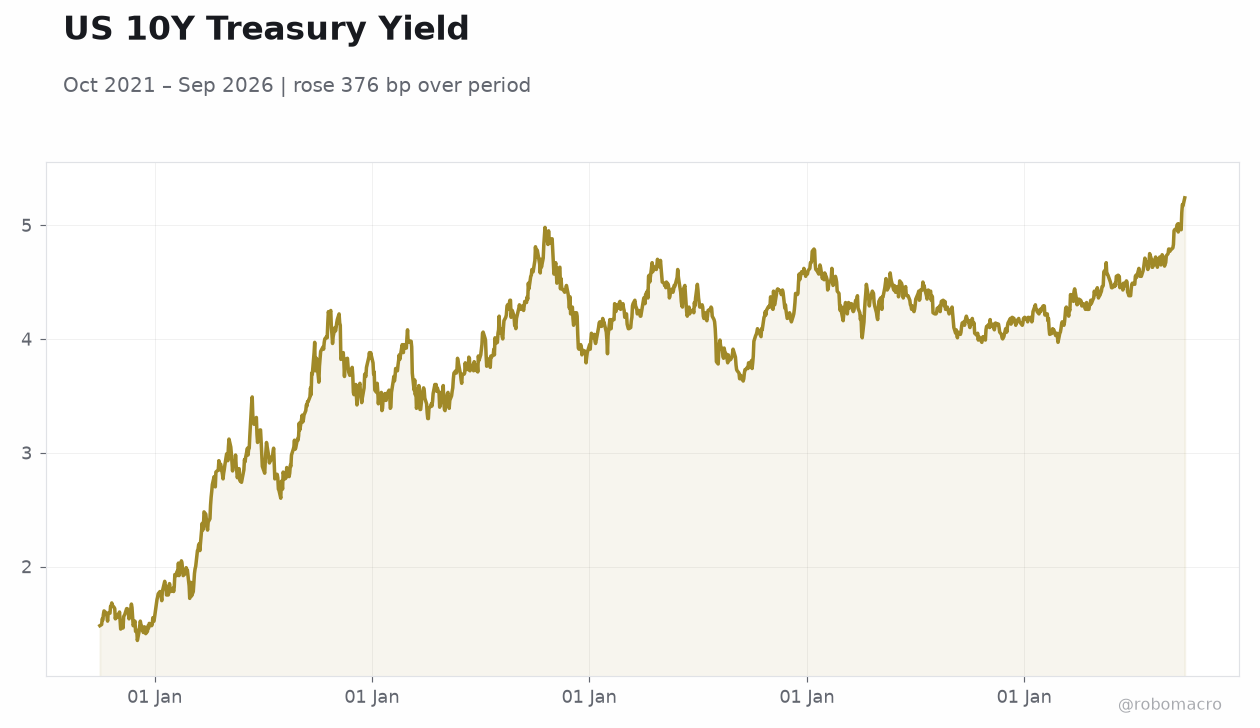 US 10Y Treasury Yield | Type: macro_line | Yield (%): 5.24 (2026-09-28) | Range: 1.35–5.24 | Trend(6pt): 1.48,3.79,4.33,4.24,5.17,5.24
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ADP Employment Change | 38,000 | 70,000 | 04:15 |
| Core PCE Price Index Month-over-Month | 0.20 | 0.30 | 04:30 |
| GDP Growth Quarter-over-Quarter Final Estimate | 2.10 | 1.50 | 04:30 |
| Personal Income Month-over-Month | 0.40 | 0.40 | 04:30 |
| Personal Spending Month-over-Month | 0.20 | 0.80 | 04:30 |
| GDP Price Index Quarter-over-Quarter Final | 3.60 | - | 04:30 |
| Goods Trade Balance Adv | -118,800m | -115,000m | 04:30 |
| PCE Price Index Month-over-Month | 0.20 | 0.40 | 04:30 |
| PCE Price Index Year-over-Year | 3.70 | 3.70 | 04:30 |
| Retail Inventories Ex Autos Month-over-Month Adv | 0.80 | - | 04:30 |
- S&P/Case-Shiller home prices rose 2.5% YoY, exceeding the 2.2% consensus.
- JOLTs job openings fell to 7.079 million versus 7.23 million expected.
- US 2-year Treasury yield jumped 14 bp to 4.85% while the 10-year rose 2 bp to 5.26%.
Yesterday's Recap
S&P/Case-Shiller Home Price Index climbed to 2.5% year-over-year, surpassing the 2.2% consensus and prior reading. JOLTs job openings declined to 7.079 million, missing the 7.23 million forecast and falling from 7.335 million. Conference Board Consumer Confidence dropped sharply to 81.9 from 88.6.
API crude oil stocks rose 1.019 million barrels against expectations of a 1.9 million draw. Equities closed mixed with the S&P 500 down 0.17% at 7,670.84 while the Nasdaq 100 gained 0.21%. The 2-year Treasury yield surged 14 bp to 4.85% and the 10-year yield added 2 bp to 5.26%.
Gold advanced 0.84% to $4,214.70 and WTI crude rose 1.06% to $90.33. Dallas Fed Manufacturing Index printed 9.8, below the prior 11.6. Multiple Fed speakers addressed audiences without shifting immediate pricing.
The Day Ahead
ADP Employment Change is due at 4:15 ET with a 70,000 consensus. Core PCE Price Index month-over-month is expected at 0.3% at 4:30 ET. Final GDP growth quarter-over-quarter is forecast at 1.5% for the same time.
Personal Income and Spending reports follow alongside the goods trade balance. Markets will focus on the inflation and growth prints for rate-path signals. Multiple Fed speakers including Goolsbee and Williams are also scheduled.
MBA 30-Year Mortgage Rate data will close the session.
Other Economic Notes
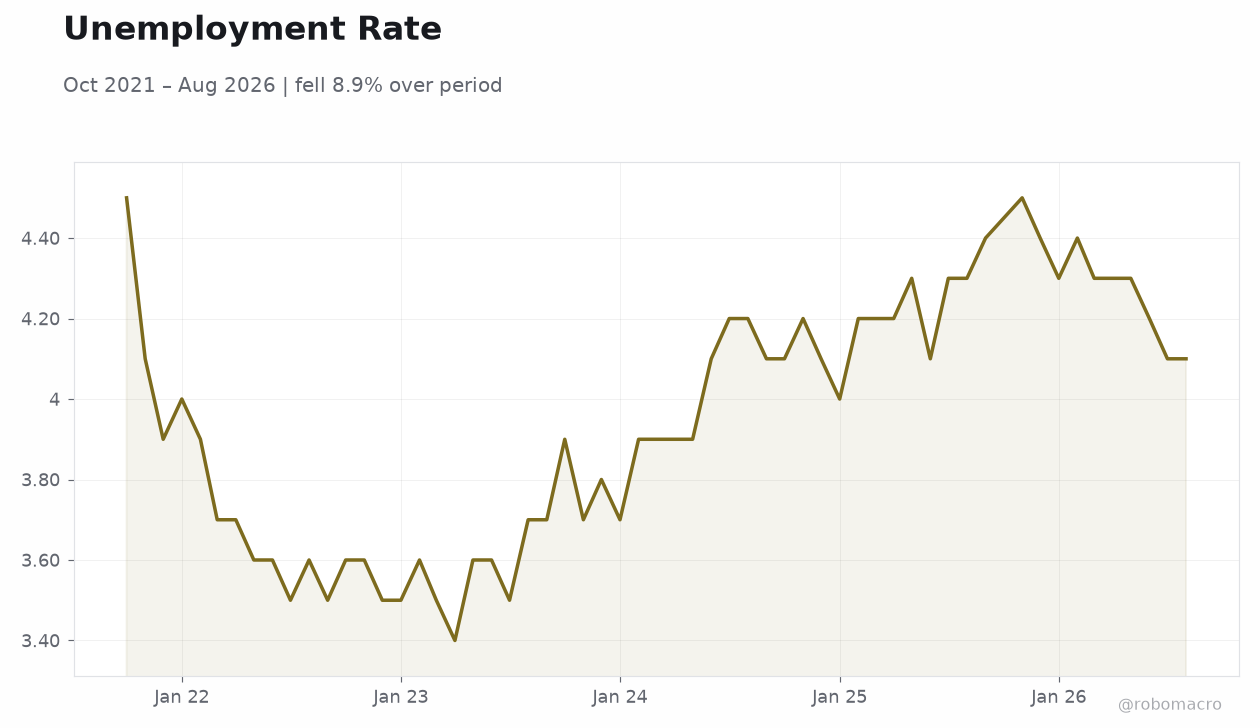
US GDP growth stands at 1.5% quarter-over-quarter annualized and 2.1% year-over-year. Unemployment holds at 4.1% while retail sales rose 5.36% year-over-year. The Fed funds rate sits at 3.88%.
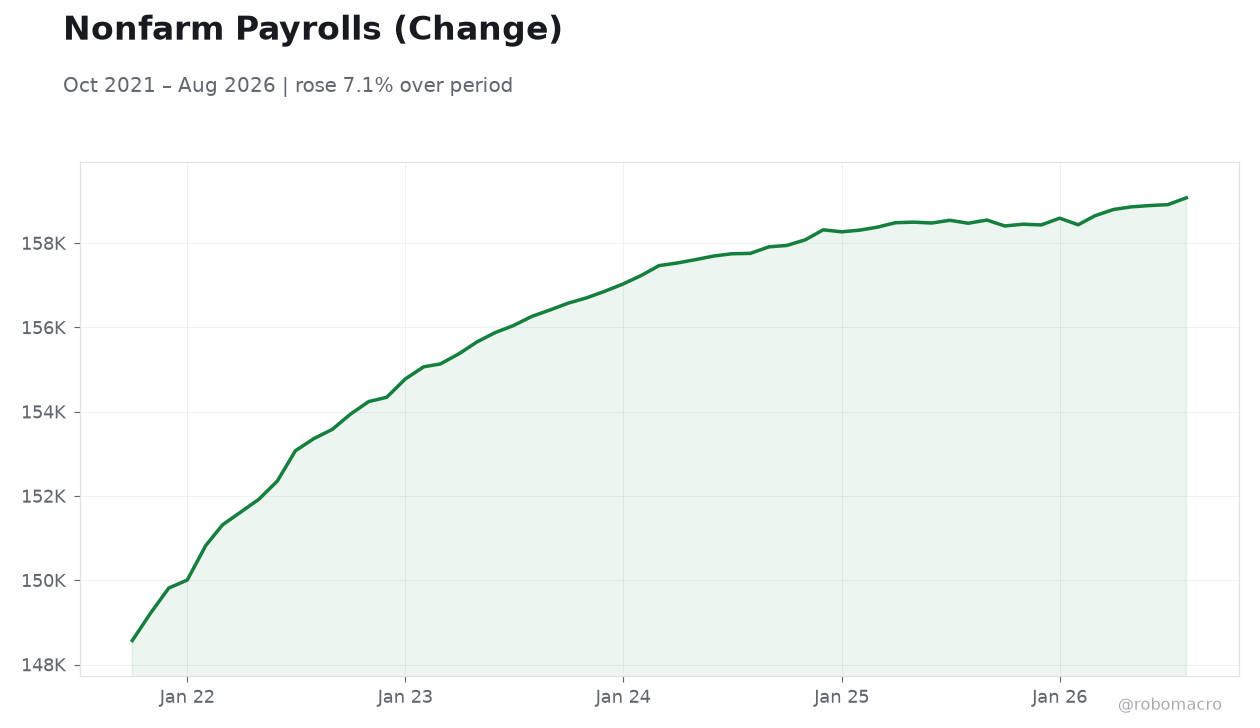
Broader themes include softening labor demand and weaker household sentiment amid still-elevated Treasury yields. CPI inflation registered 3.4% year-over-year in the latest reading. These figures underscore a resilient expansion that continues to support higher-for-longer policy expectations even as labor-market indicators cool.