US Macro Daily(Beta Mode)
Core PCE Softens as GDP Beats Estimates
Market Snapshot
| Asset | Level | Change |
|---|---|---|
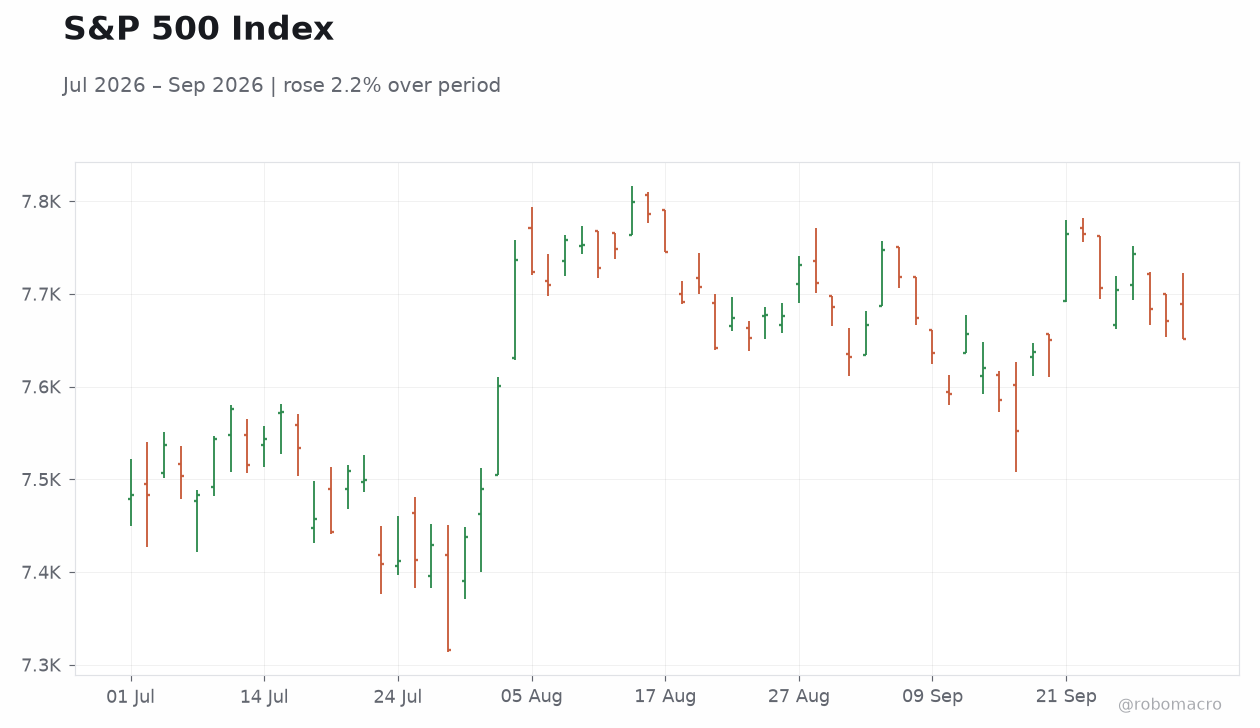
| S&P 500 | 7,651.54 | -0.25% |
| Nasdaq 100 | 30,408.50 | +0.23% |
| Dow Jones | 50,906.05 | -0.86% |
| Russell 2000 | 2,796.86 | -0.39% |
| USD/JPY | 158.10 | +0.44% |
| EUR/USD | 1.13 | -0.40% |
| GBP/USD | 1.32 | -0.06% |
| Gold | 4,204.90 | +0.43% |
| WTI Crude | 91.35 | +1.03% |
| Bitcoin | 83,889.90 | +0.40% |
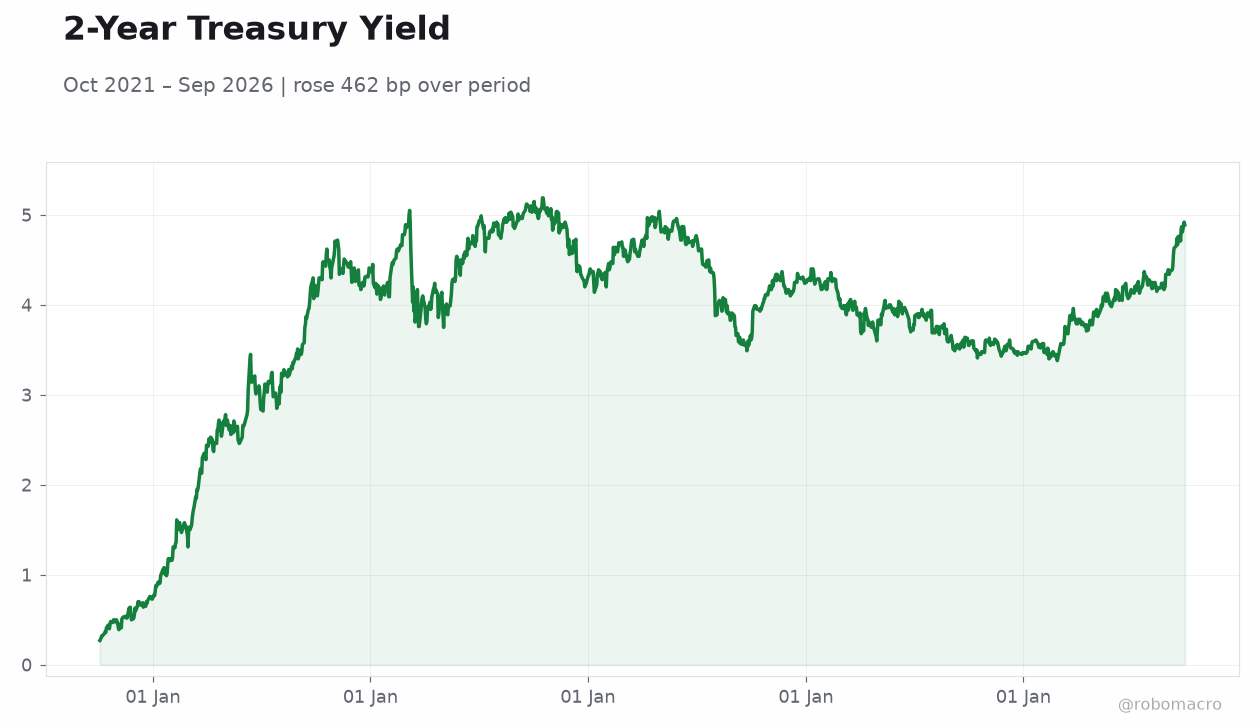
| US 2Y Treasury | 4.85% | +14 bp |
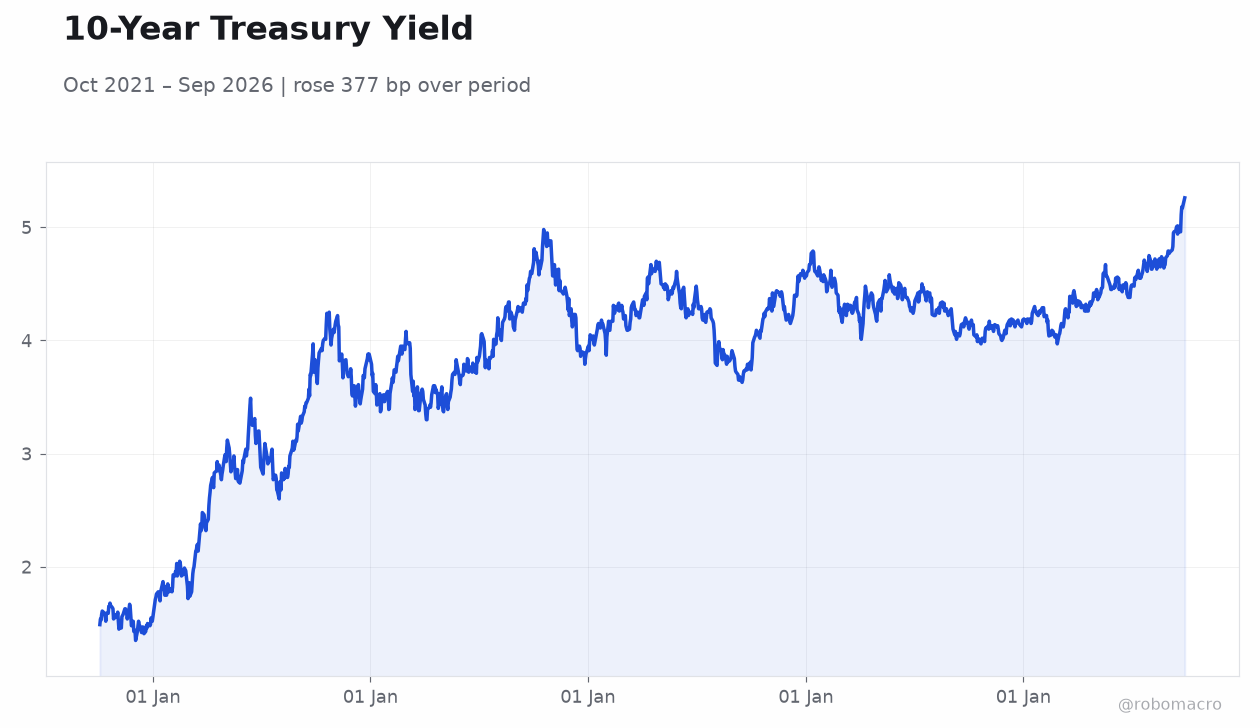
| US 10Y Treasury | 5.29% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | - |
| Un General Assembly | - | - | "" |
| Dallas Fed Manufacturing Index | 11.60 | - | 9.80 |
| Speech by Fed's Barkin | - | - | - |
| S&P/Case-Shiller Home Price Year-over-Year | 2.20 | 2.20 | 2.50 |
| JOLTs Job Openings | 7.3m | 7.2m | 7.1m |
| Cb Consumer Confidence | 88.60 | - | 81.90 |
| Fed Goolsbee Speech | - | - | - |
| Speech by Fed's Musalem | - | - | - |
| Speech by Fed's Williams | - | - | - |
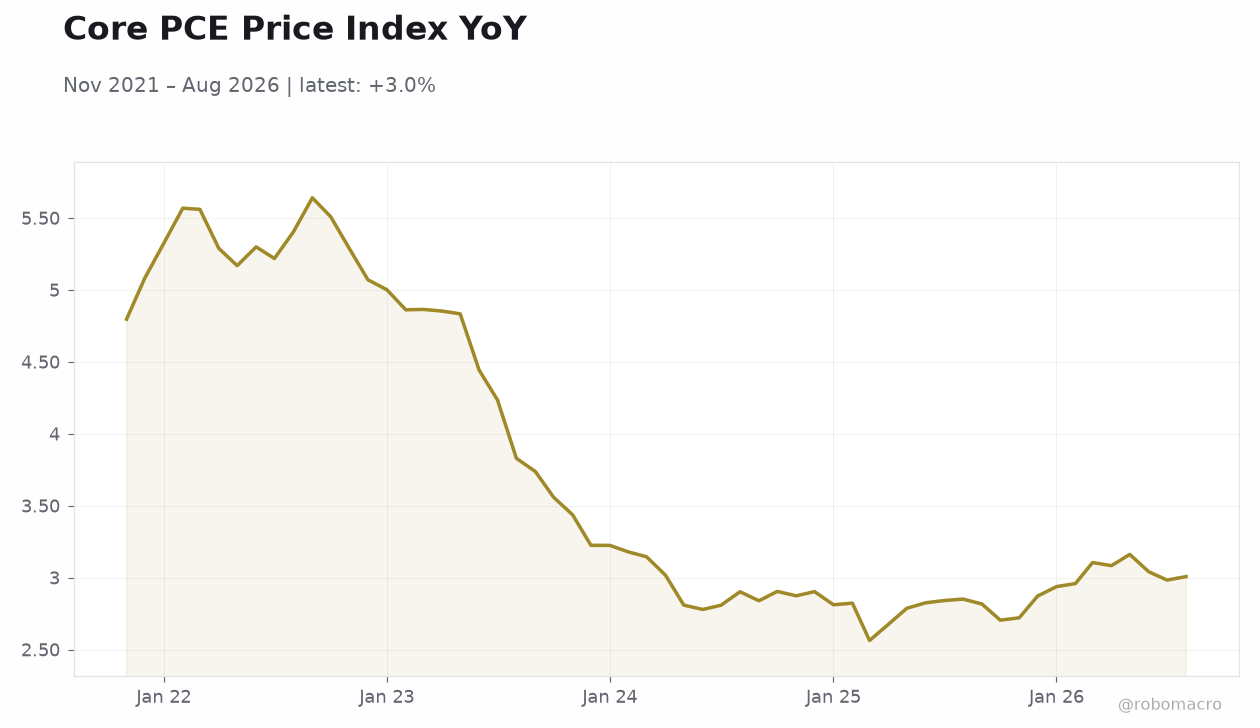 Core PCE Price Index YoY | Type: macro_line | YoY %: 3.008 (2026-08-01) | Range: 2.564–5.64 | Trend(6pt): 4.797,5.002,3.146,2.787,2.983,3.008
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Weekly Jobless Claims | 197,000 | 200,000 | 04:30 |
| Speech by Fed's Barkin | - | - | 05:05 |
| Speech by Fed's Collins | - | - | 05:05 |
| Speech by Fed's Schmid | - | - | 05:05 |
| ISM Manufacturing PMI | 54.60 | 55 | 06:00 |
| ISM Manufacturing Employment | 51.20 | - | 06:00 |
| Speech by Fed's Williams | - | - | 11:30 |
| Speech by Fed's Logan | - | - | 14:45 |
- Core PCE rose 0.2% MoM, below 0.3% consensus, easing near-term inflation pressure.
- Final Q3 GDP printed 2.2% QoQ, above 1.5% forecast, while ADP employment beat at +90k.
- 2-year Treasury yield jumped 14 bp to 4.85% as markets adjusted rate expectations.
Yesterday's Recap
Core PCE Price Index rose 0.2% MoM against a 0.3% consensus and 0.1% prior, delivering a softer inflation reading that reduced immediate overheating concerns. Final Q3 GDP growth was revised up to 2.2% QoQ from the 1.5% consensus, confirming solid underlying momentum despite the prior 2.5% pace. ADP employment surprised to the upside at +90k versus +70k expected, while JOLTs job openings fell to 7.079 million below the 7.23 million forecast.
Case-Shiller home prices accelerated to 2.5% YoY and consumer confidence dropped sharply to 81.9. The 30-year mortgage rate climbed to 7.3%. Equities finished mixed with the S&P 500 down 0.25% at 7,651.54 and the Dow Jones off 0.86% at 50,906.05, while the Nasdaq 100 gained 0.23%.
The 2-year Treasury yield surged 14 bp to 4.85% and the 10-year yield rose 3 bp to 5.29%, lifting USD/JPY to 158.10. Dallas Fed Manufacturing Index printed 9.8, below the prior 11.6, while API crude stocks rose 1.019 million barrels.
The Day Ahead
Weekly jobless claims headline the calendar with consensus at 200k after the prior 197k print. Markets will also monitor any follow-through from yesterday’s softer Core PCE and upward GDP revision for clues on labor-market resilience. Fed speakers Barkin, Collins and Schmid are scheduled, offering fresh views on the policy path after yesterday’s data.
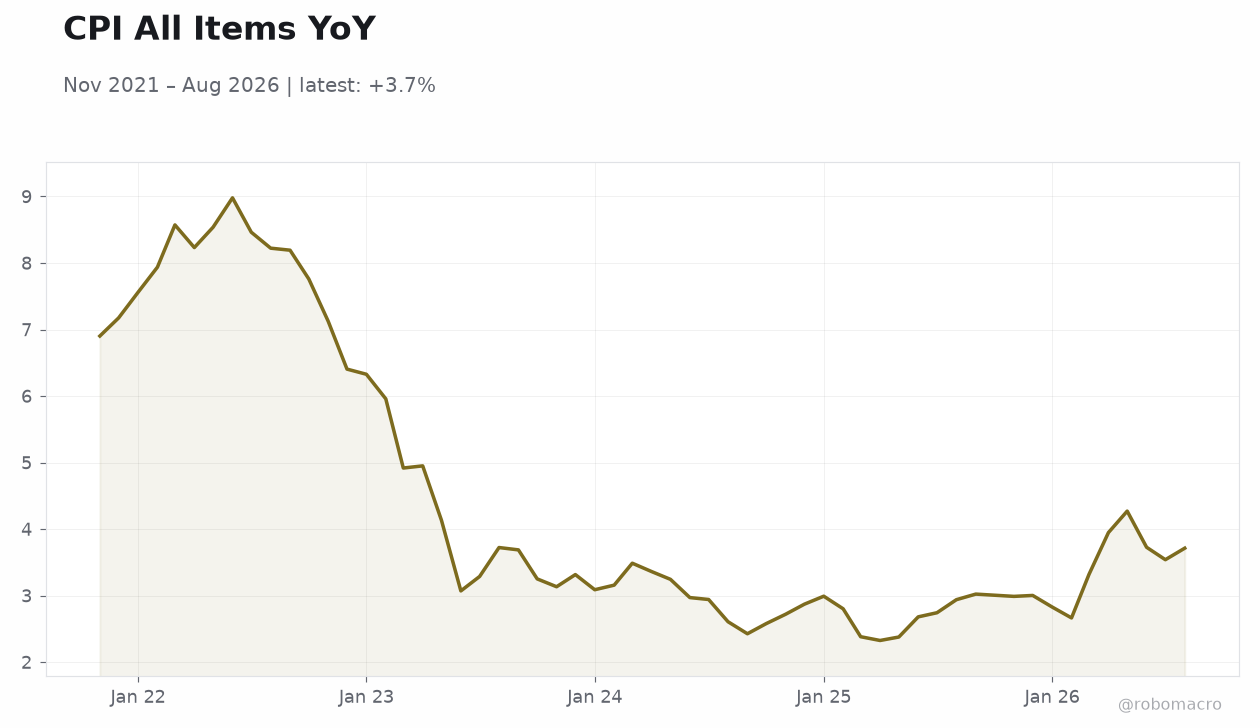
Energy inventory data and mortgage-rate updates round out the session. The 3.40% August CPI and 4.10% unemployment rate remain reference points as traders assess whether the 2.2% GDP pace sustains or requires further adjustment in rate expectations.
Other Economic Notes
The 2.5% YoY rise in Case-Shiller prices alongside the jump in mortgage rates to 7.3% points to persistent housing-market tightness despite higher borrowing costs. Consumer confidence’s drop to 81.9 signals households are growing more cautious amid mixed labor and price signals. Broader retail-sales momentum remains supported by the 5.36% YoY pace recorded in August, helping sustain the 2.2% GDP print.
↓ p.2