US Macro Daily(Beta Mode)
Soft PCE, Weak JOLTs Offset ADP Beat
Market Snapshot
| Asset | Level | Change |
|---|---|---|
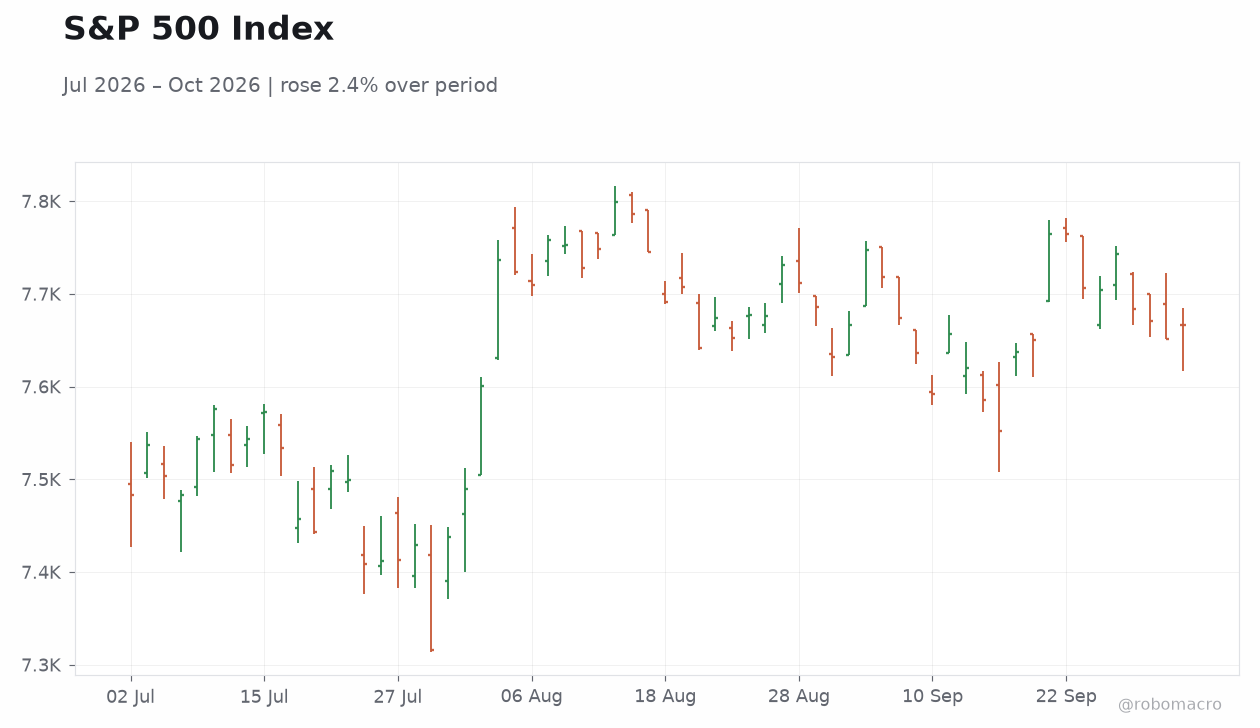
| S&P 500 | 7,666.45 | +0.19% |
| Nasdaq 100 | 30,501.56 | +0.31% |
| Dow Jones | 50,926.56 | +0.04% |
| Russell 2000 | 2,806.63 | +0.35% |
| USD/JPY | 157.80 | +0.15% |
| EUR/USD | 1.12 | -0.76% |
| GBP/USD | 1.32 | -0.41% |
| Gold | 4,216.50 | +0.34% |
| WTI Crude | 89.44 | -3.69% |
| Bitcoin | 86,419.75 | +1.85% |
| US 2Y Treasury | 4.85% | +14 bp |
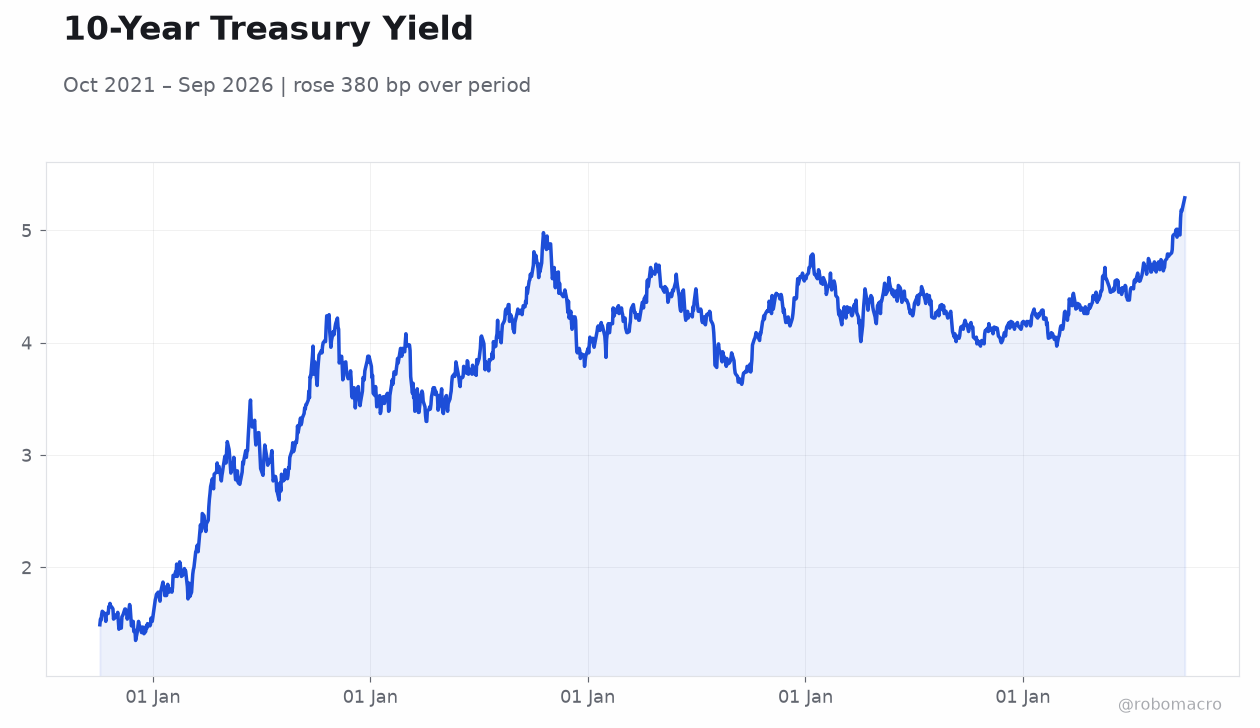
| US 10Y Treasury | 5.29% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | - |
| Un General Assembly | - | - | "" |
| Dallas Fed Manufacturing Index | 11.60 | - | 9.80 |
| Speech by Fed's Barkin | - | - | - |
| S&P/Case-Shiller Home Price Year-over-Year | 2.20 | 2.20 | 2.50 |
| JOLTs Job Openings | 7.3m | 7.2m | 7.1m |
| Cb Consumer Confidence | 88.60 | - | 81.90 |
| Fed Goolsbee Speech | - | - | - |
| Speech by Fed's Musalem | - | - | - |
| Speech by Fed's Williams | - | - | - |
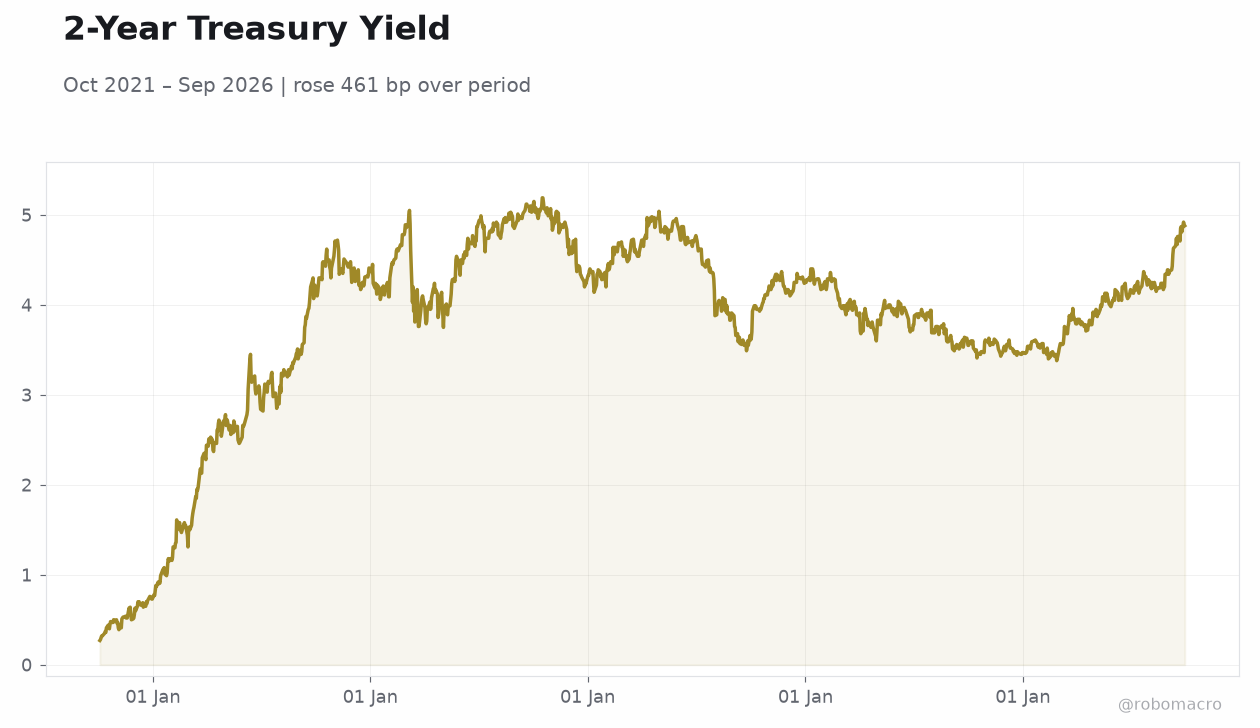 2-Year Treasury Yield | Type: macro_line | Yield %: 4.88 (2026-09-30) | Range: 0.27–5.19 | Trend(6pt): 0.27,4.36,4.7,3.78,4.92,4.88
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Headline Unemployment Rate | 4.10 | 4.10 | 04:30 |
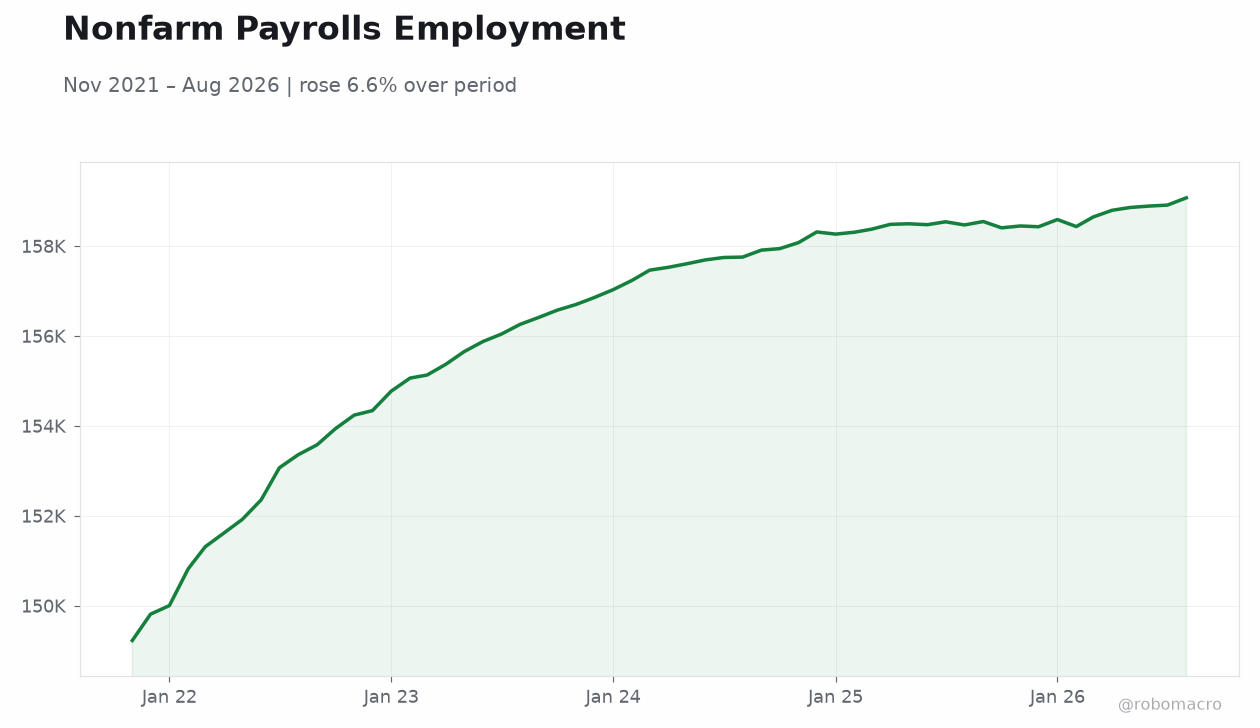
| Payroll Jobs Growth | 162,000 | 90,000 | 04:30 |
| Annual Wage Growth | 3.10 | 3.20 | 04:30 |
| Labor Force Participation | 61.60 | - | 04:30 |
| Monthly Wage Growth | 0.30 | 0.30 | 04:30 |
| Factory Orders Month-over-Month | 0.90 | 0.10 | 06:00 |
| Speech by Fed's Logan | - | - | 06:00 |
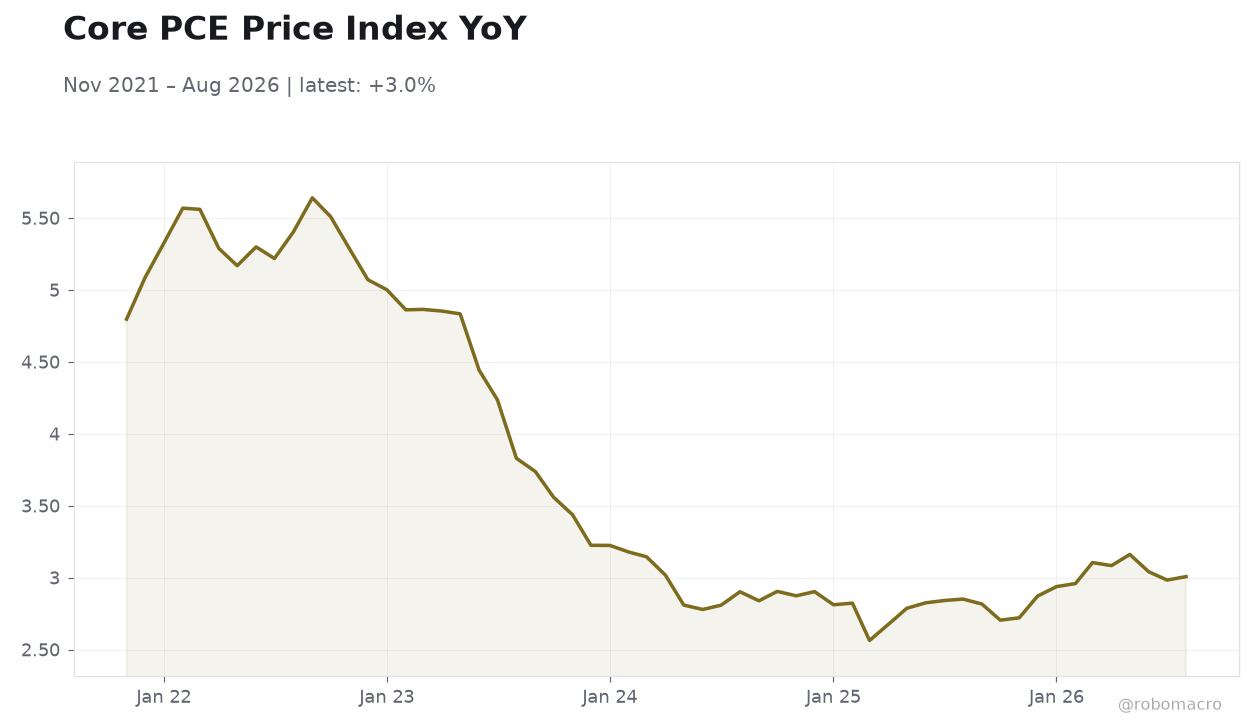
- Core PCE rose 0.2% MoM while JOLTs job openings fell to 7.079 million, signaling labor-market cooling.
- ADP employment rose 90k and Q2 GDP finalized at 2.2%, yet equities advanced modestly as 2-year yields jumped 14 bp.
- Markets price the October 2 jobs report as the key driver for near-term Fed policy expectations.
Yesterday's Recap
US data releases on September 29-30 delivered mixed signals. S&P/Case-Shiller home prices rose 2.5% YoY, above the 2.2% consensus. JOLTs job openings dropped to 7.079 million versus 7.23 million expected, while consumer confidence fell to 81.9.
ADP employment change beat forecasts at +90k, and core PCE printed 0.2% MoM against a 0.3% consensus. Final Q2 GDP came in at 2.2%, above the 1.5% estimate. The Dallas Fed manufacturing index eased to 9.8.
Equities posted small gains with the S&P 500 at 7,666.45 (+0.19%) and Nasdaq 100 at 30,501.56 (+0.31%). The 2-year Treasury yield rose 14 bp to 4.85% while the 10-year yield added 3 bp to 5.29%. WTI crude fell 3.69% to 89.44.
Fed speakers Bowman, Barkin, Goolsbee, Musalem and Williams offered no major policy shifts. API crude stocks rose 1.019 million barrels and the MBA 30-year mortgage rate increased to 7.3%.
The Day Ahead
The September employment report at 8:30 ET will dominate trading. Consensus calls for a 4.1% unemployment rate. Factory orders follow at 10:00 ET.
Markets will scrutinize wage and participation figures for clues on inflation persistence. Treasury yields and equity futures are expected to react sharply to any deviation from consensus. The report will shape expectations for the next FOMC decision.
Other Economic Notes
Rising Treasury yields reflect persistent inflation concerns despite softer core PCE. The 10-year yield at 5.29% sits near multi-decade highs, increasing borrowing costs across mortgages and corporate debt. Stronger final GDP and ADP prints underscore underlying resilience even as labor demand cools.
Mortgage rates climbed to 7.3%, further pressuring housing affordability. These dynamics keep the Fed focused on data-dependent policy adjustments.