US Macro Daily(Beta Mode)
Equities Rally on Soft Jobs Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,722.72 | +0.73% |
| Nasdaq 100 | 30,807.93 | +1.00% |
| Dow Jones | 51,176.96 | +0.49% |
| Russell 2000 | 2,832.90 | +0.94% |
| USD/JPY | 157.92 | -0.01% |
| EUR/USD | 1.12 | -0.40% |
| GBP/USD | 1.32 | +0.18% |
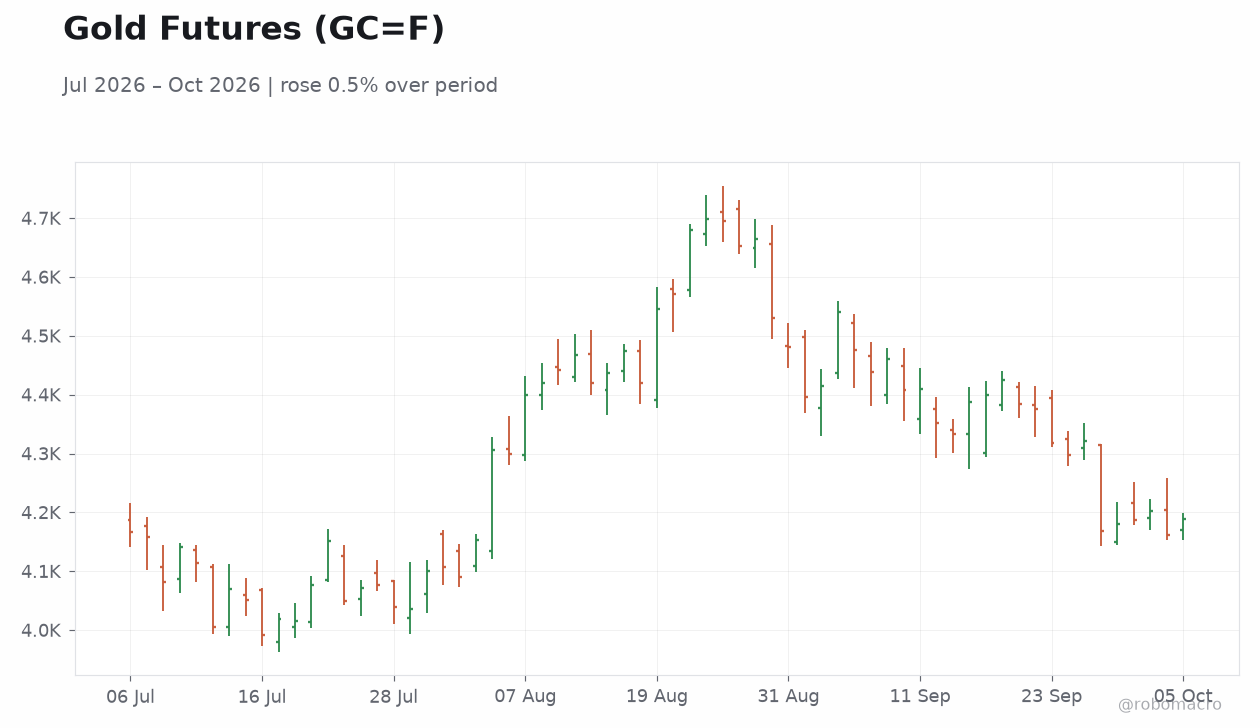
| Gold | 4,187.10 | +0.60% |
| WTI Crude | 90.55 | -0.61% |
| Bitcoin | 86,068.75 | -0.48% |
| US 2Y Treasury | - | - |
| US 10Y Treasury | 5.28% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
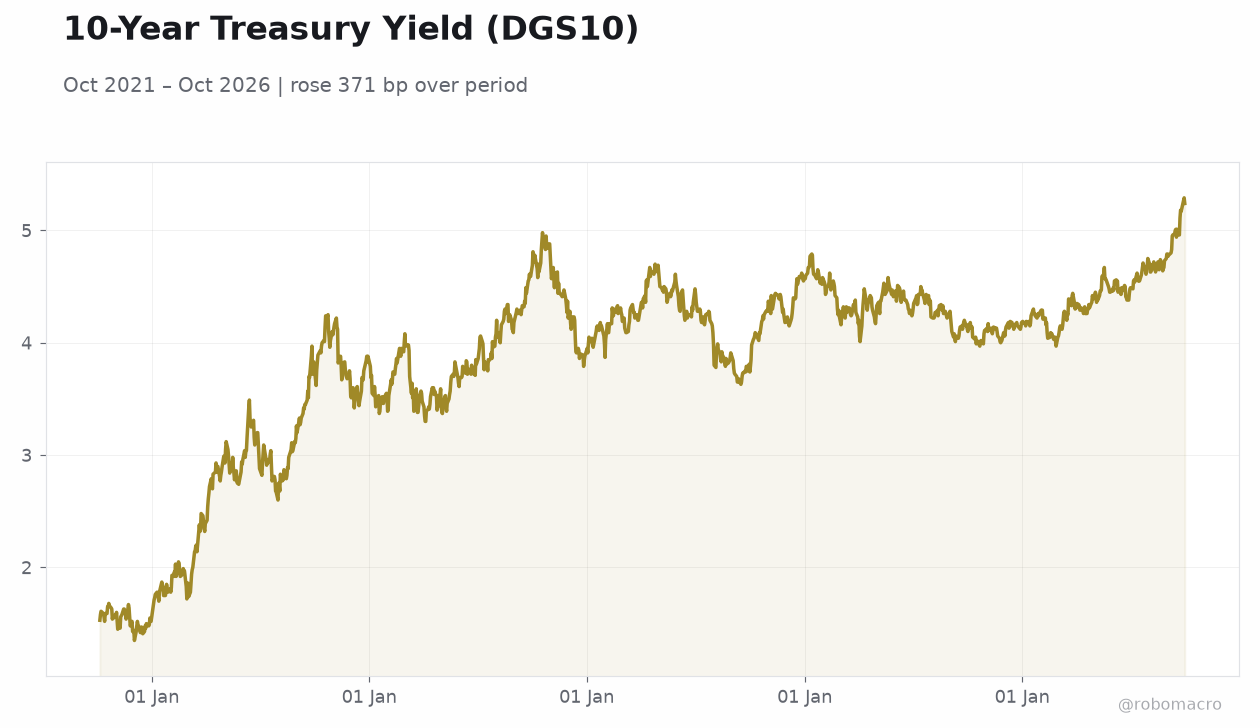 10-Year Treasury Yield (DGS10) | Type: macro_line | Percent: 5.24 (2026-10-01) | Range: 1.35–5.29 | Trend(6pt): 1.53,3.55,4.31,4.35,5.29,5.24
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Services Sector PMI | 55.40 | 55.70 | 10:00 |
| Tuesday (2026-10-06) | |||
| ADP Employment Change Weekly | 20,000 | - | 08:15 |
| Exports Level | 310,700m | - | 08:30 |
| Imports Level | 399,300m | - | 08:30 |
| Trade Balance | -88,600m | -89,800m | 08:30 |
| Speech by Fed's Williams | - | - | 09:05 |
| Speech by Fed's Bowman | - | - | 10:45 |
| API Weekly Crude Oil Stocks | 1.0m | - | 16:30 |
| Speech by Fed's Logan | - | - | 19:00 |
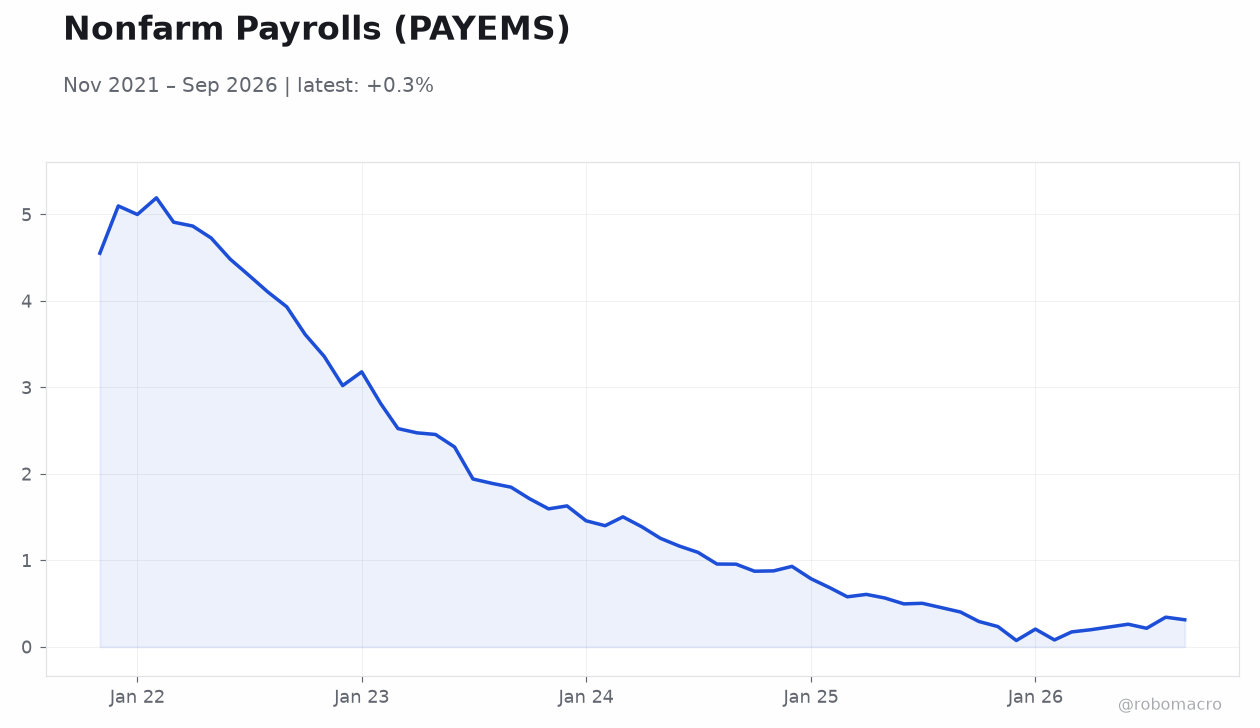
- S&P 500 rose 0.73% to 7,722.72 as September hiring slowed sharply.
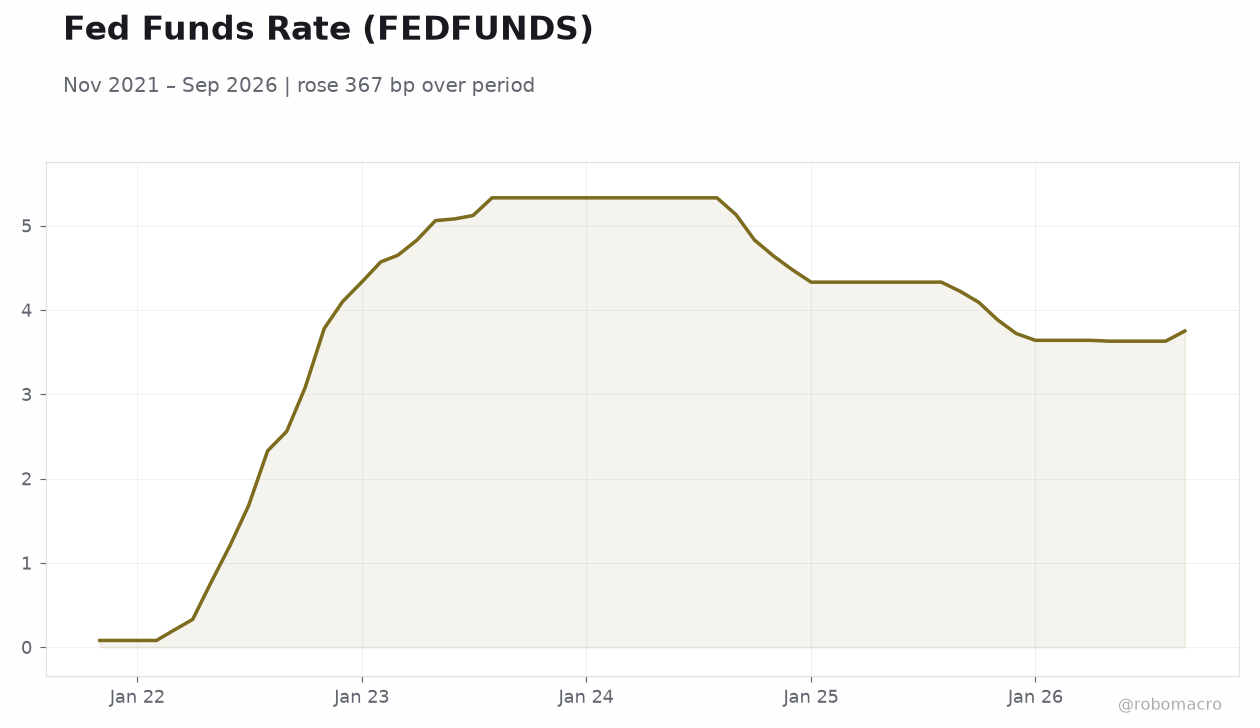
- 10-year Treasury yield climbed 4 bp to 5.28% while Fed funds rate held at 3.88%.
- Markets await today's Services PMI for fresh clues on activity.
Yesterday's Recap
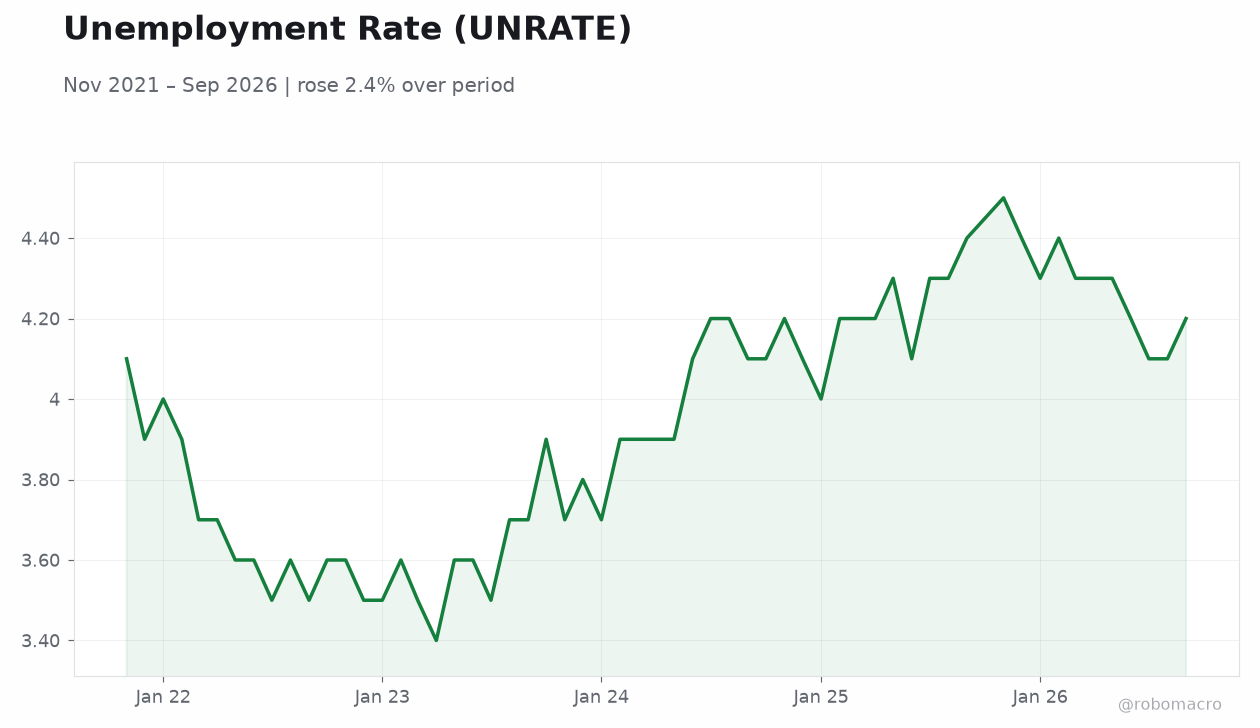
Equity indices advanced after the September employment report showed only 29,000 jobs added, well below expectations, with the unemployment rate at 4.2%. The S&P 500 closed at 7,722.72, up 0.73%, while the Nasdaq 100 gained 1.00% to 30,807.93 and the Russell 2000 rose 0.94%. The 10-year Treasury yield increased 4 bp to 5.28%, reflecting reduced near-term easing bets despite the soft payrolls.
WTI crude fell 0.61% to 90.55 as gold climbed 0.60% to 4,187.10. No high-impact US data printed on the calendar day itself, leaving price action driven by positioning ahead of the October 5 Services PMI. USD/JPY held near 157.92 while EUR/USD eased 0.40% to 1.12.
Broader context shows GDP growth at 2.20% QoQ SAAR and retail sales up 5.36% YoY, underscoring a resilient consumer amid labor-market cooling.
The Day Ahead
The Services Sector PMI at 10:00 ET carries high impact with consensus at 55.7 versus the prior 55.4; a firm print would reinforce steady policy expectations. Tomorrow features ADP employment change, exports, imports and the trade balance at 8:30 ET, followed by speeches from Fed officials Williams, Bowman and Logan. Wednesday brings the FOMC meeting minutes at 14:00 ET, which will provide fresh detail on the committee's latest assessment.
Markets will also monitor MBA 30-year mortgage rates and EIA inventory data midweek. Positioning remains sensitive to any signals on the path for the 3.88% fed funds rate amid CPI at 3.40% YoY.
Other Economic Notes
The September jobs slowdown to 29,000 additions has reinforced views that labor-market cooling is underway while GDP growth registered 2.20% QoQ SAAR in the latest reading. Retail sales expanded 5.36% YoY through August, supporting the narrative of a still-resilient consumer even as hiring stalls. CPI inflation stood at 3.40% YoY in August, keeping real yields attractive and limiting aggressive rate-cut speculation.
Broader commentary highlights that the economy remains above trend yet faces gradual normalization rather than abrupt contraction, with the 4.2% unemployment rate providing a key anchor for policy calibration.