US Macro Daily(Beta Mode)
Services PMI Softens as Equities Rally
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,773.95 | +0.66% |
| Nasdaq 100 | 31,076.44 | +0.87% |
| Dow Jones | 51,267.90 | +0.18% |
| Russell 2000 | 2,847.14 | +0.50% |
| USD/JPY | 157.73 | -0.12% |
| EUR/USD | 1.12 | -0.08% |
| GBP/USD | 1.32 | +0.03% |
| Gold | 4,187.10 | +0.73% |
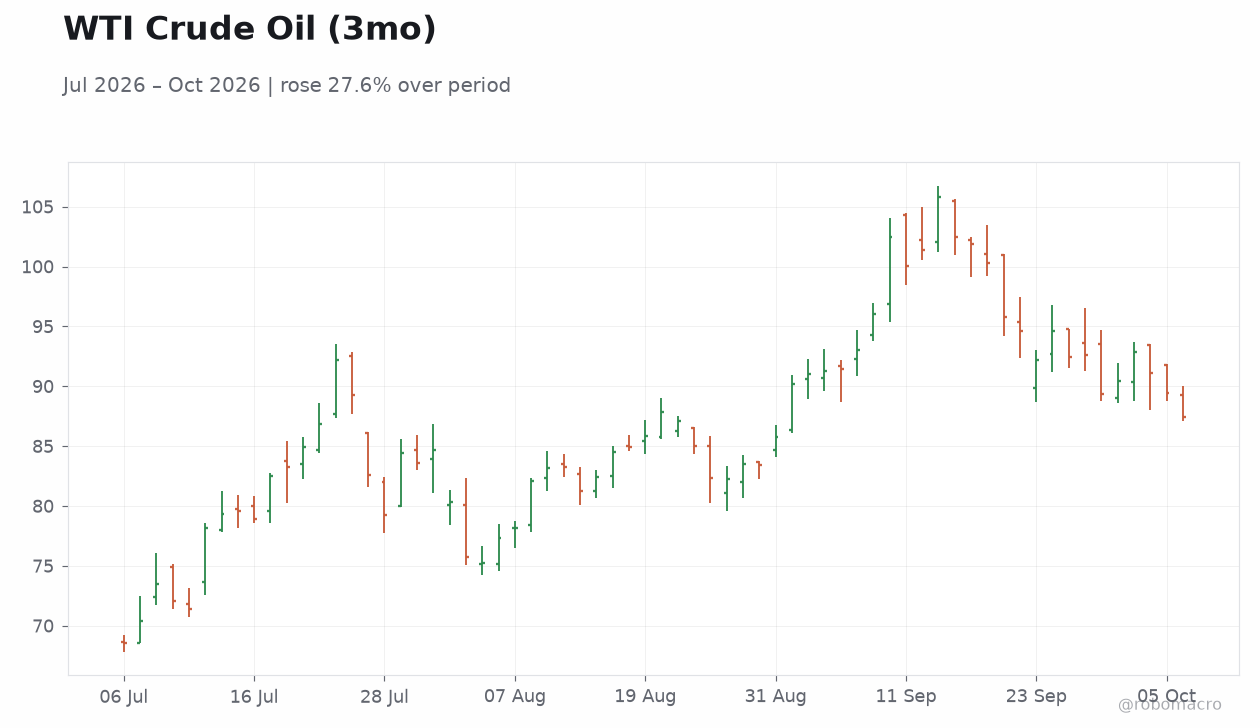
| WTI Crude | 87.50 | -2.16% |
| Bitcoin | 86,155.22 | +0.43% |
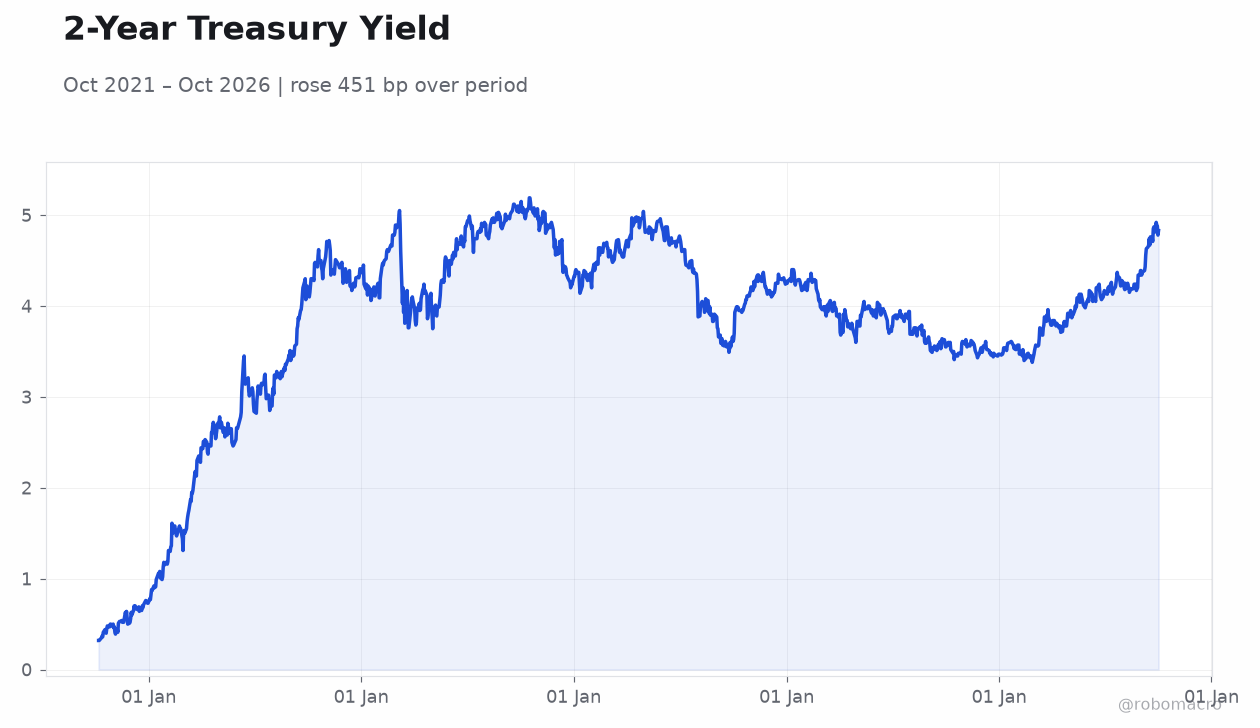
| US 2Y Treasury | 4.84% | +1 bp |
| US 10Y Treasury | 5.31% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Services Sector PMI | 55.40 | 55 | 54.90 |
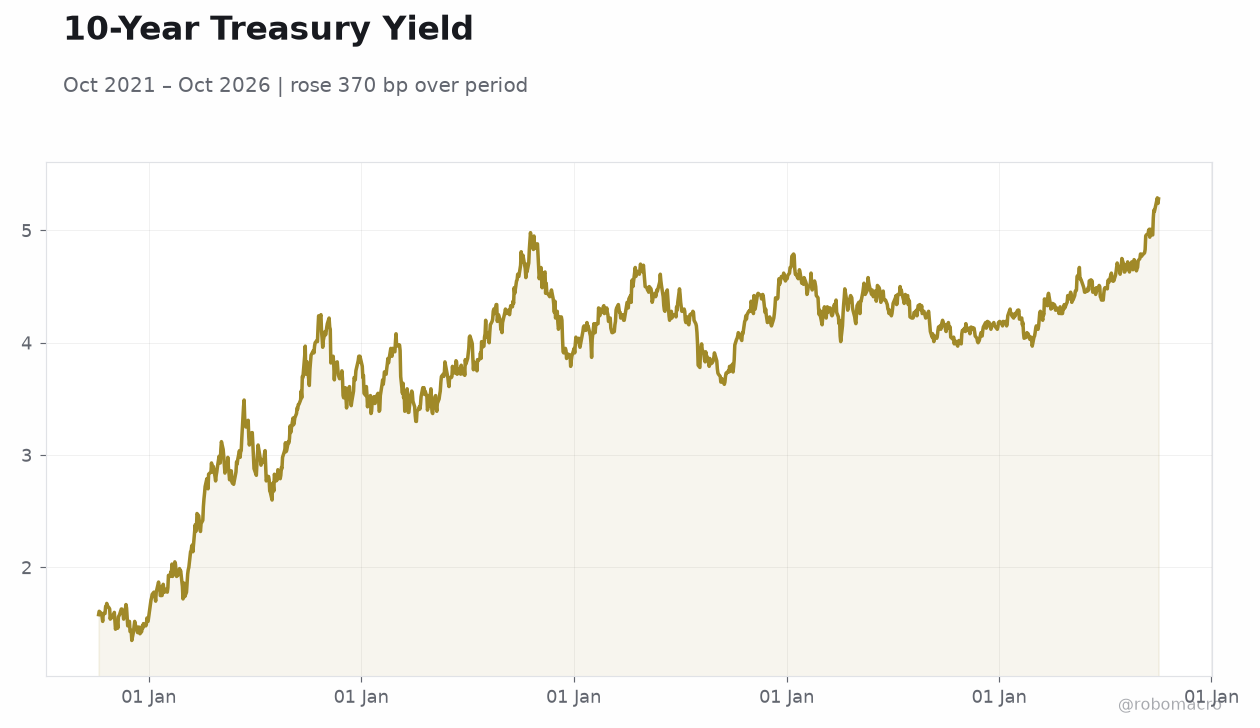 10-Year Treasury Yield | Type: macro_line | Percent: 5.28 (2026-10-02) | Range: 1.35–5.29 | Trend(6pt): 1.58,3.53,4.39,4.4,5.24,5.28
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ADP Employment Change Weekly | 20,000 | - | 08:15 |
| Exports Level | 310,700m | - | 08:30 |
| Imports Level | 399,300m | - | 08:30 |
| Trade Balance | -88,600m | -102,000m | 08:30 |
| Speech by Fed's Williams | - | - | 09:05 |
| Speech by Fed's Bowman | - | - | 10:45 |
| API Weekly Crude Oil Stocks | 1.0m | - | 16:30 |
| Speech by Fed's Logan | - | - | 19:00 |
- US services activity eased to 54.9 in October, below the 55.0 consensus.
- Equities advanced with S&P 500 up 0.66% while 10-year yields rose 3 bp to 5.31%.
- Trade balance and three Fed speeches headline today’s calendar.
Yesterday's Recap
The ISM Services PMI printed 54.9 versus a 55.0 consensus and 55.4 prior, marking a modest downside surprise that signaled slightly softer service-sector momentum. Equity indices closed higher across the board, with the S&P 500 finishing at 7,773.95 (+0.66%), Nasdaq 100 at 31,076.44 (+0.87%), Dow Jones at 51,267.90 (+0.18%), and Russell 2000 at 2,847.14 (+0.50%). Treasury yields climbed, the 2-year reaching 4.84% (+1 bp) and the 10-year 5.31% (+3 bp).
WTI Crude fell 2.16% to 87.50 while gold rose 0.73% to 4,187.10. USD/JPY eased 0.12% to 157.73 and EUR/USD slipped 0.08% to 1.12. The single data release did not shift near-term growth or rate expectations materially.
The Day Ahead
ADP Employment Change, Exports, Imports and the Trade Balance headline the morning releases, with the consensus Trade Balance at –$102 billion. Three Federal Reserve speakers follow: Williams at 09:05 ET, Bowman at 10:45 ET and Logan at 19:00 ET. API Weekly Crude Oil Stocks close the session at 16:30 ET.
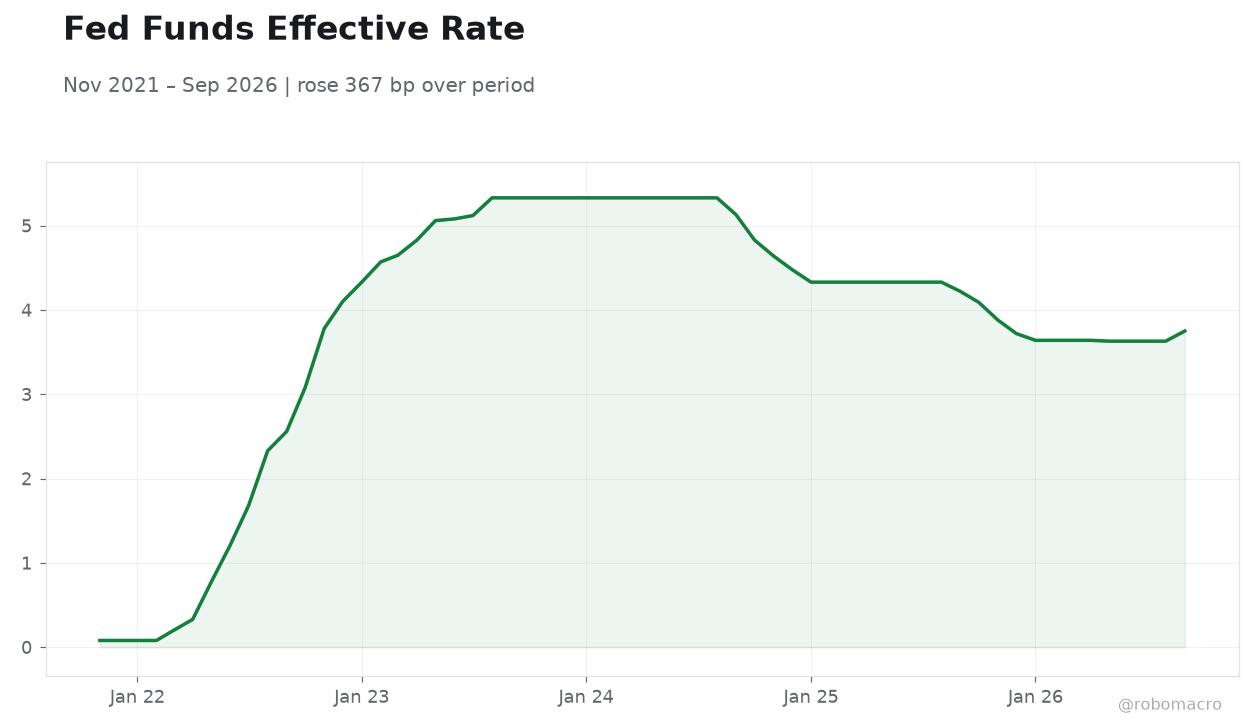
Markets will parse the trade figures for USD direction and scrutinize the speeches for any incremental guidance on the 3.88% fed-funds target. The combination of data and central-bank commentary carries the highest potential to move rate-sensitive assets.
Other Economic Notes
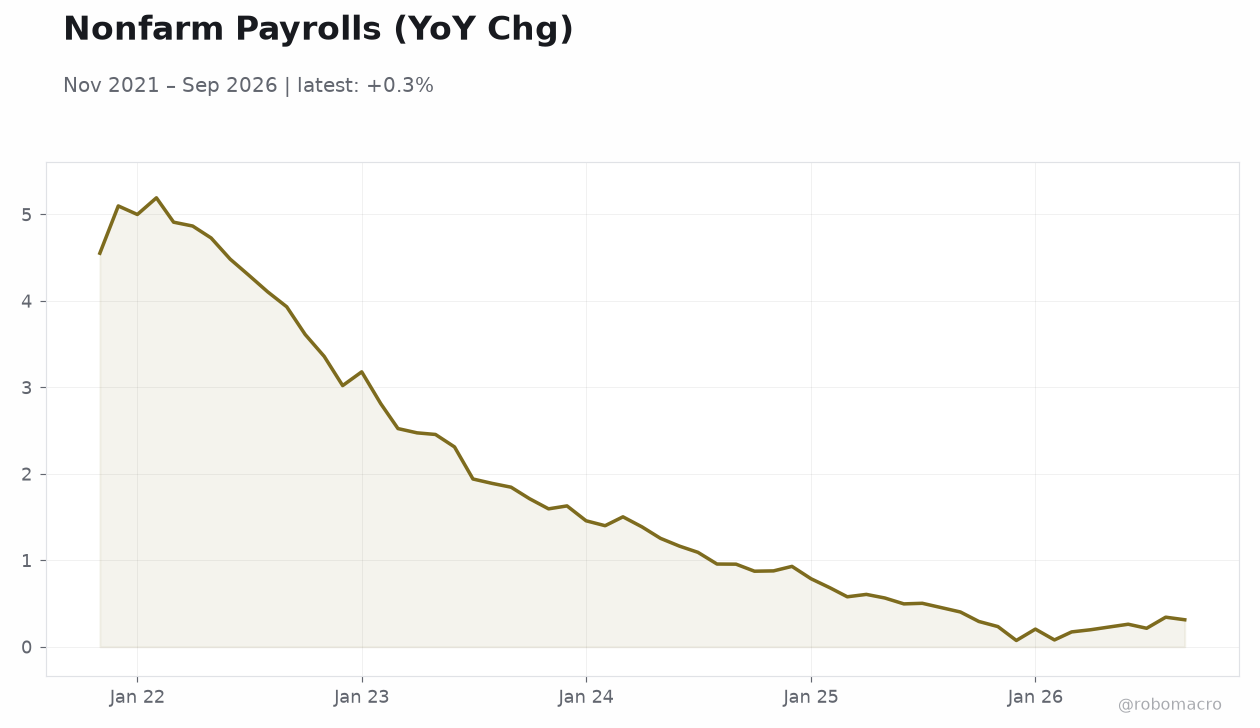
US GDP expanded 2.20% QoQ SAAR in the latest reading while year-over-year growth stood at 2.19%. Retail sales rose 5.36% YoY and the unemployment rate held at 4.20%. These figures continue to depict a resilient expansion even as the softer services print hints at moderating momentum.
Treasury yields remain elevated, with the 10-year at 5.31%, consistent with markets pricing limited near-term policy easing. The combination of solid growth and sticky inflation metrics at 3.40% YoY keeps the policy path data-dependent.
Global Macro News
Global risk appetite improved alongside the US equity rally, supporting commodity currencies and pressuring the dollar modestly. UK budget expectations and gradual dollar gains noted by HSBC added to sterling’s modest advance. ↓ p.2