Stocks Hit Records, Yields Ease Ahead of FOMC Minutes
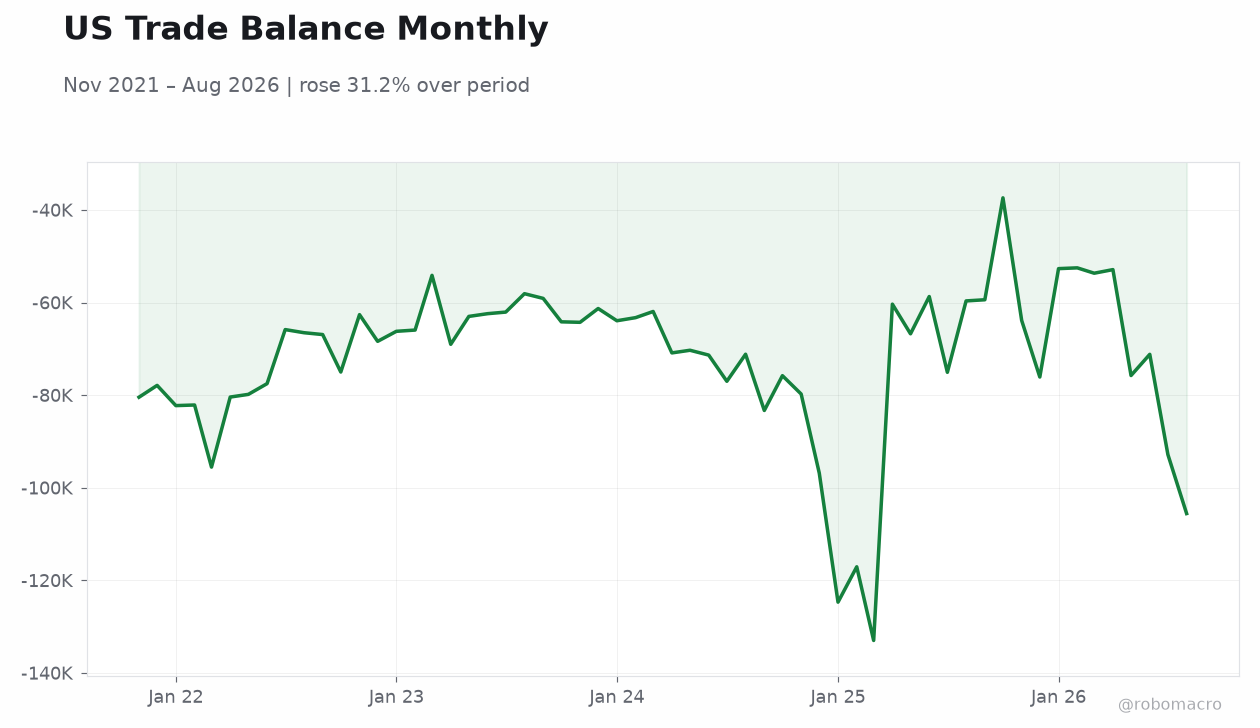
54.90 Services Sector PMI23,750 ADP Employment Change315,200m Exports420,800m Imports-105,600m Trade Balance
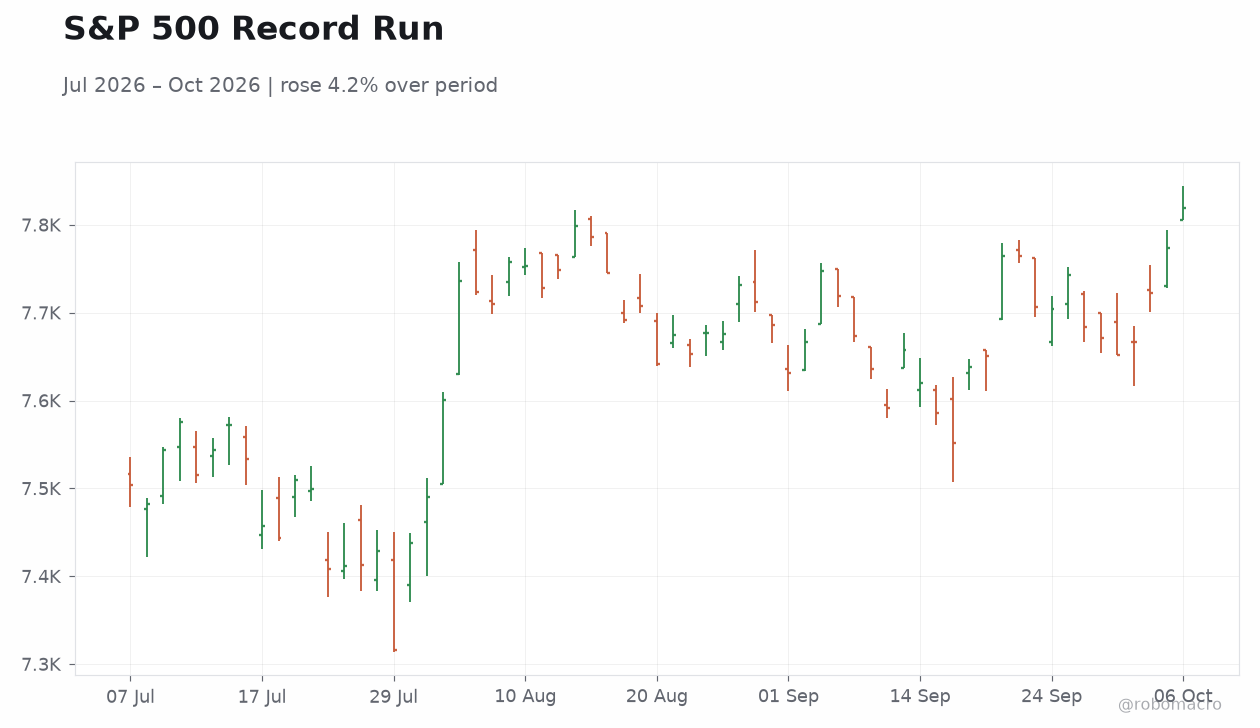
S&P 5007,818.93+0.58%
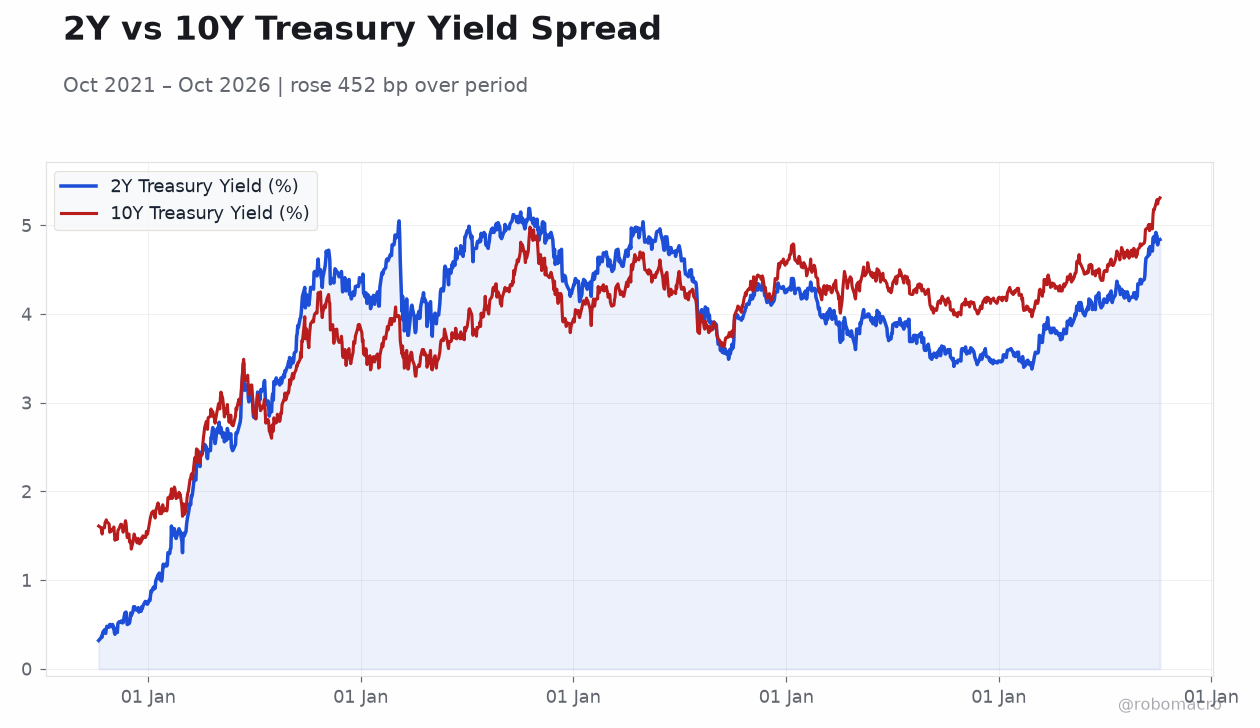
US 10Y Treasury5.27%-4 bp
WTI Crude90.01+0.64%
Gold4,142.00-1.08%
Market Snapshot
| Asset | Level | Change |
|---|
| S&P 500 | 7,818.93 | +0.58% |
| Nasdaq 100 | 31,224.47 | +0.48% |
| Dow Jones | 51,521.28 | +0.49% |
| Russell 2000 | 2,830.30 | -0.59% |
| USD/JPY | 158.32 | +0.22% |
| EUR/USD | 1.12 | -0.21% |
| GBP/USD | 1.32 | -0.01% |
| Gold | 4,142.00 | -1.08% |
| WTI Crude | 90.01 | +0.64% |
| Bitcoin | 83,745.70 | -2.12% |
| US 2Y Treasury | 4.79% | -5 bp |
| US 10Y Treasury | 5.27% | -4 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| Services Sector PMI | 55.40 | 55 | 54.90 |
| ADP Employment Change Weekly | 20,000 | - | 23,750 |
| Exports Level | 310,700m | - | 315,200m |
| Imports Level | 403,600m | - | 420,800m |
| Trade Balance | -92,800m | -102,000m | -105,600m |
| Speech by Fed's Williams | - | - | - |
| Speech by Fed's Bowman | - | - | - |
| Atlanta Fed GDPNow | 3.70 | 3.70 | 3.70 |
| Speech by Fed's Schmid | - | - | - |
| API Weekly Crude Oil Stocks | 1.0m | - | -2.1m |
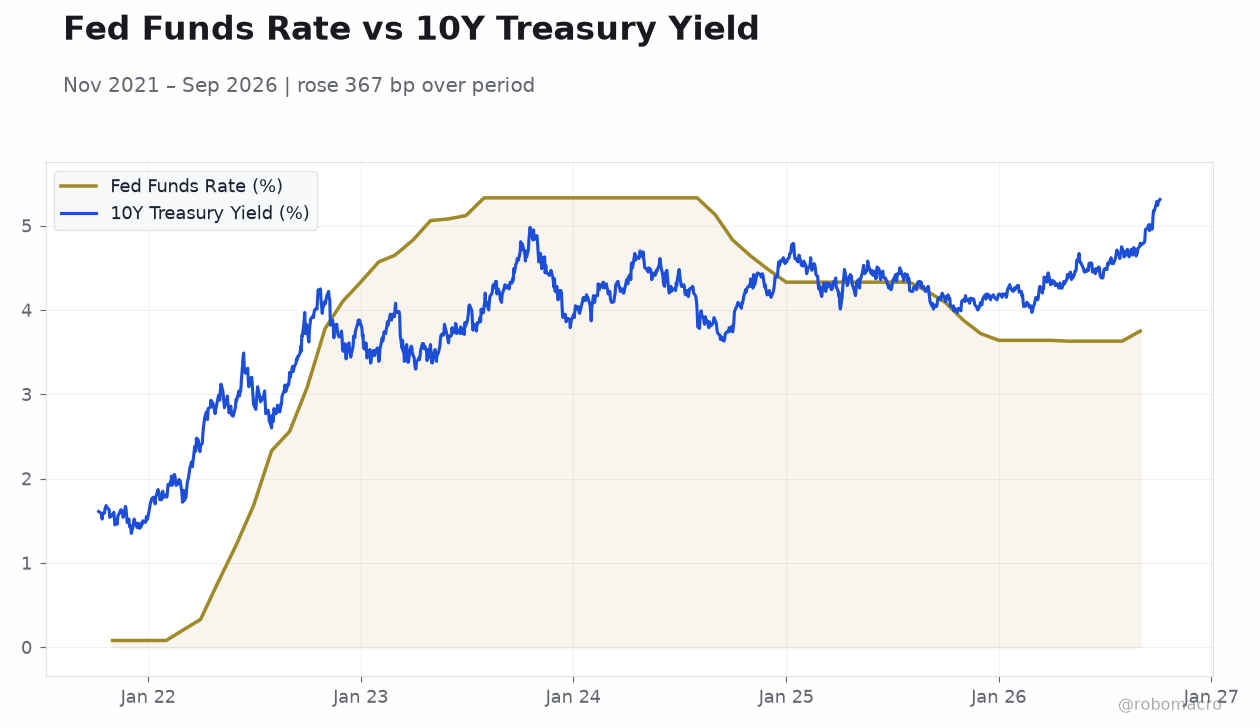 Fed Funds Rate vs 10Y Treasury Yield | Type: macro_line | Fed Funds Rate (%): 3.75 (2026-09-01) | Range: 0.08–5.33 | Trend(6pt): 0.08,4.33,5.33,4.33,3.63,3.75 | 10Y Treasury Yield (%): 5.31 (2026-10-05) | Range: 1.35–5.31 | Trend(6pt): 1.61,3.61,4.42,4.42,5.28,5.31
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| EIA Weekly Crude Oil Inventory | 922,000 | 1.9m | 10:30 |
| EIA Weekly Gasoline Inventory | -1.7m | - | 10:30 |
| FOMC Meeting Minutes | - | - | 14:00 |
|
| Thursday (2026-10-08) |
| Weekly Jobless Claims | 197,000 | 200,000 | 08:30 |
| Atlanta Fed GDPNow | 3.70 | - | 11:00 |
| Speech by Fed's Musalem | - | - | 13:40 |
|
| Friday (2026-10-09) |
| Michigan Consumer Sentiment Prel | 48.10 | 47.60 | 10:00 |
| Speech by Fed's Collins | - | - | 16:00 |
- S&P 500 and Nasdaq notched record closes Tuesday, with the S&P up 0.58% to 7,818.93, as AI chipmaker strength outweighed a rising-rate backdrop.
- The 10-year Treasury yield eased 4 bp to 5.27% and the 2-year fell 5 bp to 4.79%, while the trade deficit widened to $105.6 billion.
- FOMC minutes from the September meeting headline today's calendar at 2:00 p.m. ET, with markets parsing the committee's thinking on the strong economy and the rate path.
Yesterday's Recap
US equities pushed decisively higher, with the S&P 500 gaining 0.58% to 7,818.93 and the Nasdaq 100 adding 0.48% to 31,224.47, both closing at fresh record highs as AI chipmakers led the advance. The Dow rose 0.49% to 51,521.28, though small caps lagged, with the Russell 2000 slipping 0.59% to 2,830.30 in a rotation away from domestic cyclicals. Treasuries firmed across the curve: the 10-year yield eased 4 bp to 5.27% and the 2-year declined 5 bp to 4.79%, a modest rally that helped underpin the equity bid.
The dollar softened against the euro, with EUR/USD up 0.21% to 1.12, while USD/JPY climbed 0.22% to 158.32. Gold retreated 1.08% to $4,142 as traders positioned ahead of the FOMC minutes. On the data front, the Services PMI printed 54.9 versus 55 expected, down from 55.4 prior but still firmly in expansion.
The trade balance widened to $105.6 billion from $92.8 billion, as imports rose to $420.8 billion against exports of $315.2 billion. Weekly ADP private payrolls rose 23,750 after a 20,000 prior print. WTI crude gained 0.64% to $90.01, and Bitcoin fell 2.12% to $83,745.70.
API crude stocks drew 2.09 million barrels after a 1.02 million-barrel build.
The Day Ahead
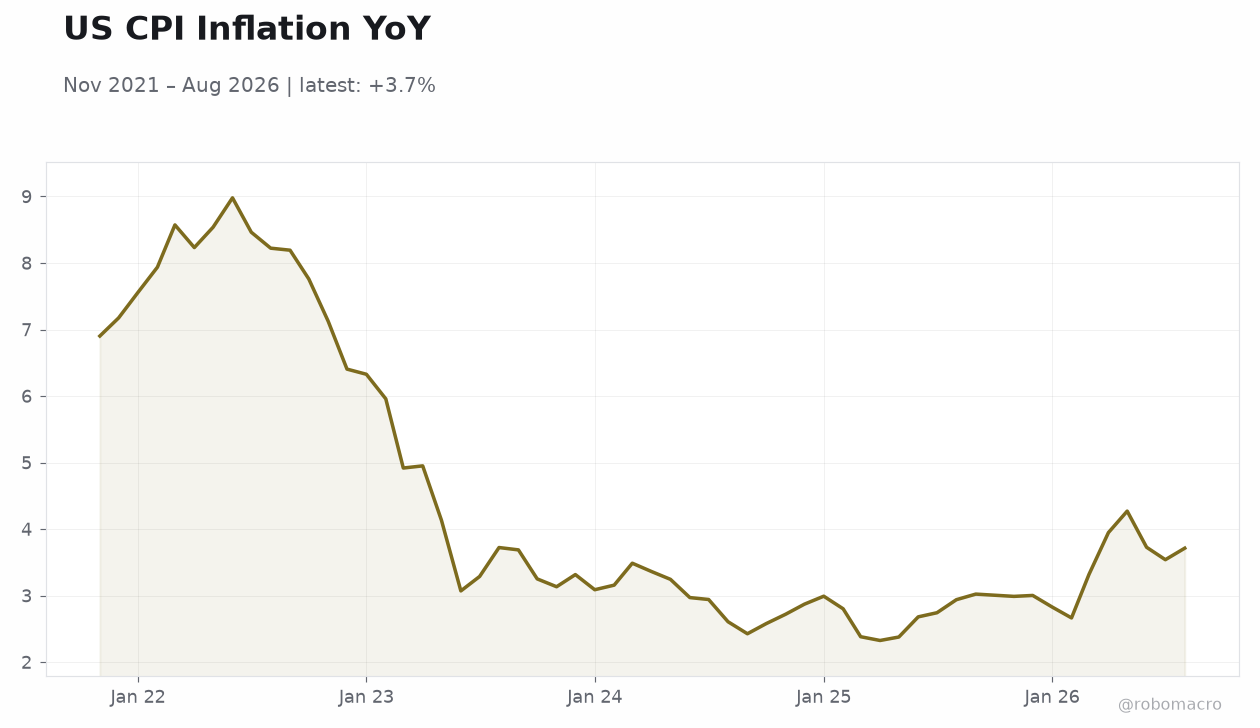
Today's centerpiece is the FOMC meeting minutes at 2:00 p.m. ET, which will detail the committee's internal deliberations from its most recent gathering. Markets will scrutinize the minutes for clues on the balance of risks around inflation persistence and the pace of any future adjustments, particularly given the strong growth backdrop the Fed has cited.
Earlier, at 10:30 a.m. ET, the EIA releases weekly petroleum status data, with crude stocks expected to build 1.9 million barrels following last week's 922,000-barrel increase; the gasoline inventory print will also draw attention. The MBA 30-year mortgage rate, last at 7.3%, will show whether financing costs continue to pressure housing demand.
↓ p.2
Page 1
Never miss an issue
Subscribe to US Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.