US Macro Daily(Beta Mode)
Trade Gap Widens as Oil Jumps and Yields Rise
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,801.77 | -0.22% |
| Nasdaq 100 | 31,160.08 | -0.21% |
| Dow Jones | 51,179.87 | -0.66% |
| Russell 2000 | 2,793.20 | -1.31% |
| USD/JPY | 158.20 | -0.06% |
| EUR/USD | 1.12 | -0.37% |
| GBP/USD | 1.32 | -0.30% |
| Gold | 4,150.70 | +0.24% |
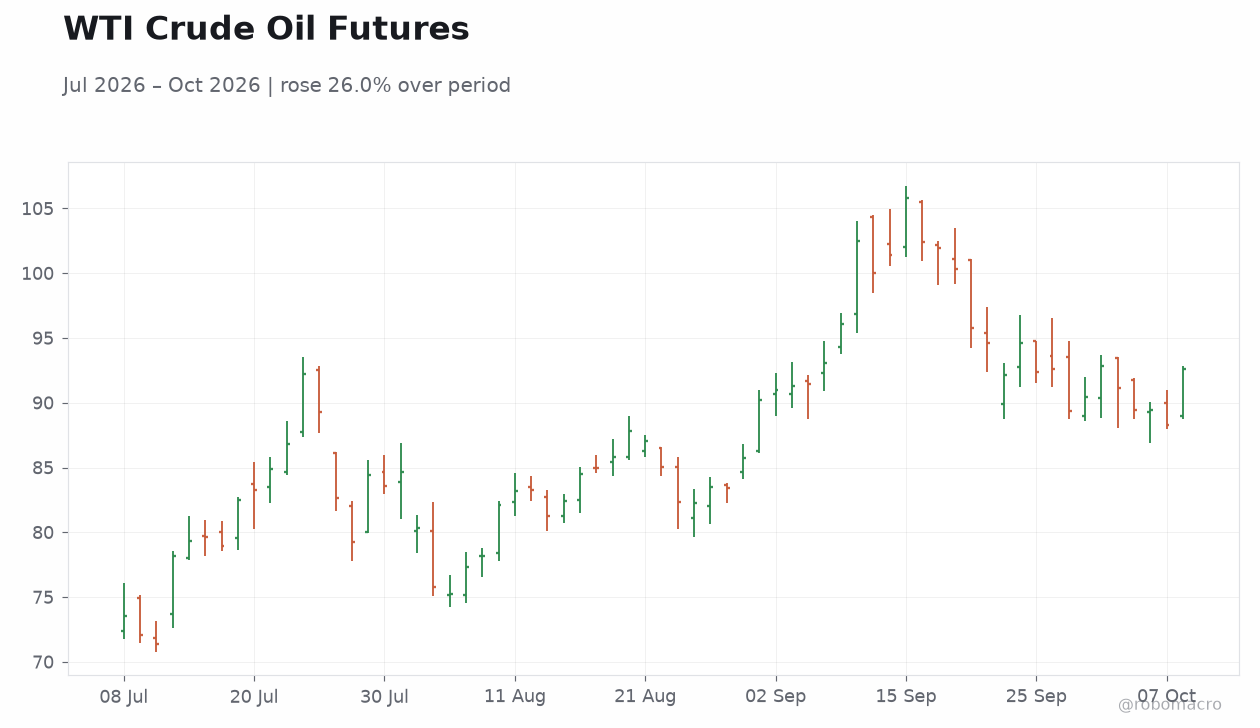
| WTI Crude | 92.50 | +4.78% |
| Bitcoin | 82,617.49 | -0.79% |
| US 2Y Treasury | 4.77% | -2 bp |
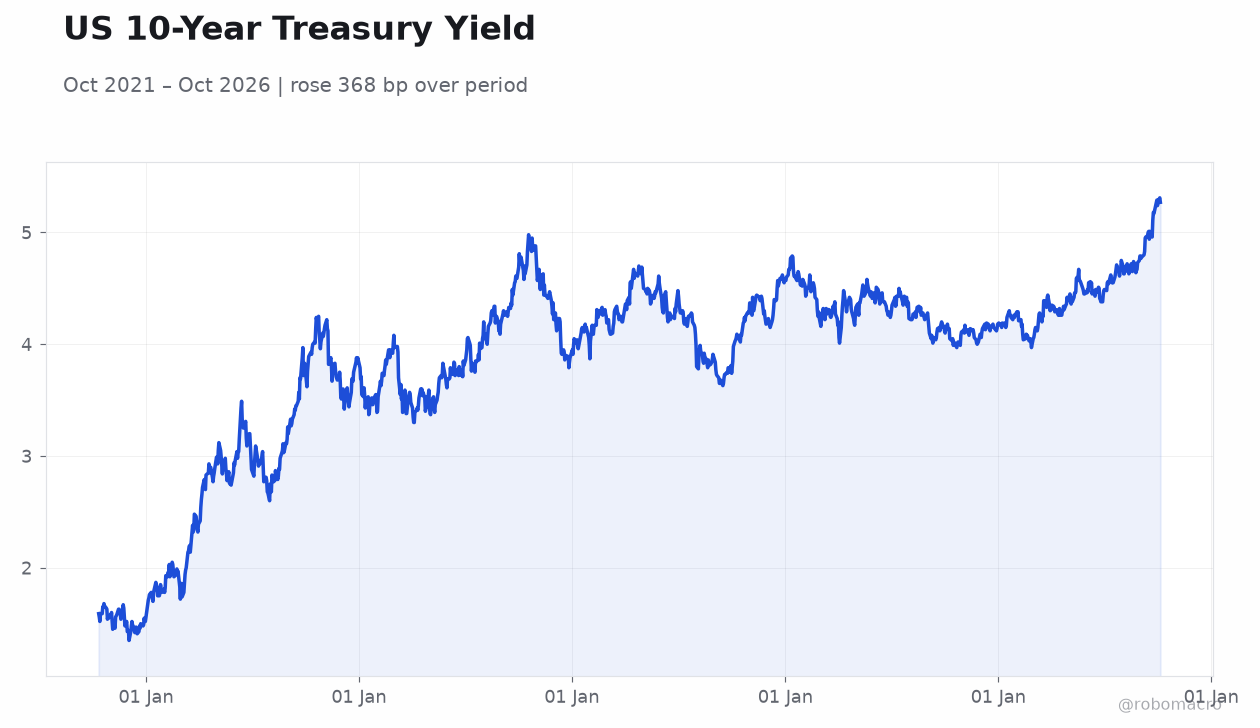
| US 10Y Treasury | 5.28% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Exports Level | 310,700m | - | 315,200m |
| Imports Level | 403,600m | - | 420,800m |
| Trade Balance | -92,800m | -102,000m | -105,600m |
| Speech by Fed's Williams | - | - | - |
| Speech by Fed's Bowman | - | - | - |
| Atlanta Fed GDPNow | 3.70 | 3.70 | 3.70 |
| Speech by Fed's Schmid | - | - | - |
| API Weekly Crude Oil Stocks | 1.0m | - | -2.1m |
| Speech by Fed's Logan | - | - | - |
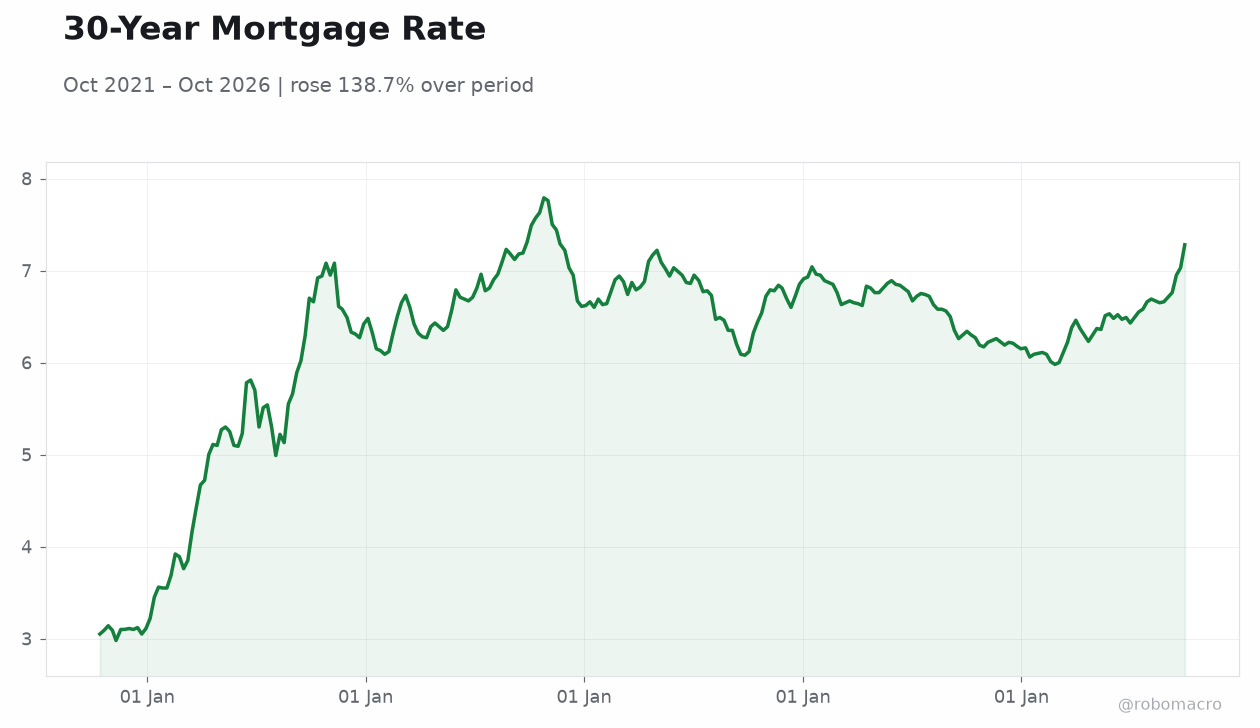
| MBA 30-Year Mortgage Rate | 7.30 | - | 7.49 |
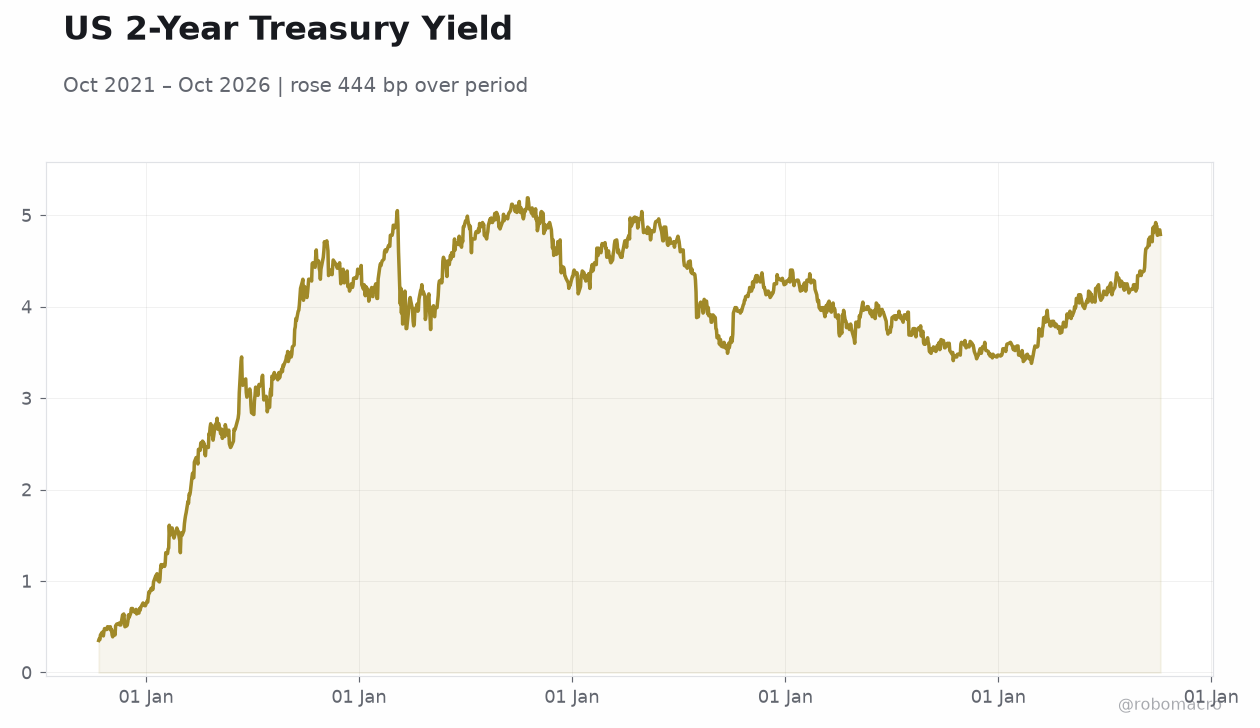 US 2-Year Treasury Yield | Type: macro_line | Percent: 4.79 (2026-10-06) | Range: 0.35–5.19 | Trend(6pt): 0.35,4.2,4.74,3.86,4.84,4.79
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Speech by Fed's Musalem | - | - | 13:40 |
| Friday (2026-10-09) | |||
| Michigan Consumer Sentiment Prel | 48.10 | 47.60 | 10:00 |
| Speech by Fed's Collins | - | - | 16:00 |
- US trade deficit expanded to $105.6 billion in August, exceeding consensus forecasts.
- EIA crude inventories posted a sharp 3.186 million barrel draw, lifting WTI 4.78 percent.
- Equities closed lower with the Russell 2000 falling 1.31 percent amid climbing 10-year yields.
Yesterday's Recap
US exports rose to $315.2 billion while imports climbed to $420.8 billion, widening the trade balance to a larger-than-expected $105.6 billion deficit. The MBA 30-year mortgage rate increased to 7.49 percent. EIA data showed a 3.186 million barrel crude draw against a 1.7 million build consensus and a 382,000 barrel gasoline build.
API reported a 2.09 million barrel crude stock decline. Atlanta Fed GDPNow held steady at 3.7 percent. Equities retreated, with the S&P 500 down 0.22 percent, Nasdaq 100 off 0.21 percent, Dow Jones declining 0.66 percent and Russell 2000 falling 1.31 percent.
The 2-year Treasury yield eased 2 basis points to 4.77 percent while the 10-year yield rose 1 basis point to 5.28 percent. WTI crude surged 4.78 percent to $92.50 and gold advanced 0.24 percent. Multiple Fed speakers, including Williams, Bowman, Schmid and Logan, addressed audiences without shifting policy signals.
The Day Ahead
Weekly jobless claims are scheduled for release at 8:30 a.m. ET with consensus near 200,000. The Atlanta Fed will update its GDPNow estimate at 11:00 a.m.
ET. Fed Governor Christopher Waller is set to speak at 4:30 a.m. ET.
Markets will monitor any fresh signals on labor market momentum and growth tracking. Treasury yields and equity futures will react to the claims print and Waller remarks. Oil volatility may persist given recent inventory surprises.
Fed Governor Musalem is also scheduled to speak at 1:40 p.m. ET, adding to the roster of central bank commentary that could influence rate expectations.
Other Economic Notes
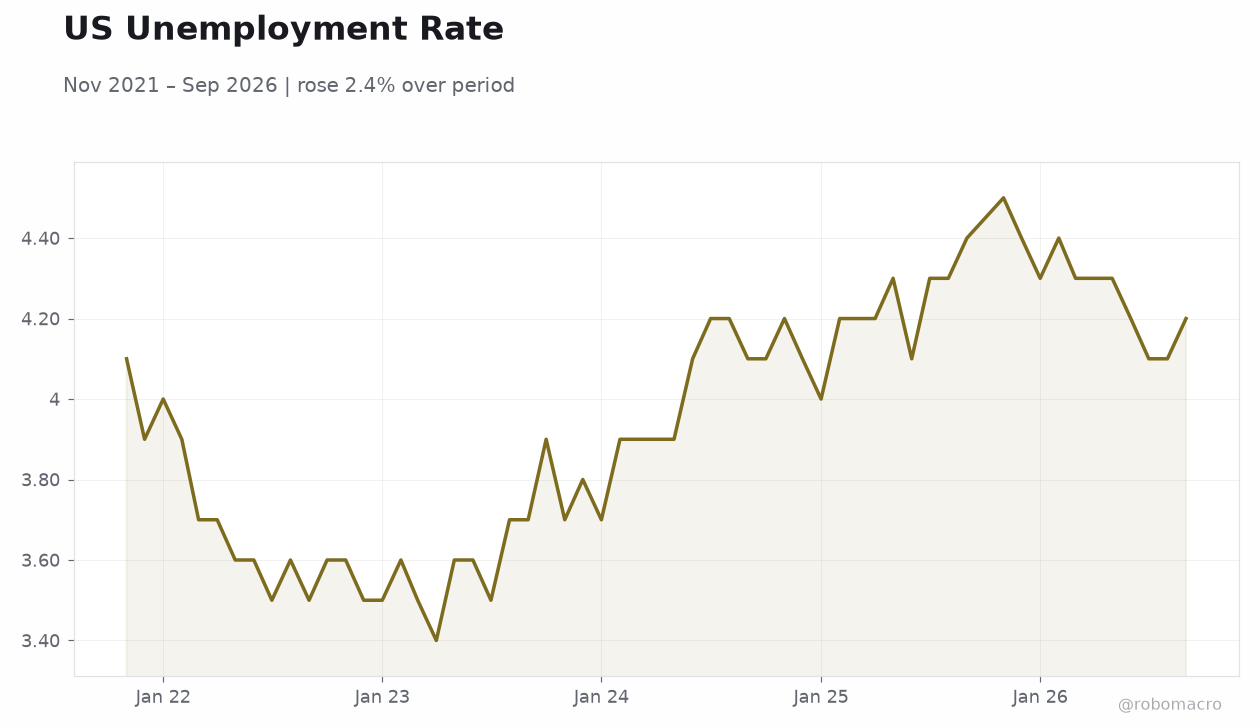
The 3.88 percent Fed funds rate and 4.2 percent unemployment rate continue to anchor expectations for gradual policy easing. Retail sales growth at 5.36 percent year-over-year supports consumer resilience despite higher borrowing costs. CPI at 3.4 percent year-over-year keeps inflation above the 2 percent target and limits aggressive rate-cut bets.
↓ p.2