Yields Ease as Claims Hold Near Lows
-105,600m Trade Balance3.70 Atlanta Fed GDPNow-2.1m API Weekly Crude Oil7.49 MBA 30-Year Mortgage Rate-3.2m EIA Weekly Crude Oil
S&P 5007,765.36-0.47%
US 10Y Treasury5.22%-6 bp
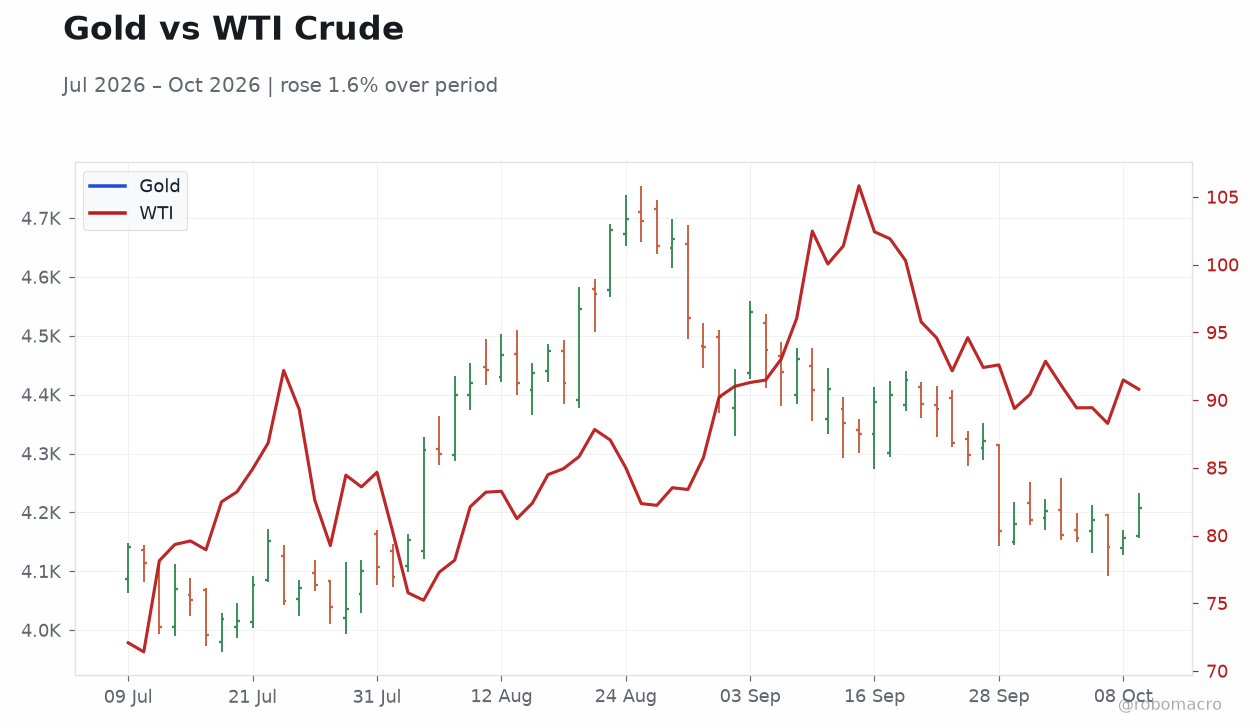
WTI Crude90.82-0.73%
Gold4,204.90+1.15%
Market Snapshot
| Asset | Level | Change |
|---|
| S&P 500 | 7,765.36 | -0.47% |
| Nasdaq 100 | 30,725.81 | -1.39% |
| Dow Jones | 51,231.64 | +0.10% |
| Russell 2000 | 2,794.13 | +0.03% |
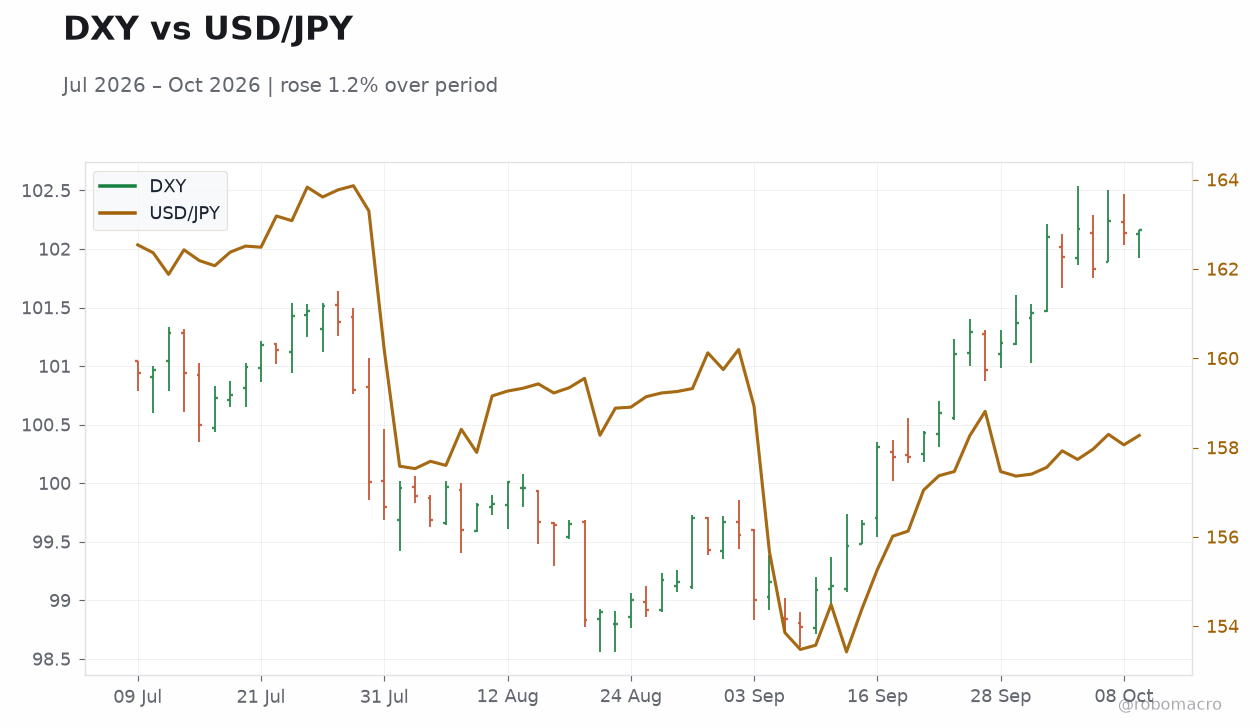
| USD/JPY | 158.31 | +0.16% |
| EUR/USD | 1.12 | +0.08% |
| GBP/USD | 1.32 | +0.08% |
| Gold | 4,204.90 | +1.15% |
| WTI Crude | 90.82 | -0.73% |
| Bitcoin | 82,438.11 | +0.93% |
| US 2Y Treasury | 4.75% | -2 bp |
| US 10Y Treasury | 5.22% | -6 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| Trade Balance | -92,800m | -102,000m | -105,600m |
| Speech by Fed's Williams | - | - | - |
| Speech by Fed's Bowman | - | - | - |
| Atlanta Fed GDPNow | 3.70 | 3.70 | 3.70 |
| Speech by Fed's Schmid | - | - | - |
| API Weekly Crude Oil Stocks | 1.0m | - | -2.1m |
| Speech by Fed's Logan | - | - | - |
| MBA 30-Year Mortgage Rate | 7.30 | - | 7.49 |
| EIA Weekly Crude Oil Inventory | 922,000 | 1.7m | -3.2m |
| EIA Weekly Gasoline Inventory | -1.7m | -1.7m | 382,000 |
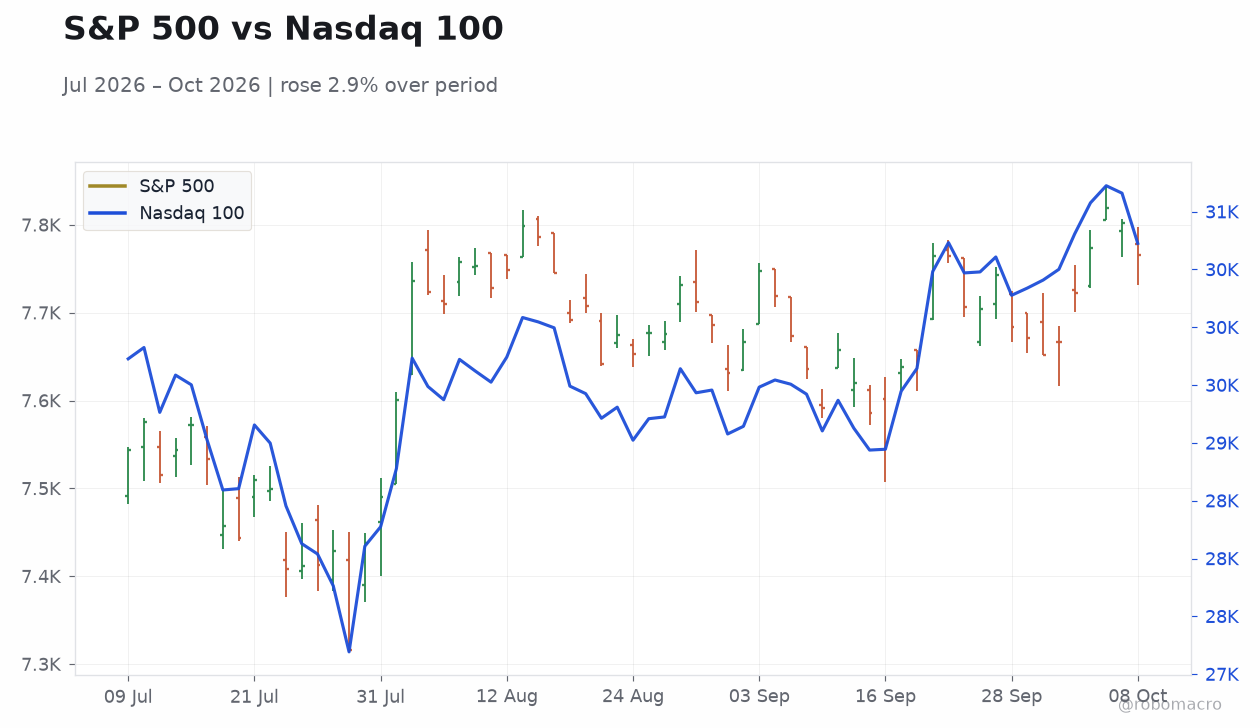 S&P 500 vs Nasdaq 100 | Type: market_hloc | S&P 500: 7765 (2026-10-08) | Range: 7316–7819 | Trend(5pt): 7544,7490,7653,7552,7765 | Nasdaq 100: 3.073e+04 (2026-10-08) | Range: 2.719e+04–3.122e+04 | Trend(5pt): 2.973e+04,2.827e+04,2.902e+04,2.895e+04,3.073e+04
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| Michigan Consumer Sentiment Prel | 48.10 | 47.60 | 10:00 |
| Speech by Fed's Collins | - | - | 16:00 |
- Jobless claims ticked down to 197,000, underscoring labor-market resilience while the Atlanta Fed trimmed its Q4 GDPNow estimate to 3.6%.
- The 10-year yield eased 6 bp to 5.22% and the 2-year slipped 2 bp to 4.75%, with the curve bull-flattening as growth trades cooled.
- Equities diverged: Nasdaq 100 fell 1.39% while the Dow gained 0.10%, and gold rallied 1.15% to $4,204.90.
Yesterday's Recap
US equity markets closed mixed on Thursday, with the S&P 500 down 0.47% at 7,765.36 and the Nasdaq 100 lagging at -1.39%, while the Dow Jones bucked the trend, adding 0.10% to 51,231.64 and the Russell 2000 was flat at +0.03%. The labor market remained the focal point: weekly jobless claims printed at 197,000, below both the prior week's 199,000 and the 200,000 consensus, reinforcing the picture of a resilient hiring backdrop. The Atlanta Fed's GDPNow tracker was revised down to 3.6% from 3.7%, a modest trim to fourth-quarter growth expectations that nonetheless leaves the model pointing to well-above-trend expansion.
In energy markets, EIA data showed crude inventories fell 3.19 million barrels against expectations for a 1.7 million barrel build, while gasoline stocks rose 382,000 barrels; the API's earlier estimate had shown a 2.09 million barrel draw. WTI settled at $90.82, down 0.73%, despite the tighter inventory picture. Treasury yields retreated across the curve, with the 10-year easing 6 bp to 5.22% and the 2-year down 2 bp at 4.75%, narrowing the spread by 4 bp.
The dollar was mixed, with EUR/USD up 0.08% at 1.12 and USD/JPY firming 0.16% to 158.31.
The Day Ahead
Friday's calendar is light on Tier-1 releases, leaving markets to consolidate Thursday's moves and position into the weekend. The sole high-impact print is the University of Michigan's preliminary consumer sentiment reading at 10:00 ET, with consensus looking for 47.6 versus the prior 48.1 — a modest dip that would nonetheless keep sentiment near cycle lows and sharpen focus on the inflation-expectations component. Attention will also remain on the mortgage market after the MBA 30-year rate printed at 7.49% on Wednesday, up from 7.30%, a level that continues to pressure housing affordability and refi activity.
With no other major data scheduled, Fed speak takes on added weight: officials have been active this week, and any additional commentary will be parsed for signals on the rate path into year-end. Energy traders will watch for the next round of inventory data and any escalation in the Middle East after oil surged more than 5% midweek on reports of potential new US strikes on Iran. ↓ p.2
Page 1
Never miss an issue
Subscribe to US Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.