Stocks Near Records; Yields Grind Higher Into CPI
S&P 5007,811.54+0.59%
US 10Y Treasury5.24%+2 bp
WTI Crude92.85+1.09%
Gold4,201.80-0.34%
Market Snapshot
| Asset | Level | Change |
|---|
| S&P 500 | 7,811.54 | +0.59% |
| Nasdaq 100 | 30,883.15 | +0.51% |
| Dow Jones | 51,654.95 | +0.83% |
| Russell 2000 | 2,806.98 | +0.46% |
| USD/JPY | 158.06 | +0.00% |
| EUR/USD | 1.12 | -0.29% |
| GBP/USD | 1.32 | +0.02% |
| Gold | 4,201.80 | -0.34% |
| WTI Crude | 92.85 | +1.09% |
| Bitcoin | 83,358.20 | -0.38% |
| US 2Y Treasury | 4.80% | +5 bp |
| US 10Y Treasury | 5.24% | +2 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| No events available |
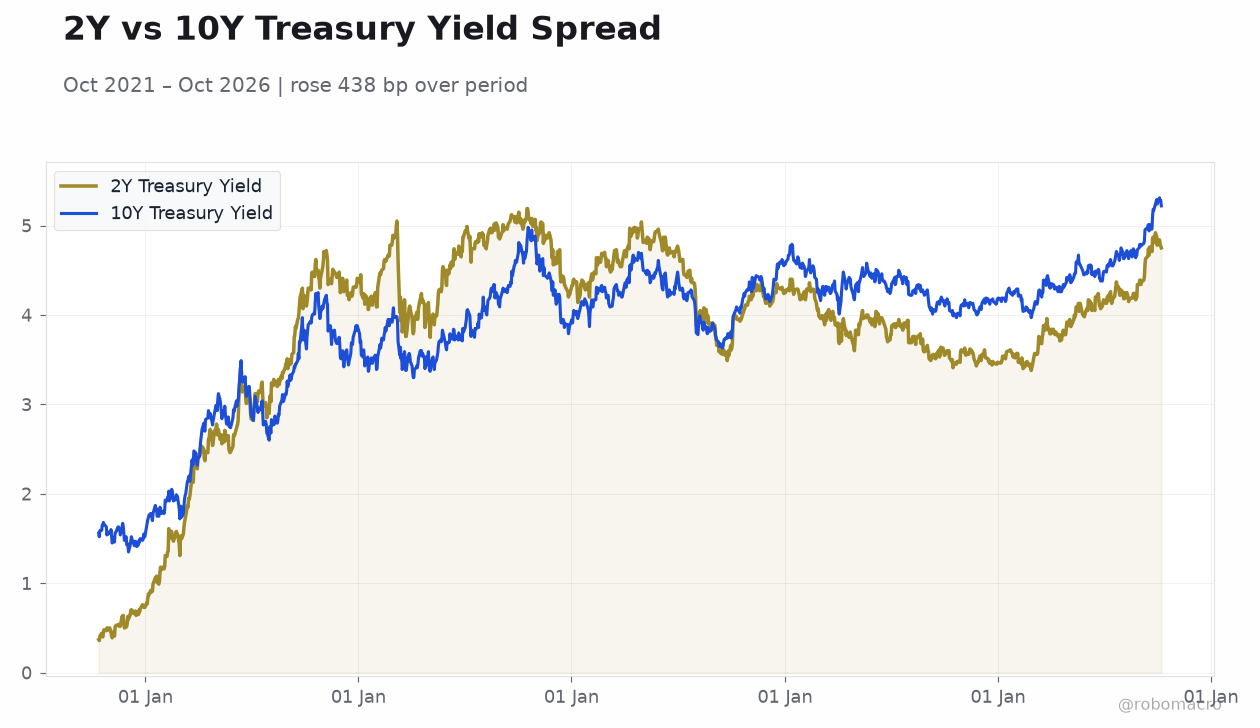 2Y vs 10Y Treasury Yield Spread | Type: macro_line | 2Y Treasury Yield: 4.75 (2026-10-08) | Range: 0.36–5.19 | Trend(6pt): 0.37,4.12,4.97,3.86,4.79,4.75 | 10Y Treasury Yield: 5.22 (2026-10-08) | Range: 1.35–5.31 | Trend(6pt): 1.56,3.43,4.55,4.35,5.27,5.22
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| Fed Hammack Speech | - | - | 12:50 |
|
| Tuesday (2026-10-13) |
| Speech by Fed's Waller | - | - | 03:45 |
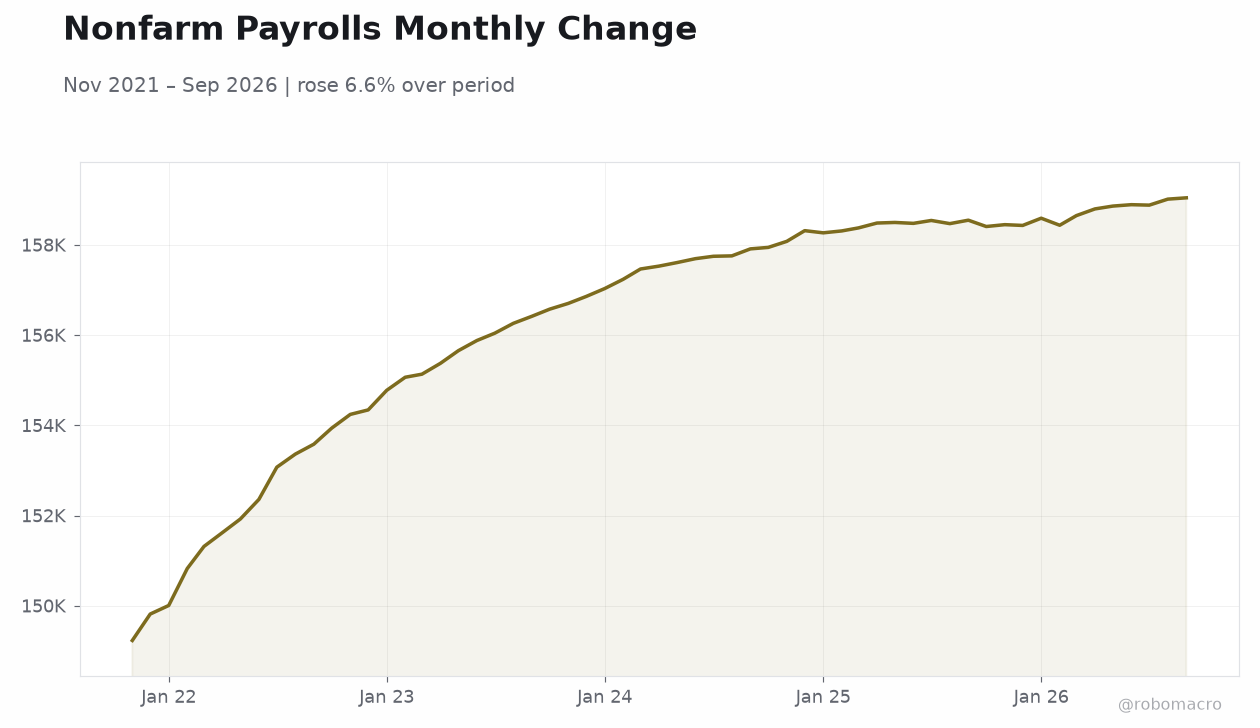
| ADP Employment Change Weekly | 23,750 | - | 08:15 |
| Existing Home Sales | 4.0m | 4.0m | 10:00 |
| Existing Home Sales Month-over-Month | -2 | - | 10:00 |
| Speech by Fed's Barkin | - | - | 13:00 |
| Monthly Budget Statement | -167,000m | -28,000m | 14:00 |
| Speech by Fed's Collins | - | - | 16:00 |
|
| Wednesday (2026-10-14) |
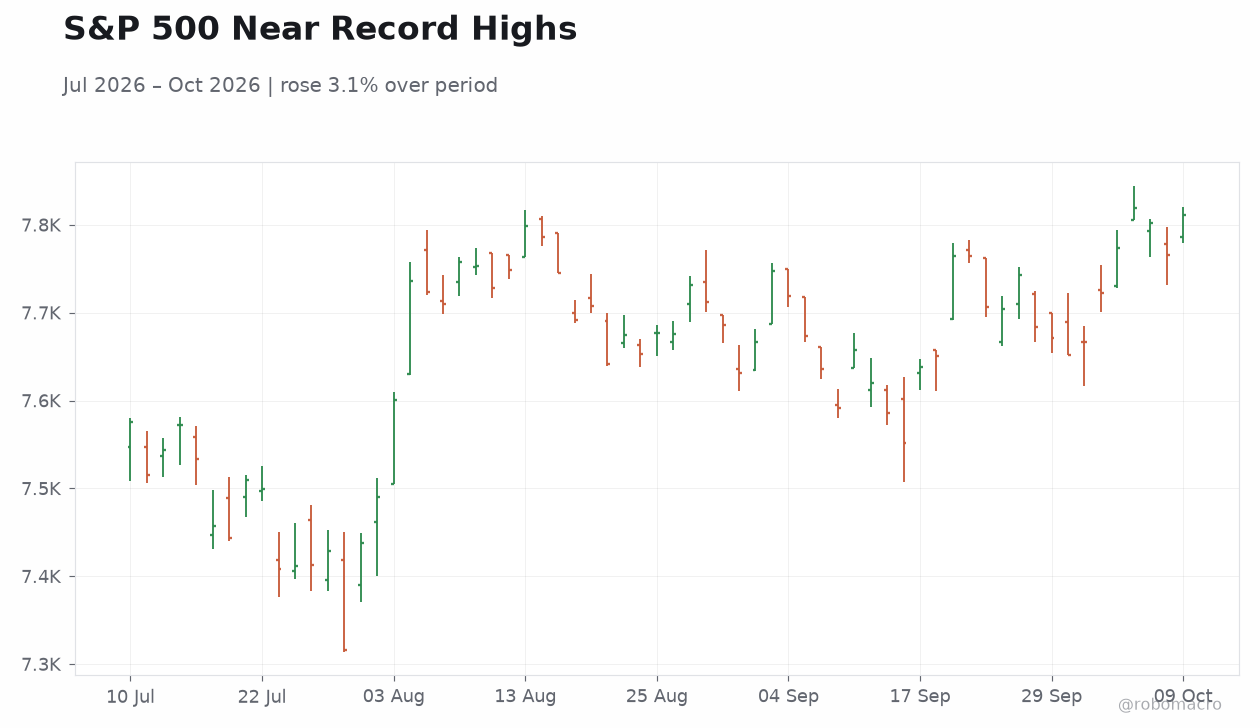
- Wall Street closed Friday near record highs, with the S&P 500 up 0.59% to 7,811.54 and the Dow gaining 0.83% to 51,654.95, as investors positioned for Wednesday's CPI and the start of earnings season.
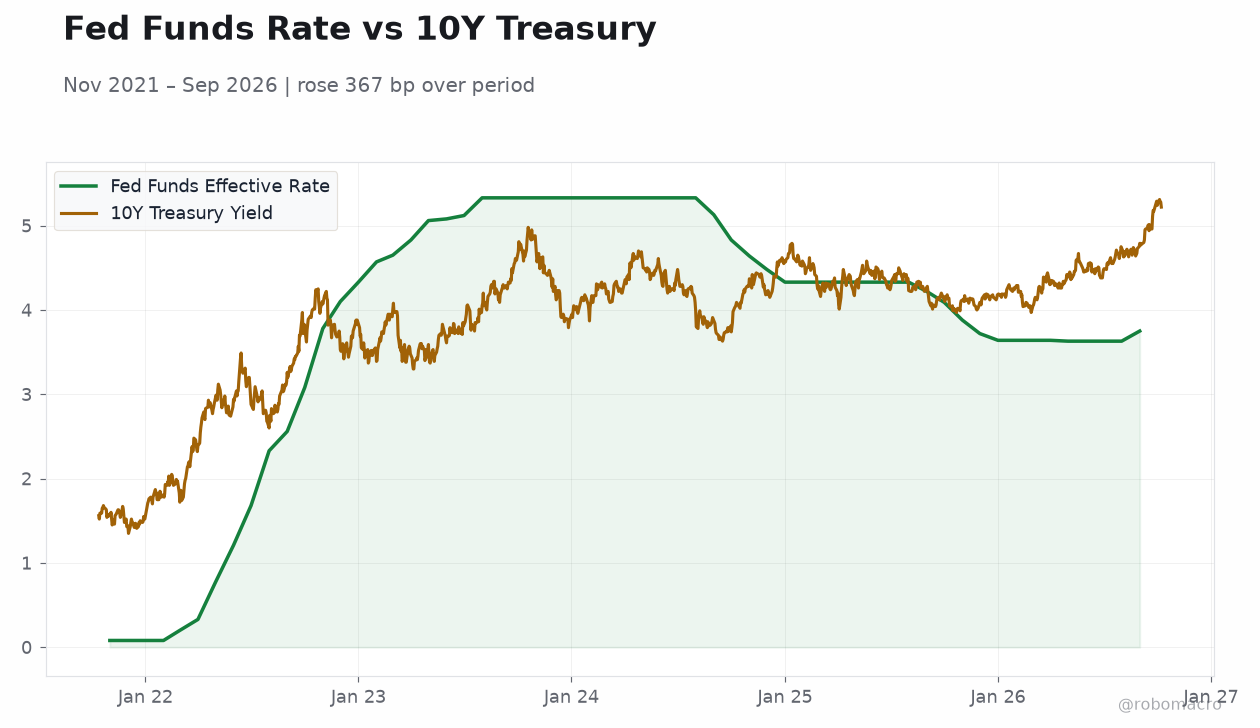
- Treasury yields firmed, with the 2-year up 5 bp to 4.80% and the 10-year up 2 bp to 5.24%, while Fed funds sits at 3.88% and markets brace for a heavy week of Fed speaker appearances.
- Trump escalated pressure on the Fed, establishing a committee of inquiry into Governor Lisa Cook, adding a political dimension to this week's policy commentary from Hammack, Waller, Barkin, Collins and Bowman.
Yesterday's Recap
Friday's session was a broad risk-on advance, with the S&P 500 closing within reach of record territory after a 0.59% gain to 7,811.54. The Dow outperformed, rising 0.83% to 51,654.95, while the Nasdaq 100 added 0.51% to 30,883.15 and the Russell 2000 gained 0.46% to 2,806.98. Small-cap participation alongside the mega-cap complex suggested the rally was not narrowly concentrated.
Rates ground higher rather than lower: the 2-year yield rose 5 bp to 4.80% and the 10-year added 2 bp to 5.24%, a modest steepening that signals investors are hedging against a firmer inflation print this week. In currency markets, the dollar softened against the euro with EUR/USD up 0.29% to 1.12, while sterling was essentially flat at 1.32 and USD/JPY held at 158.06. Gold slipped 0.34% to $4,201.80 as real-yield pressure and profit-taking weighed on the metal after its strong run.
WTI crude bucked the softer tone, rallying 1.09% to $92.85. Bitcoin eased 0.38% to $83,358, and the University of Michigan's consumer sentiment deterioration on cost-of-living concerns provided a downbeat macro undertone beneath the equity strength.
The Day Ahead
Monday's calendar is light, with Cleveland Fed President Hammack speaking at 12:50 p.m. ET the sole high-impact event. Tuesday brings a far busier slate: Waller speaks at 3:45 a.m., weekly ADP employment change prints at 8:15 a.m.
following a prior 23,750, and existing home sales at 10 a.m. are expected to hold roughly flat at 3.96 million annualized versus 3.98 million previously. Barkin speaks at 1 p.m., the Monthly Budget Statement follows at 2 p.m.
with the deficit expected to narrow sharply from September's $167 billion, and Collins closes the day at 4 p.m. The week's centerpiece arrives Wednesday with September CPI at 8:30 a.m., where consensus looks for headline inflation of 0.6% month-over-month and core of 0.2%, with the core year-over-year rate seen ticking up to 2.5% from 2.4%. Bowman speaks Wednesday morning as well, and the MBA mortgage rate survey will be scrutinized with 30-year rates at 7.49%.
Page 1
Never miss an issue
Subscribe to US Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.