US Macro Daily(Beta Mode)
Yields Grind Higher; Fed Speakers in Focus
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,807.24 | -0.06% |
| Nasdaq 100 | 30,664.70 | -0.71% |
| Dow Jones | 51,850.55 | +0.38% |
| Russell 2000 | 2,794.48 | -0.45% |
| USD/JPY | 158.10 | +0.02% |
| EUR/USD | 1.12 | -0.22% |
| GBP/USD | 1.32 | +0.10% |
| Gold | 4,204.40 | +0.33% |
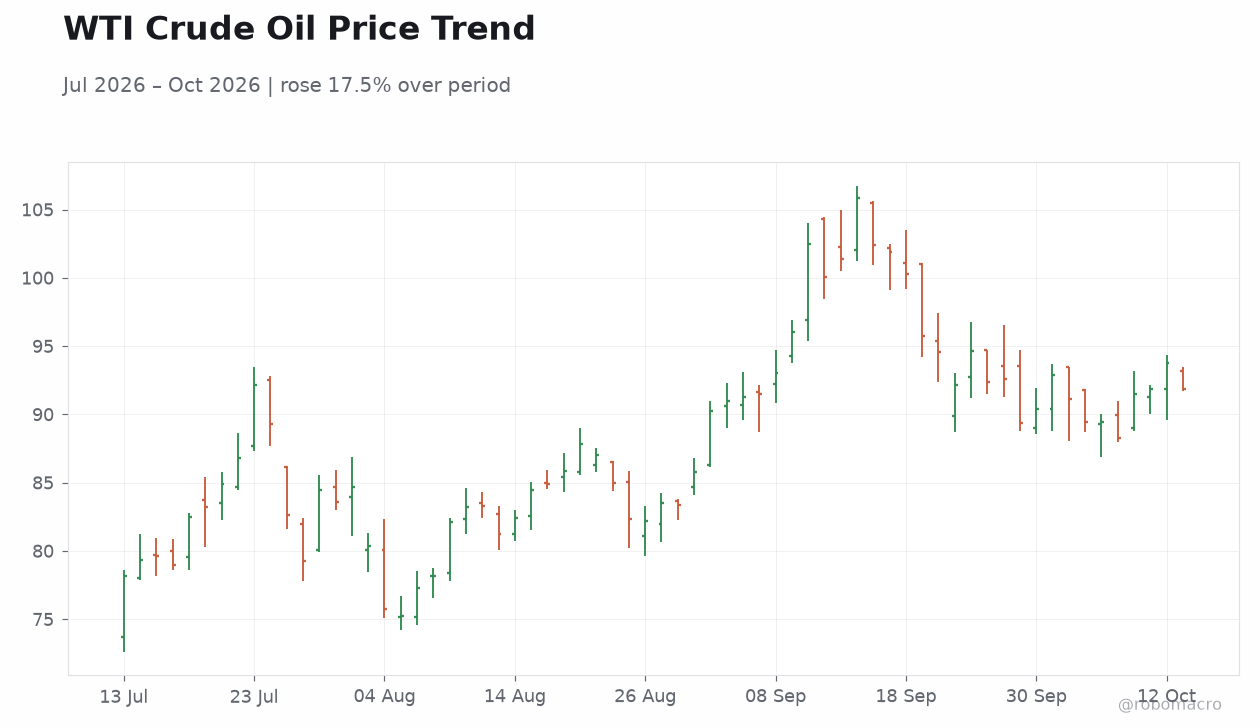
| WTI Crude | 91.84 | -2.03% |
| Bitcoin | 83,144.30 | +1.69% |
| US 2Y Treasury | 4.80% | +5 bp |
| US 10Y Treasury | 5.24% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Fed Hammack Speech | - | - | - |
| Speech by Fed's Waller | - | - | - |
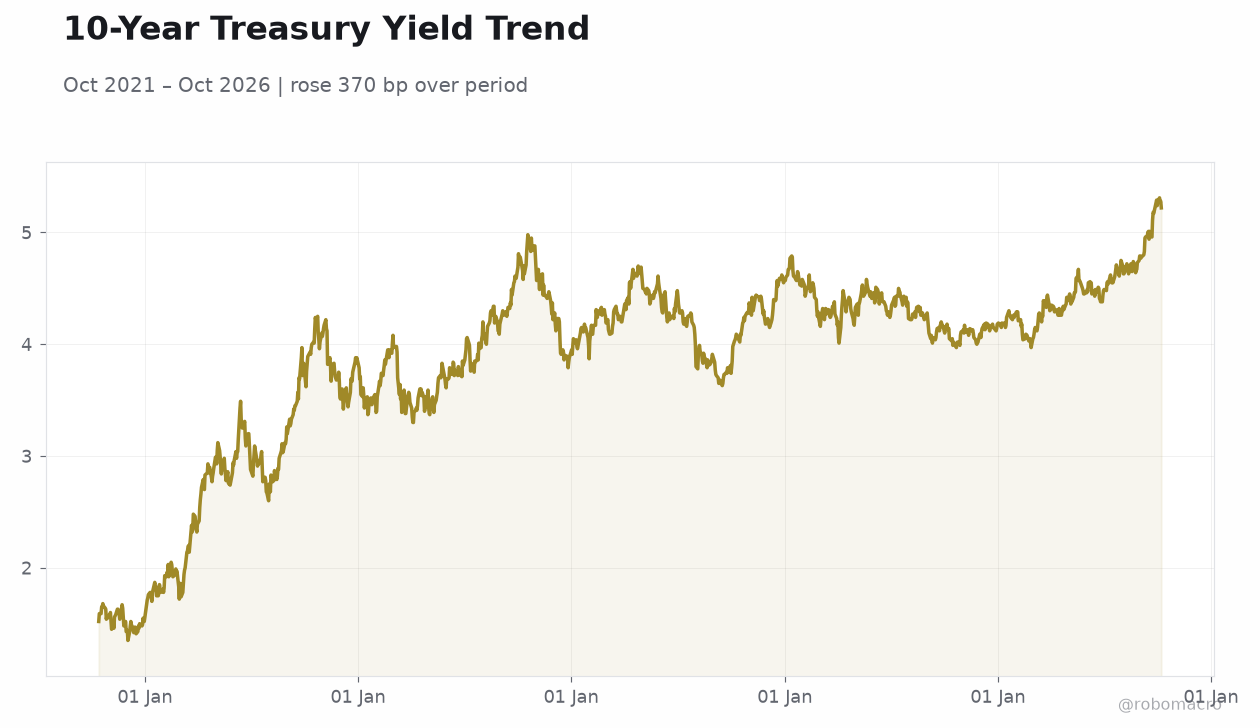 10-Year Treasury Yield Trend | Type: macro_line | 10-Year Treasury Yield (%): 5.22 (2026-10-08) | Range: 1.35–5.31 | Trend(6pt): 1.52,3.49,4.56,4.43,5.28,5.22
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
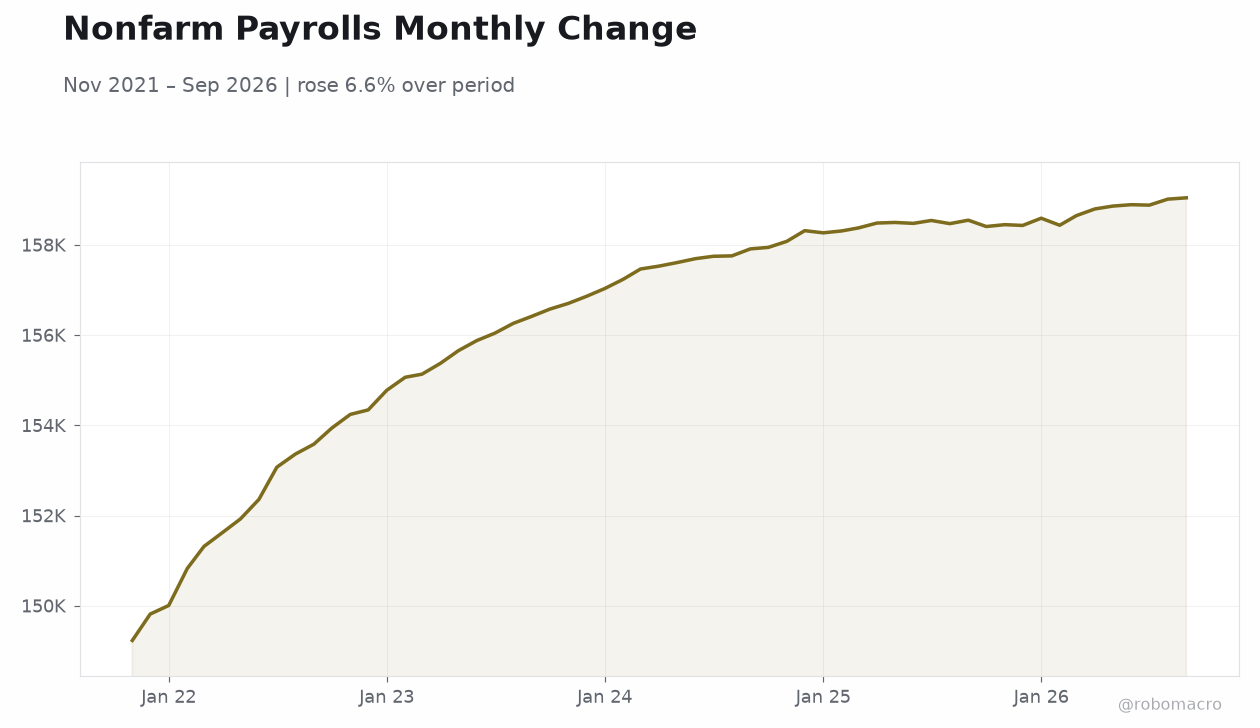
| ADP Employment Change Weekly | 23,750 | - | 08:15 |
| Existing Home Sales | 4.0m | 4.0m | 10:00 |
| Existing Home Sales Month-over-Month | -2 | - | 10:00 |
| Speech by Fed's Barkin | - | - | 13:00 |
| Monthly Budget Statement | -167,000m | -28,000m | 14:00 |
| Speech by Fed's Collins | - | - | 16:00 |
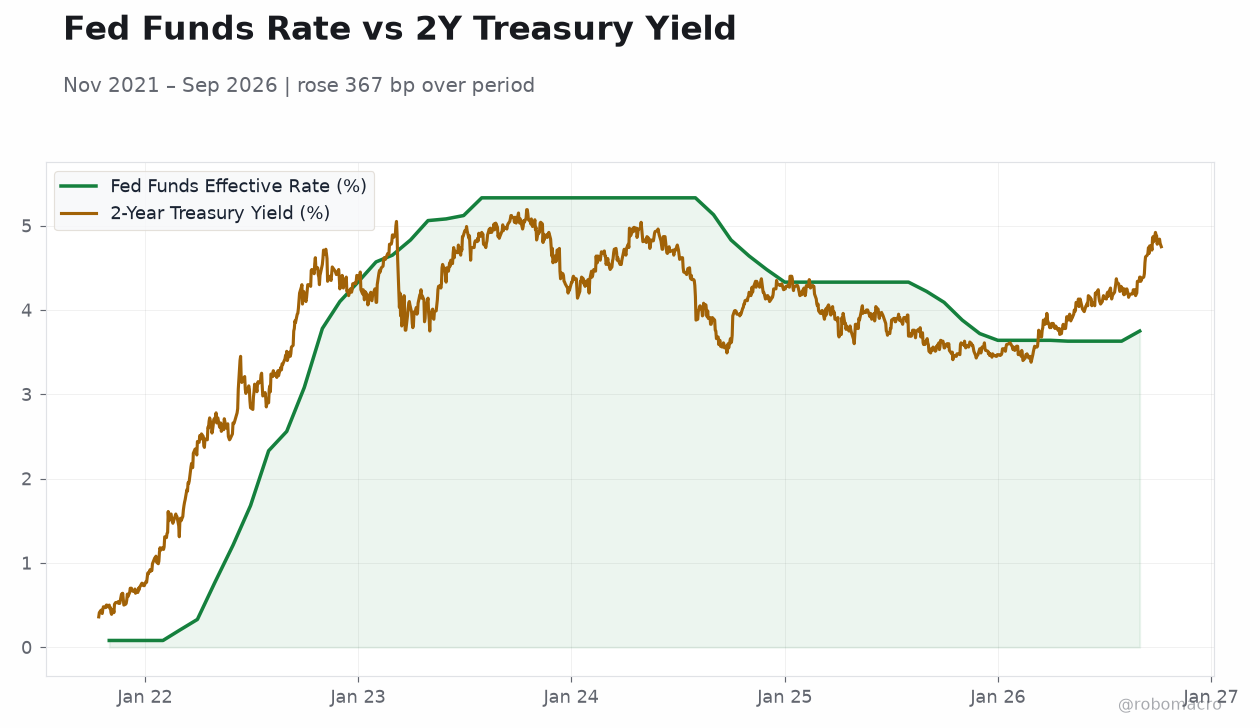
- 10-year Treasury yield rose 2 bp to 5.24% and the 2-year added 5 bp to 4.80% as investors position for a heavy week of Fed commentary and Wednesday's CPI.
- Fed's Hammack described the economy as thriving and backed further rate hikes, while Waller argued higher long yields are doing tightening work for the Fed.
- Today brings ADP weekly employment, Existing Home Sales (cons. 3.96M), the Monthly Budget Statement, and speeches from Barkin and Collins; CPI prints tomorrow.
Yesterday's Recap
Monday's session was a study in rotation rather than direction. The Dow industrials gained 0.38% to 51,850.55, but the Nasdaq 100 slipped 0.71% to 30,664.70 and the S&P 500 edged down 0.06% to 7,807.24, leaving the Russell 2000 0.45% lower at 2,794.48. The mixed tape reflected a market wrestling with elevated rates: the 10-year Treasury yield climbed 2 bp to 5.24% and the 2-year rose 5 bp to 4.80%, steepening the curve modestly as near-term policy expectations firmed.
Crude was the day's big mover, with WTI falling 2.03% to $91.84, while gold advanced 0.33% to $4,204.40. Bitcoin bucked the equity softness, rallying 1.69% to $83,144.30. In FX, the dollar was mixed — EUR/USD eased 0.22% to 1.12 while GBP/USD added 0.10% to 1.32 and USD/JPY held near 158.10.
On the data front, the calendar was light, but Cleveland Fed President Hammack's speech at 12:50 ET dominated the tape, with the regional president citing a thriving economy and endorsing additional tightening.
The Day Ahead
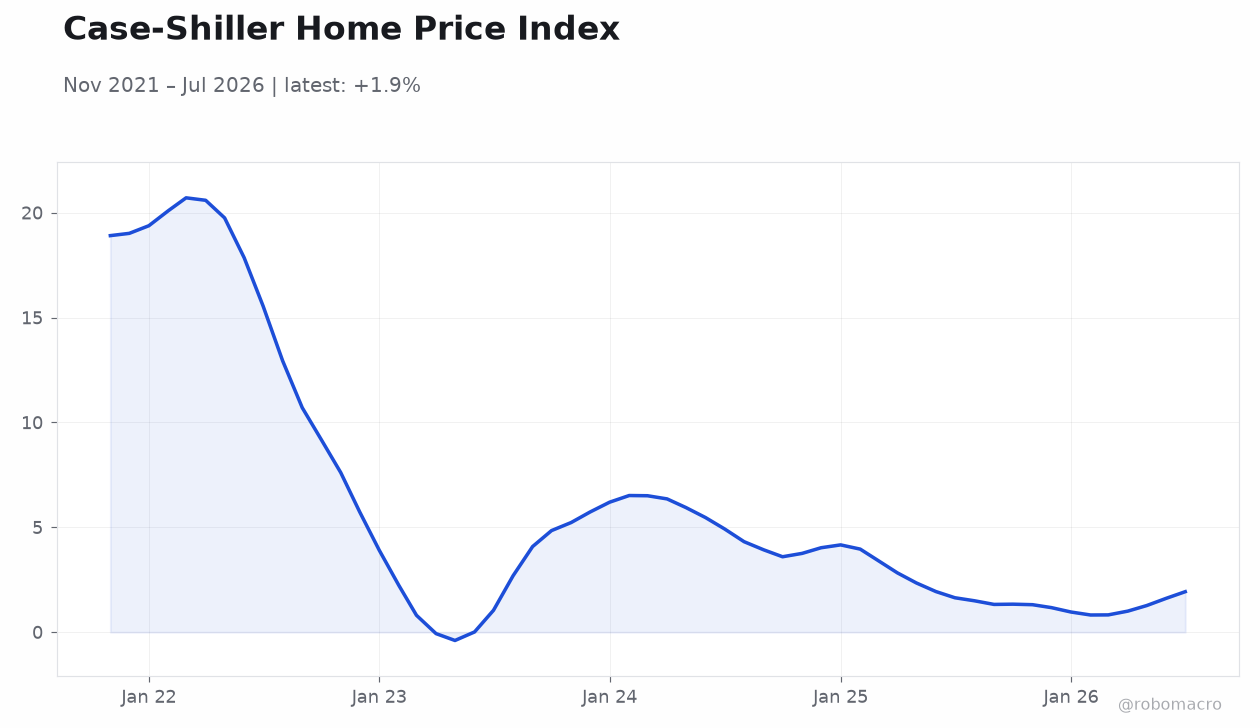
Tuesday's docket opens with the weekly ADP Employment Change at 8:15 ET, a useful pulse on private hiring after last week's 23,750 print. The centerpiece is Existing Home Sales at 10:00 ET, where consensus looks for an annualized pace of 3.96 million, roughly stable versus the prior 3.98 million — a key test of whether housing demand is stabilizing despite mortgage rates near 7.5%. The Treasury's Monthly Budget Statement follows at 14:00 ET, with the deficit expected to narrow sharply from the prior $167 billion shortfall.
The Fed is out in force: Barkin speaks at 13:00 ET and Collins at 16:00 ET, offering investors further color on the rate path. Tomorrow's calendar is even heavier, headlined by CPI at 8:30 ET, where headline inflation is seen accelerating to 3.7% year-over-year from 3.4%, with core holding near 2.5%.
Other Economic Notes
The housing market remains the economy's pressure point, with existing sales stuck below 4 million annualized and the MBA 30-year rate at 7.49% as of last Thursday's survey — levels that continue to lock in existing owners and suppress turnover. ↓ p.2