CPI in Focus as Yields Ease, Chips Slide
24,750 ADP Employment Change4.0m Existing Home Sales1.50 Existing Home Sales
S&P 5007,805.45-0.02%
US 10Y Treasury5.21%-3 bp
WTI Crude95.29+1.22%
Gold4,167.00-0.25%
Market Snapshot
| Asset | Level | Change |
|---|
| S&P 500 | 7,805.45 | -0.02% |
| Nasdaq 100 | 30,569.48 | -0.31% |
| Dow Jones | 51,670.10 | -0.35% |
| Russell 2000 | 2,783.37 | -0.40% |
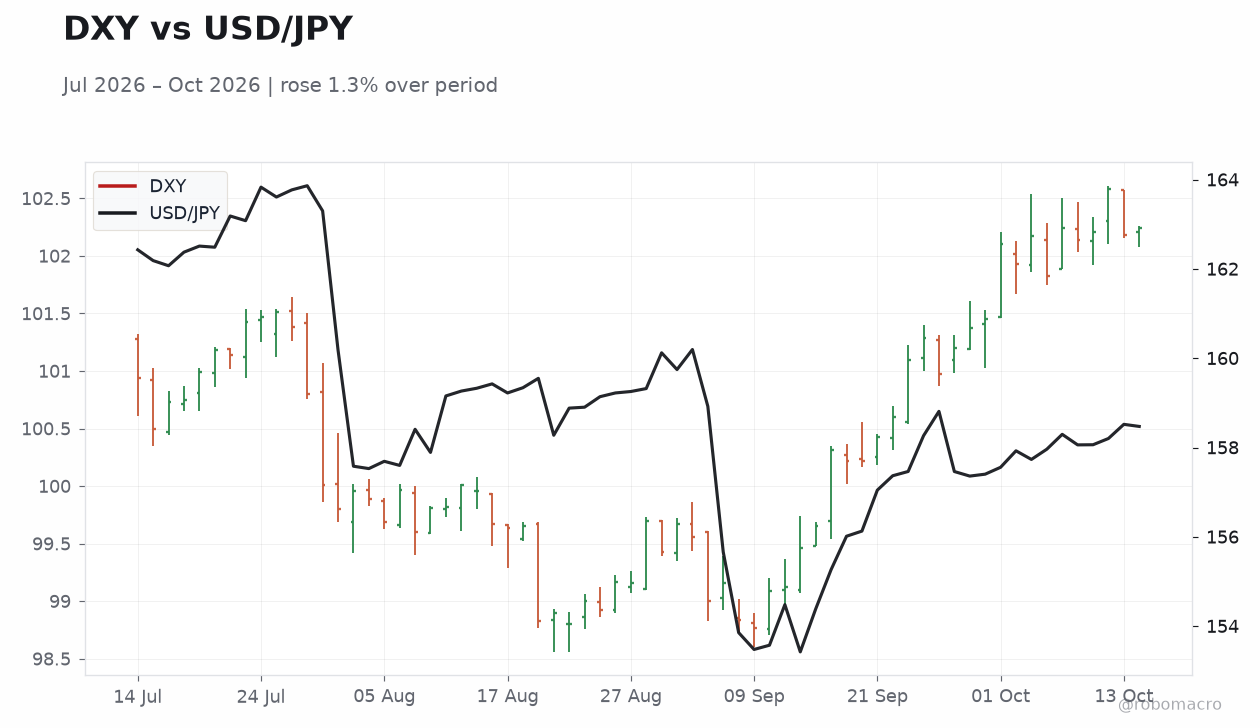
| USD/JPY | 158.43 | -0.06% |
| EUR/USD | 1.12 | +0.30% |
| GBP/USD | 1.33 | +0.42% |
| Gold | 4,167.00 | -0.25% |
| WTI Crude | 95.29 | +1.22% |
| Bitcoin | 83,324.72 | +0.28% |
| US 2Y Treasury | 4.79% | -1 bp |
| US 10Y Treasury | 5.21% | -3 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| Fed Hammack Speech | - | - | - |
| Speech by Fed's Waller | - | - | - |
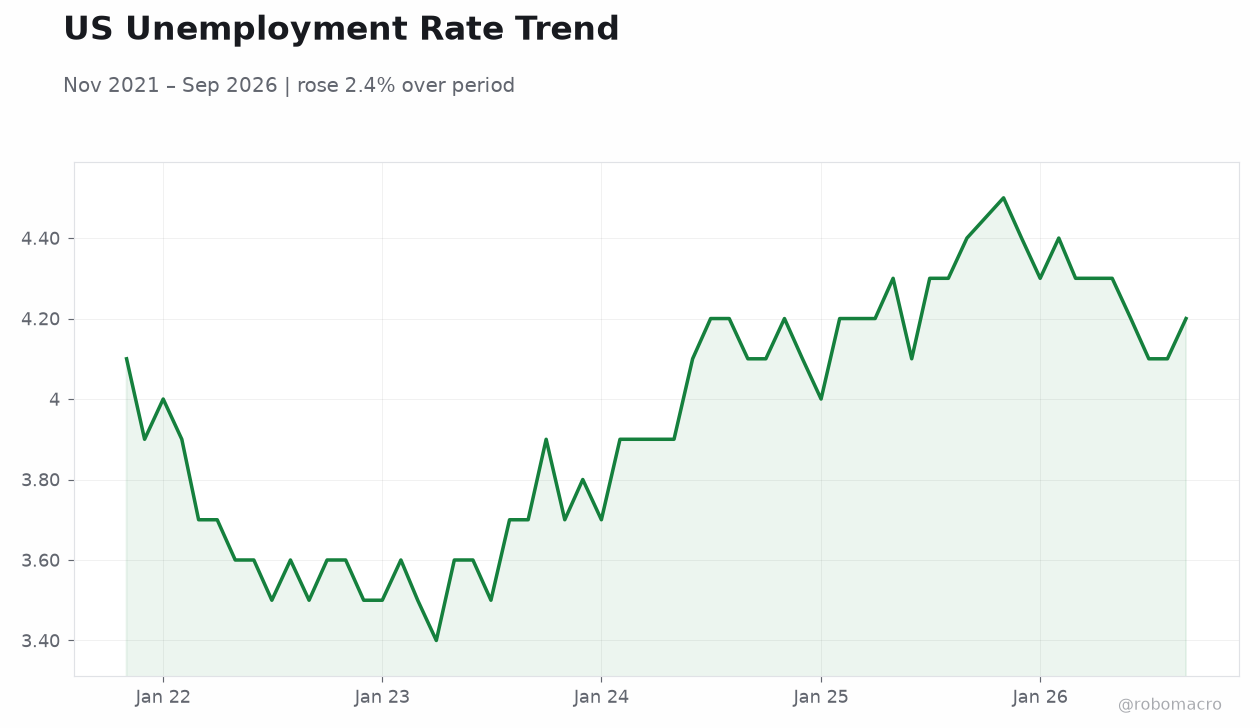
| ADP Employment Change Weekly | 23,750 | - | 24,750 |
| Existing Home Sales | 3.9m | 4.0m | 4.0m |
| Existing Home Sales Month-over-Month | -3.20 | - | 1.50 |
| Speech by Fed's Barkin | - | - | - |
| Monthly Budget Statement | -167,000m | -29,000m | - |
| Speech by Fed's Collins | - | - | - |
| Speech by Fed's Bowman | - | - | - |
| MBA 30-Year Mortgage Rate | 7.49 | - | - |
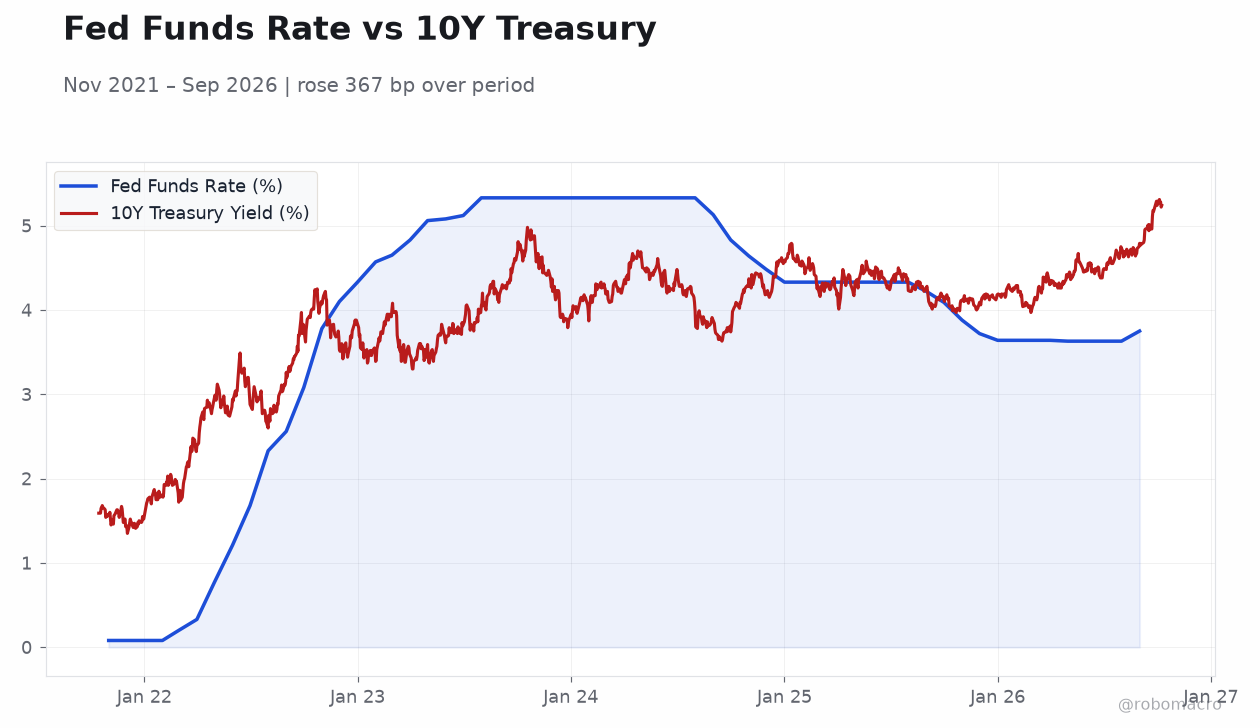
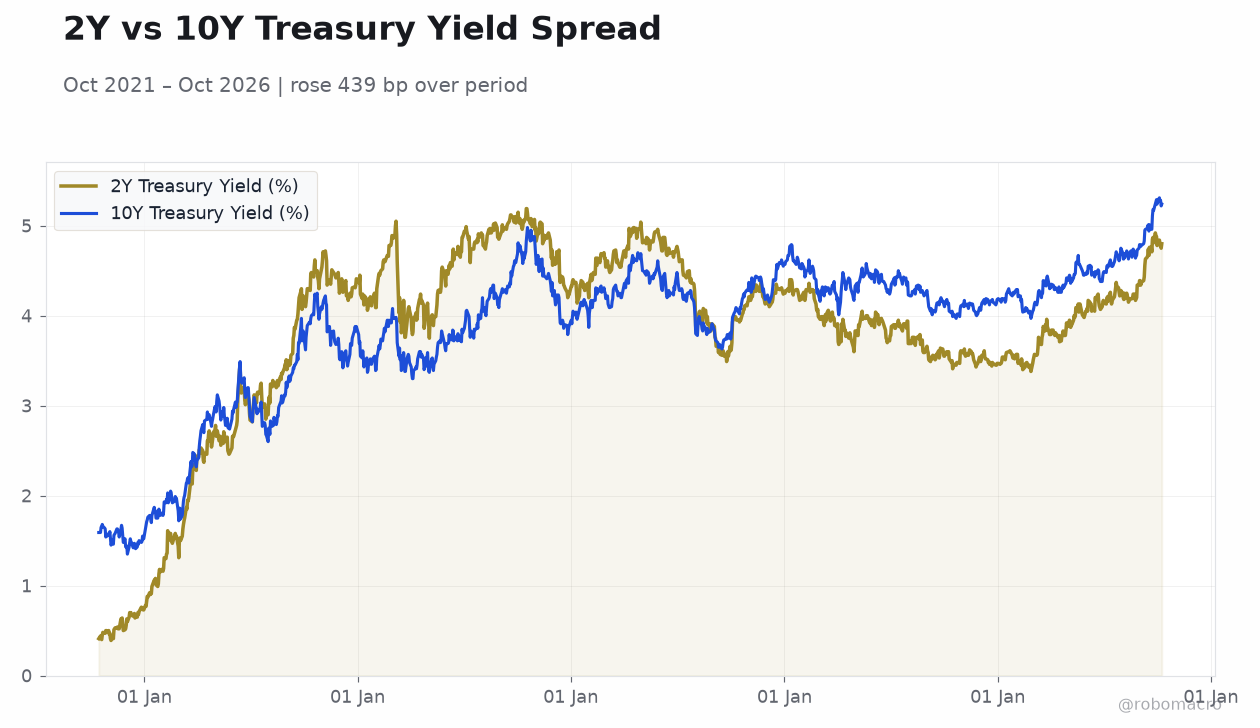 2Y vs 10Y Treasury Yield Spread | Type: macro_line | 2Y Treasury Yield (%): 4.8 (2026-10-09) | Range: 0.39–5.19 | Trend(6pt): 0.41,4.18,4.88,3.9,4.75,4.8 | 10Y Treasury Yield (%): 5.24 (2026-10-09) | Range: 1.35–5.31 | Trend(6pt): 1.59,3.53,4.5,4.43,5.22,5.24
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| Core Inflation Rate Month-over-Month | 0.30 | 0.20 | 08:30 |
| Core Inflation Rate Year-over-Year | 2.40 | 2.50 | 08:30 |
| Inflation Rate Month-over-Month | 0.40 | 0.60 | 08:30 |
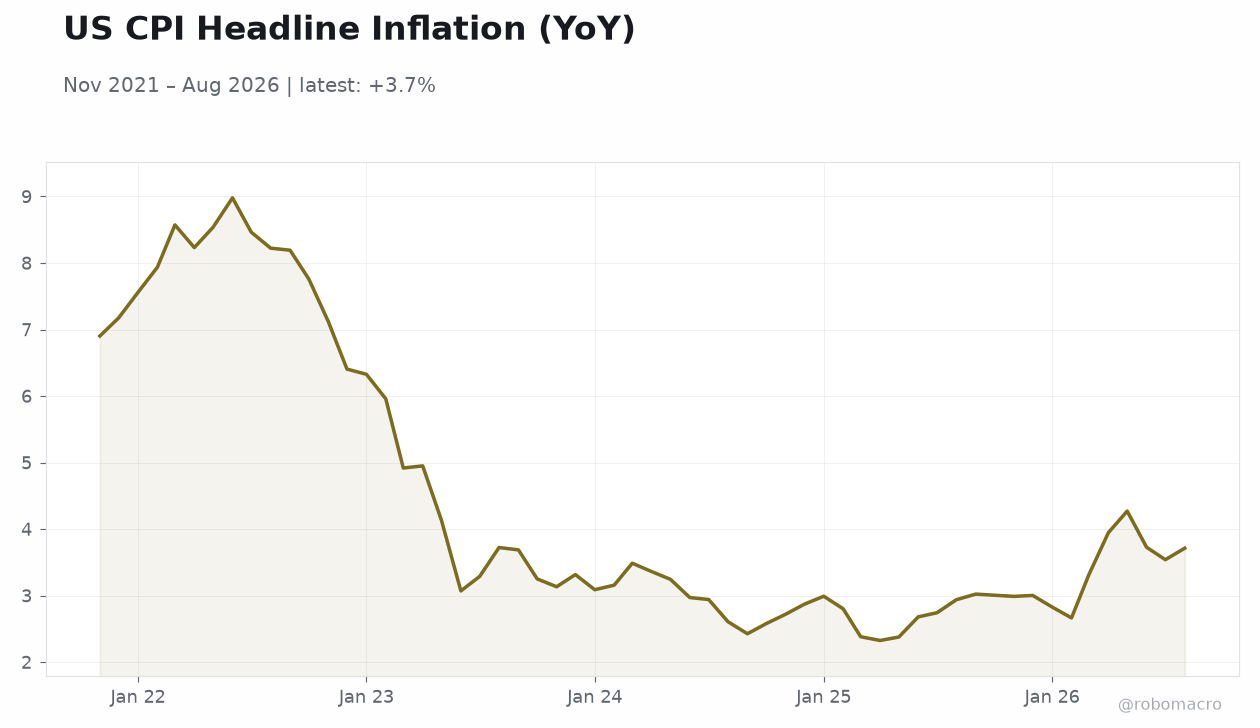
| Inflation Rate Year-over-Year | 3.40 | 3.60 | 08:30 |
| CPI s.a | 334.13 | - | 08:30 |
| Consumer Price Index | 334.98 | 336.65 | 08:30 |
| Speech by Fed's Barkin | - | - | 13:30 |
| API Weekly Crude Oil Stocks | -2.1m | - | 16:30 |
| Speech by Fed's Bowman | - | - | 22:55 |
- Headline and core CPI due 8:30am ET; consensus sees headline at 0.6% m/m and 3.6% y/y, core at 0.2% m/m and 2.5% y/y
- Treasuries firmed Tuesday, the 10-year easing 3 bp to 5.21% and the 2-year down 1 bp to 4.79%, while equities closed modestly lower
- Existing home sales beat in September at 3.99 million annualized, up 1.5% m/m, offering a rare bright for housing
Yesterday's Recap
US markets closed slightly softer on Tuesday as investors positioned ahead of Wednesday's CPI release. The S&P 500 slipped 0.02% to 7,805.45, the Nasdaq 100 lost 0.31% to 30,569.48, and the Dow fell 0.35% to 51,670.10, with the Russell 2000 lagging at -0.40% as small caps absorbed a continuing chipmaker selloff. Semiconductors extended their decline for a second session, pressuring tech-heavy indices before major bank earnings begin later this week.
The Treasury curve bull-steepened modestly: the 10-year yield eased 3 bp to 5.21% and the 2-year dipped 1 bp to 4.79%, narrowing the 2s10s spread to 42 bp. In data, existing home sales rose to a 3.99 million annualized pace, beating the 3.95 million consensus and rebounding 1.5% m/m from August's 3.93 million print — a notable recovery given mortgage rates near 7.49%. ADP's weekly employment change showed private payrolls expanding by 24,750, marginally above the prior week's 23,750, suggesting labor demand remains positive but decelerating.
The monthly budget statement was scheduled for 2pm, with the prior month showing a $167 billion deficit against a much smaller expected shortfall. Fed speakers were active: Hammack, Waller, Barkin, and Collins all took the podium, while Bowman speaks early Wednesday. Gold slipped 0.25% to $4,167 as the dollar's retreat — EUR/USD up 0.30% to 1.12 and GBP/USD gaining 0.42% to 1.33 — failed to spark safe-haven demand.
WTI crude jumped 1.22% to $95.29, and Bitcoin added 0.28% to $83,325.
The Day Ahead
The centerpiece is September CPI at 8:30am ET, with headline inflation expected at 0.6% m/m and 3.6% y/y, accelerating from August's 3.4% pace. Core CPI is forecast at 0.2% m/m and 2.5% y/y, up from 2.4% previously — a softer core print would reinforce the disinflation narrative and support expectations for continued Fed easing from the current 3.88% funds rate. The seasonally adjusted CPI index level will also be published, with the prior reading at 334.131.
MBA mortgage application data follows at 7am, where the 30-year rate held at 7.49% last week; any renewed rise would test the housing recovery signaled by Tuesday's existing home sales beat. Fed Governor Bowman speaks at 5:40am ET, offering a final pre-CPI signal on the policy path. ↓ p.2
Page 1
Never miss an issue
Subscribe to US Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.