US Macro Daily(Beta Mode)
Risk Rally Meets Sticky Yields as Fed Pause Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,757.17 | +0.58% |
| Nasdaq 100 | 29,822.52 | +1.13% |
| Dow Jones | 52,856.09 | +0.69% |
| Russell 2000 | 2,781.02 | +0.27% |
| USD/JPY | 156.84 | -0.90% |
| EUR/USD | 1.12 | -0.09% |
| GBP/USD | 1.34 | +0.03% |
| Gold | 4,098.20 | -1.25% |
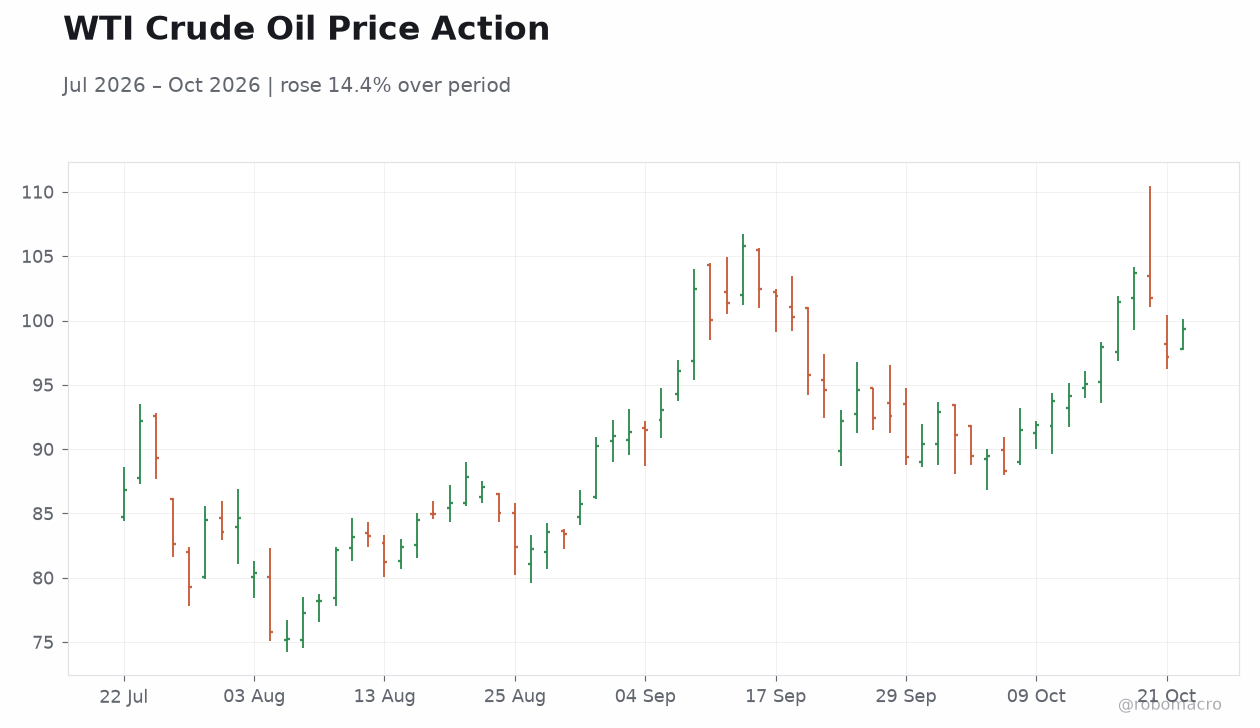
| WTI Crude | 99.23 | +2.14% |
| Bitcoin | 81,923.57 | -2.49% |
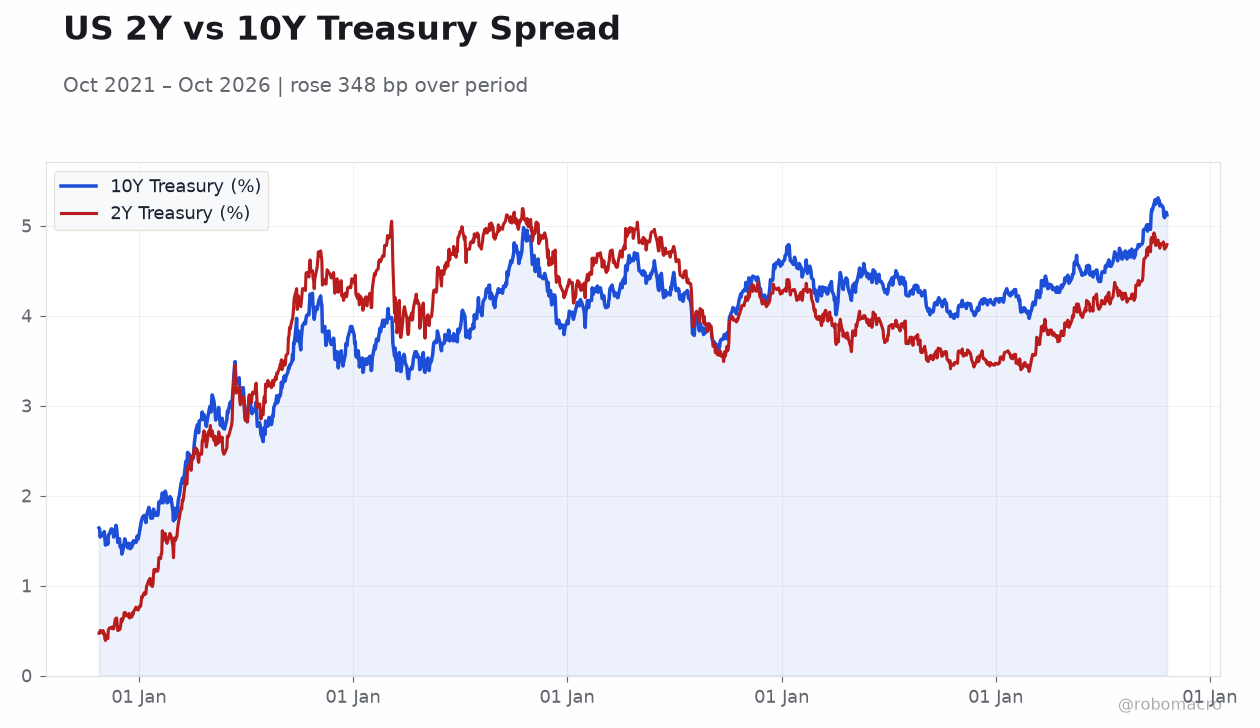
| US 2Y Treasury | 4.81% | +2 bp |
| US 10Y Treasury | 5.13% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
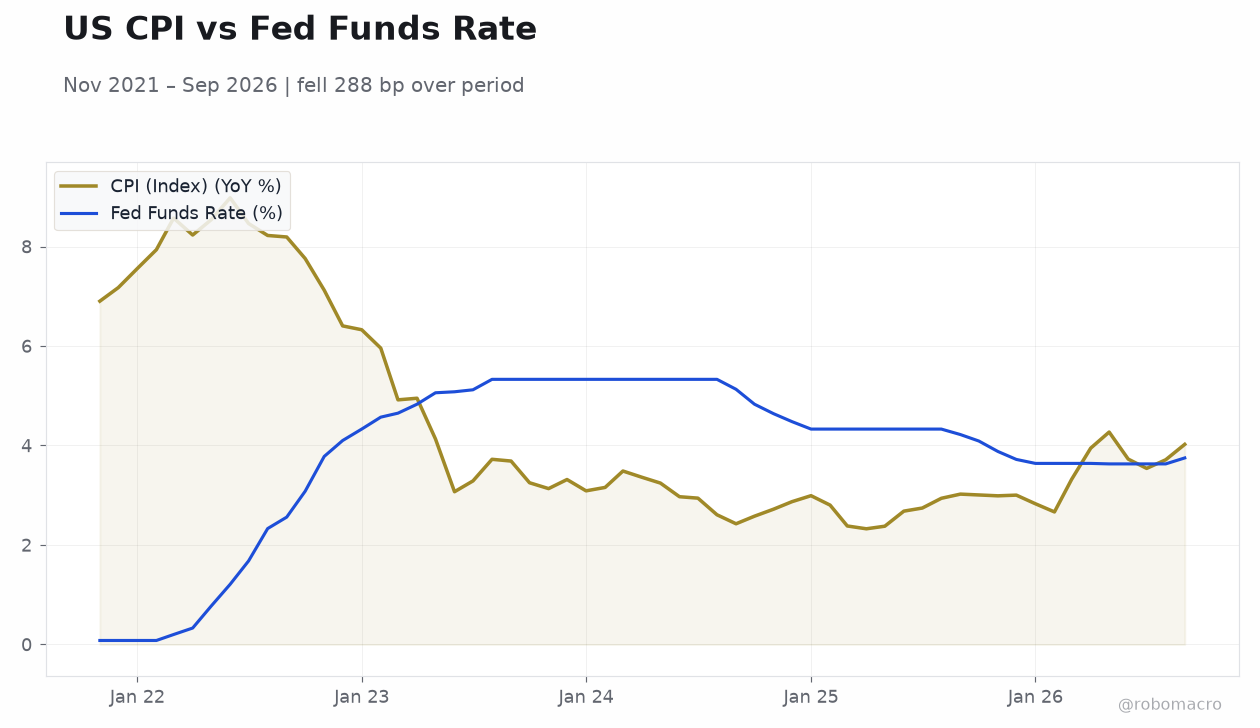 US CPI vs Fed Funds Rate | Type: macro_line | CPI (Index): 4.023 (2026-09-01) | Range: 2.325–8.979 | Trend(6pt): 6.902,6.327,3.487,2.377,3.713,4.023 | Fed Funds Rate (%): 3.75 (2026-09-01) | Range: 0.08–5.33 | Trend(6pt): 0.08,4.33,5.33,4.33,3.63,3.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Equities rallied broadly (S&P 500 +0.58%, Nasdaq 100 +1.13%) while gold fell 1.25% and Bitcoin dropped 2.49%, signaling a rotation out of hedges into risk.
- Treasury yields edged higher (2Y 4.81%, +2 bp; 10Y 5.13%, +1 bp), keeping the curve steep and rate-sensitive sectors under pressure.
- WTI crude jumped 2.14% to $99.23 on supply concerns, complicating the disinflation narrative as the Fed weighs its next move.
Yesterday's Recap
US equities posted a broad risk-on session Wednesday, with the S&P 500 gaining 0.58% to 7,757.17 and the Nasdaq 100 outperforming at +1.13%, while the Dow added 0.69% and the Russell 2000 lagged at +0.27%. The move came despite Treasury yields grinding higher, with the 2-year up 2 bp to 4.81% and the 10-year up 1 bp to 5.13%, leaving the curve steep and real yields elevated. Safe-haven and speculative assets diverged sharply from equities: gold fell 1.25% to $4,098.20 and Bitcoin slid 2.49% to $81,923.57, suggesting profit-taking rather than a broad de-risking.
In FX, USD/JPY dropped 0.90% to 156.84 while EUR/USD slipped 0.09% to 1.12 and GBP/USD was roughly flat at 1.34, a mixed dollar picture consistent with Fed pause speculation. Energy was the standout commodity mover, with WTI crude surging 2.14% to $99.23, keeping headline inflation risk alive. No major US data releases were logged for the session, so price action reflected positioning and rate expectations rather than fresh macro prints.
The Day Ahead
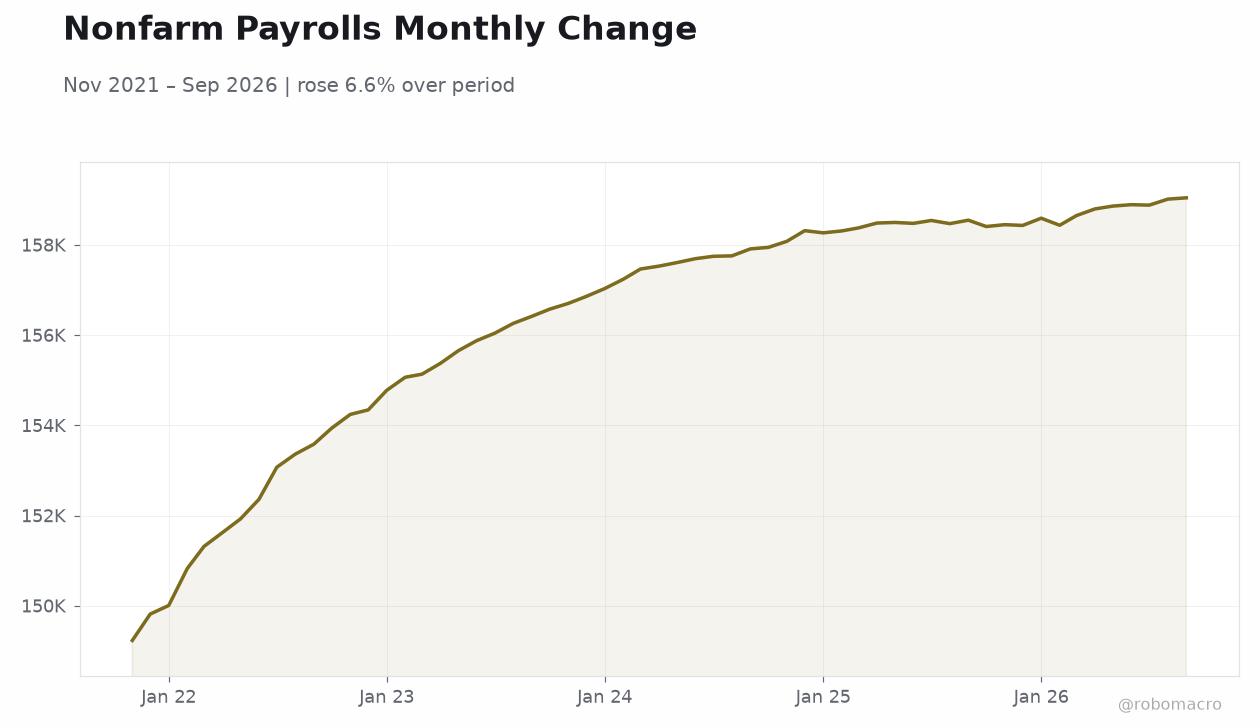
The US calendar is light Thursday, with no top-tier releases scheduled, leaving markets to trade off positioning and Fed communication. Attention will center on any Fed speakers and the tone of rate expectations following recent soft labor data. Housing-related sentiment remains a live theme, with recent data weakening as borrowing costs stay elevated.
Traders will also watch the 10-year auction cycle and dealer positioning given the 5.13% yield level. With WTI near $99, energy-driven inflation risk stays on the radar for both equities and rates.
Other Economic Notes
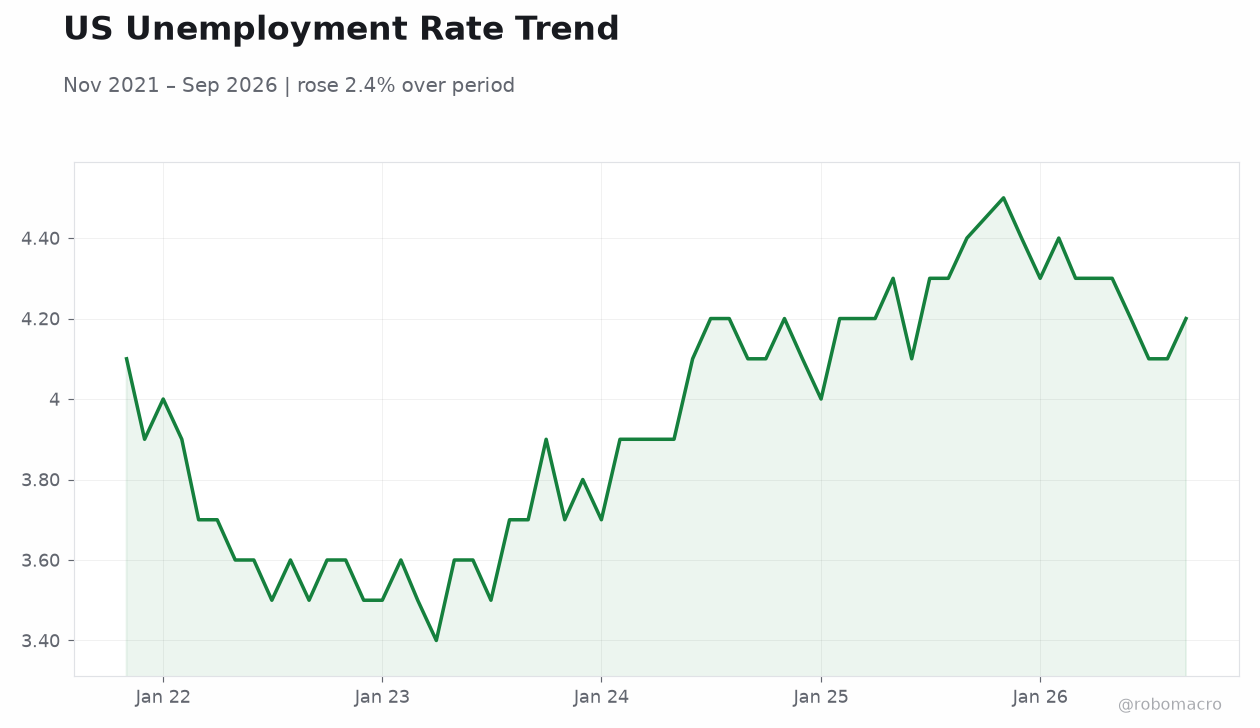
The macro backdrop remains one of sticky inflation and slowing momentum: CPI at 3.70% YoY sits well above target while GDP growth has cooled to 2.20% QoQ SAAR. Retail sales growth of 6.29% YoY shows the consumer is still spending, but housing data have weakened again as mortgage costs bite. Unemployment at 4.20% is consistent with a labor market that is softening but not collapsing, which keeps the Fed's dual mandate in tension.
↓ p.2