US Macro Daily(Beta Mode)
Yields Plunge on Fed Pause Bets, Tech Rout
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,663.43 | -1.21% |
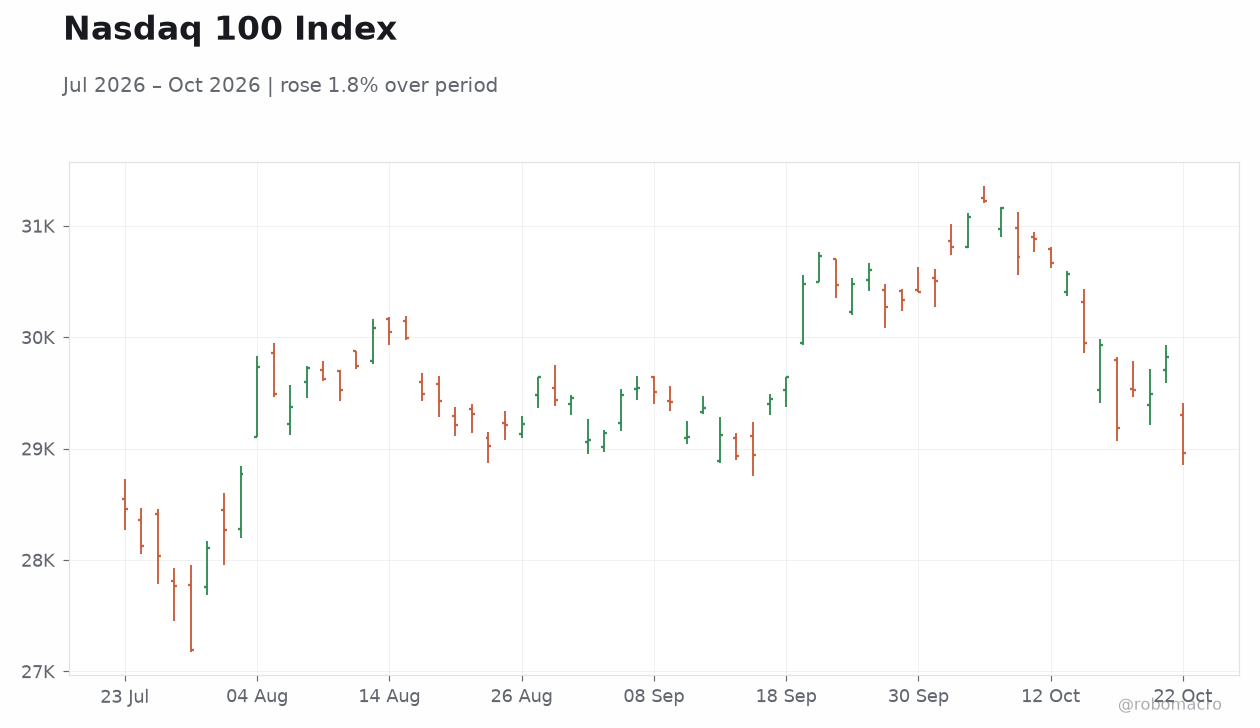
| Nasdaq 100 | 28,958.69 | -2.90% |
| Dow Jones | 52,867.98 | +0.02% |
| Russell 2000 | 2,784.03 | +0.11% |
| USD/JPY | 156.82 | -0.83% |
| EUR/USD | 1.12 | -0.32% |
| GBP/USD | 1.34 | -0.16% |
| Gold | 4,038.00 | -0.55% |
| WTI Crude | 101.02 | +1.56% |
| Bitcoin | 81,478.48 | +0.20% |
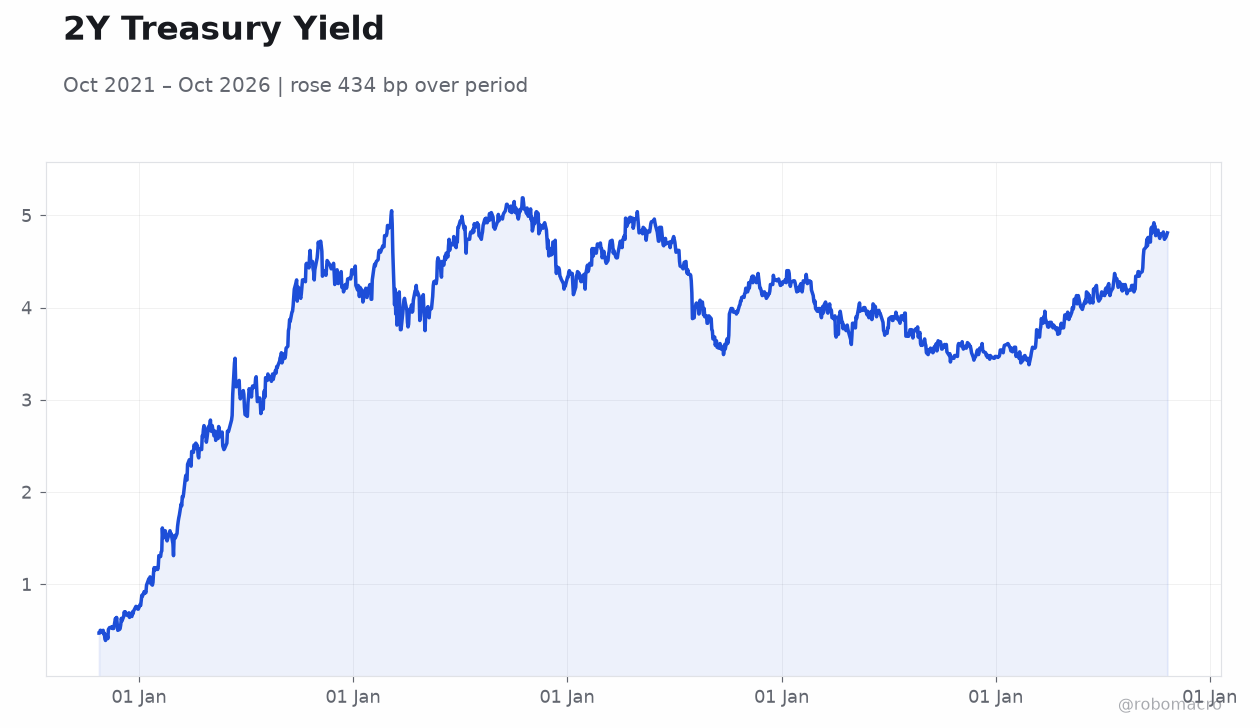
| US 2Y Treasury | 4.65% | -16 bp |
| US 10Y Treasury | 4.96% | -17 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
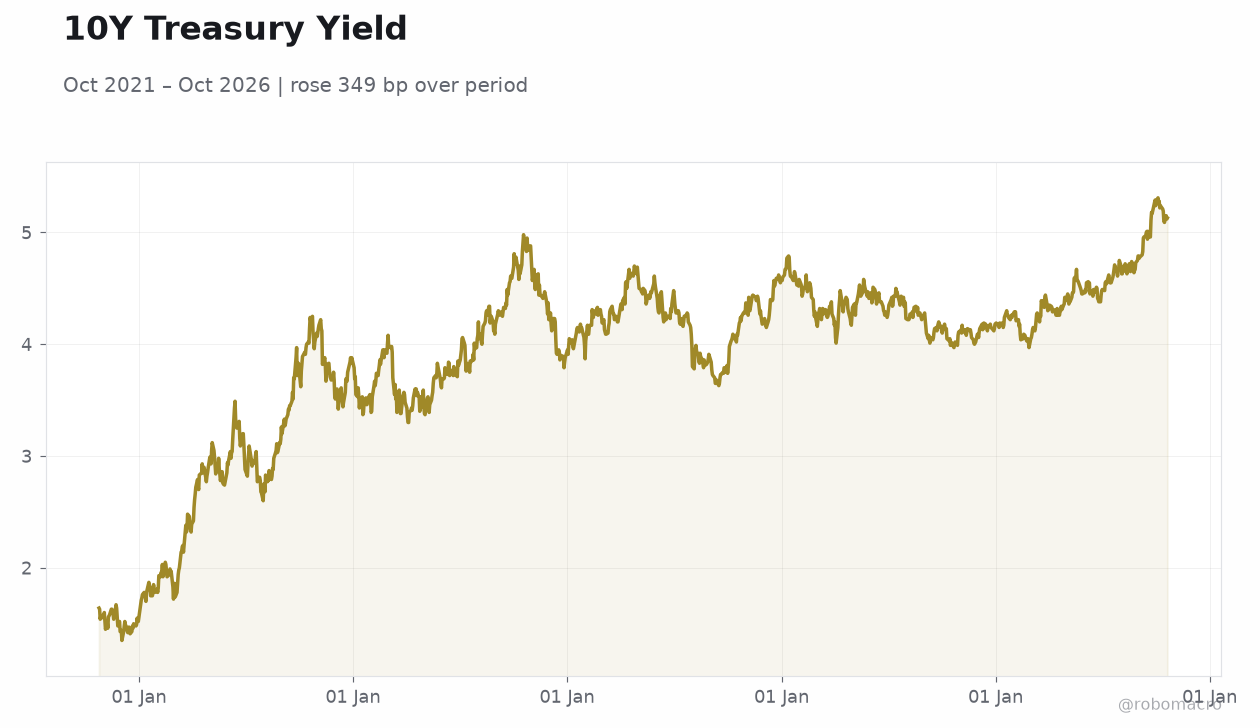 10Y Treasury Yield | Type: macro_line | Percent: 5.13 (2026-10-21) | Range: 1.35–5.31 | Trend(6pt): 1.64,3.46,4.62,4.35,5.15,5.13
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
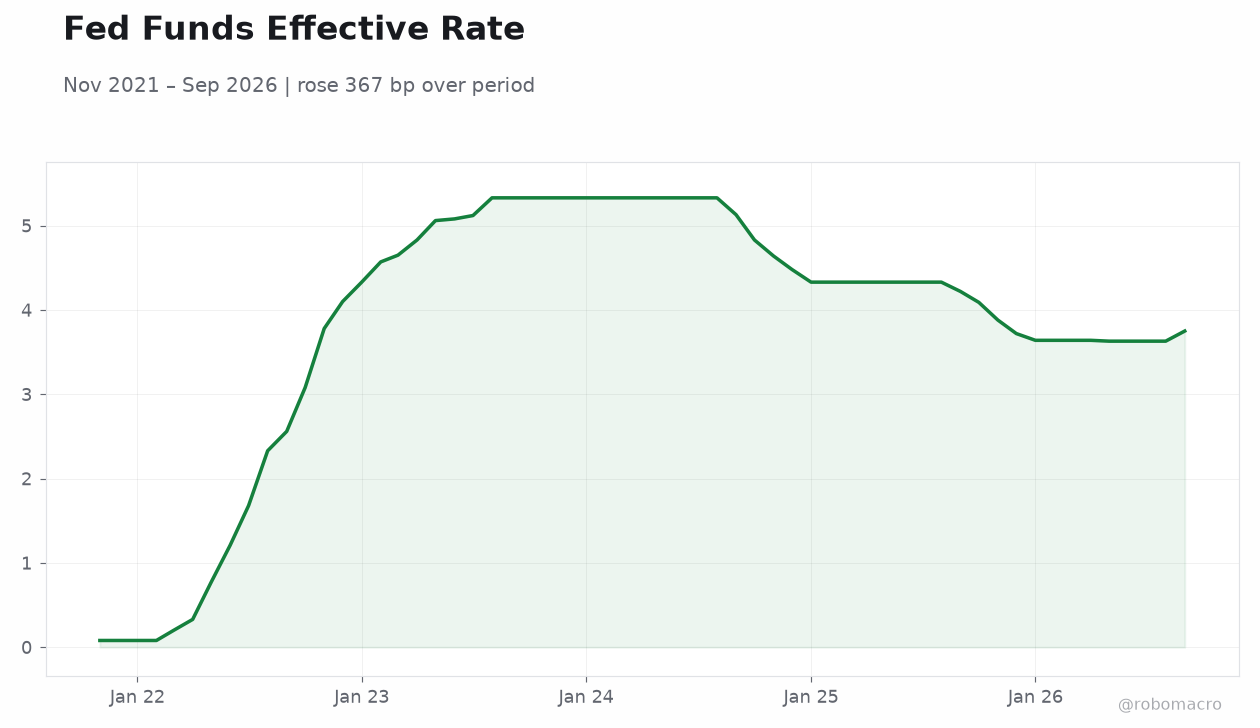
- Treasury yields fell sharply as markets priced higher odds of Fed holding rates steady.
- Equities declined with Nasdaq 100 dropping 2.90% on renewed AI valuation concerns.
- Dollar weakened toward 101.50 on the index amid softer rate-hike expectations.
Yesterday's Recap
Equity markets closed mixed to lower on October 22 as technology shares led a broad selloff. The S&P 500 declined 1.21% to 7,663.43 while the Nasdaq 100 fell 2.90% to 28,958.69 on revived doubts about artificial-intelligence spending returns. The Dow Jones edged up 0.02% to 52,867.98 and the Russell 2000 gained 0.11%.
Treasury yields dropped sharply, with the 2-year yield easing 16 basis points to 4.65% and the 10-year yield falling 17 basis points to 4.96%. The dollar index moved lower near 101.50 on increased bets that the Federal Reserve will pause further tightening. Gold slipped 0.55% to $4,038 while WTI crude rose 1.56% to $101.02.
Bitcoin held steady with a modest 0.20% gain. EUR/USD eased 0.32% to 1.12 and GBP/USD declined 0.16% to 1.34, while USD/JPY fell 0.83% to 156.82.
The Day Ahead
Attention turns to political developments ahead of the November midterms, with investors monitoring potential shifts in fiscal policy. No major economic data releases are scheduled for October 23. Market participants will watch for any additional Federal Reserve speakers who could clarify the path of policy after recent inflation forecasts.
Treasury trading is expected to remain sensitive to positioning ahead of month-end flows. Equity volatility may stay elevated given ongoing questions around technology earnings sustainability. Cross-asset flows could intensify if political headlines alter expectations for post-election spending or tax measures.
Other Economic Notes
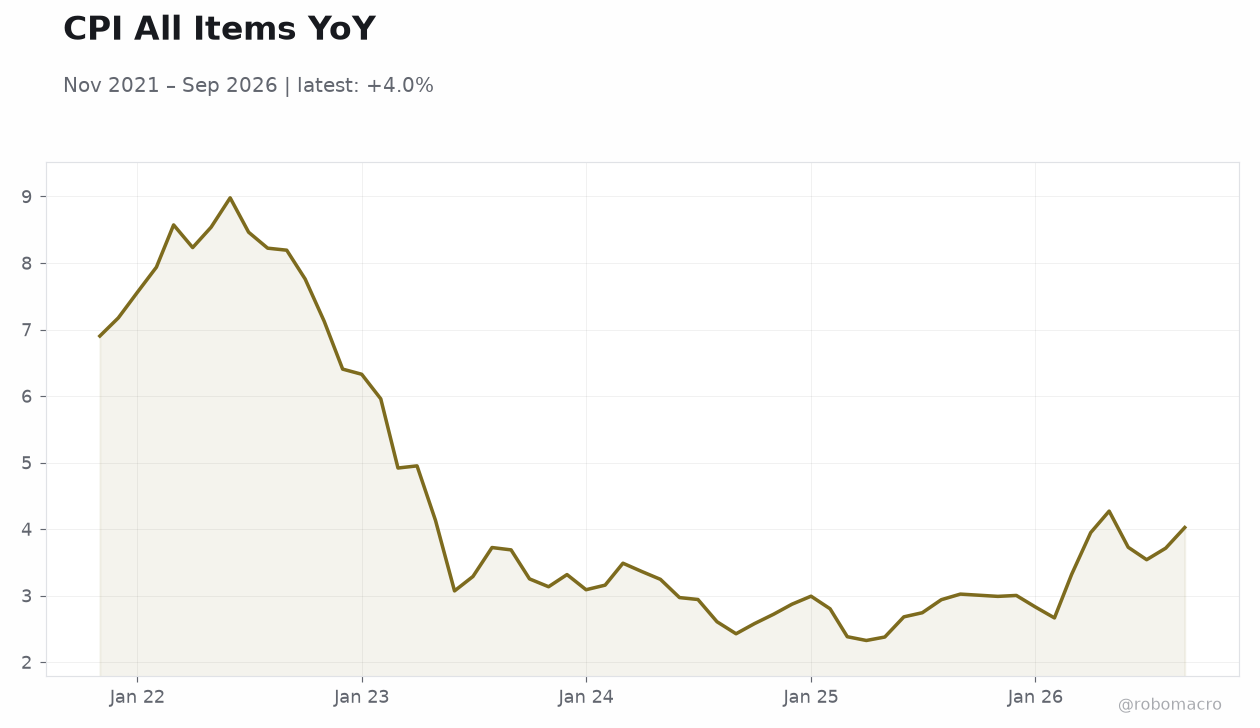
Persistent inflation at 3.70% year-over-year continues to complicate the Federal Reserve’s reaction function despite GDP growth holding near 2.2%. Retail sales running at 6.29% year-over-year signal resilient consumer demand that could keep price pressures elevated. Unemployment at 4.2% remains low enough to support arguments for caution on further easing.
Markets are balancing these data points against political uncertainty that could alter the fiscal backdrop after the elections. The combination of steady growth and sticky prices leaves little room for aggressive policy shifts without clearer signals on both fronts.