US Macro Daily(Beta Mode)
Equities Slip as Yields Climb Ahead of Fed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
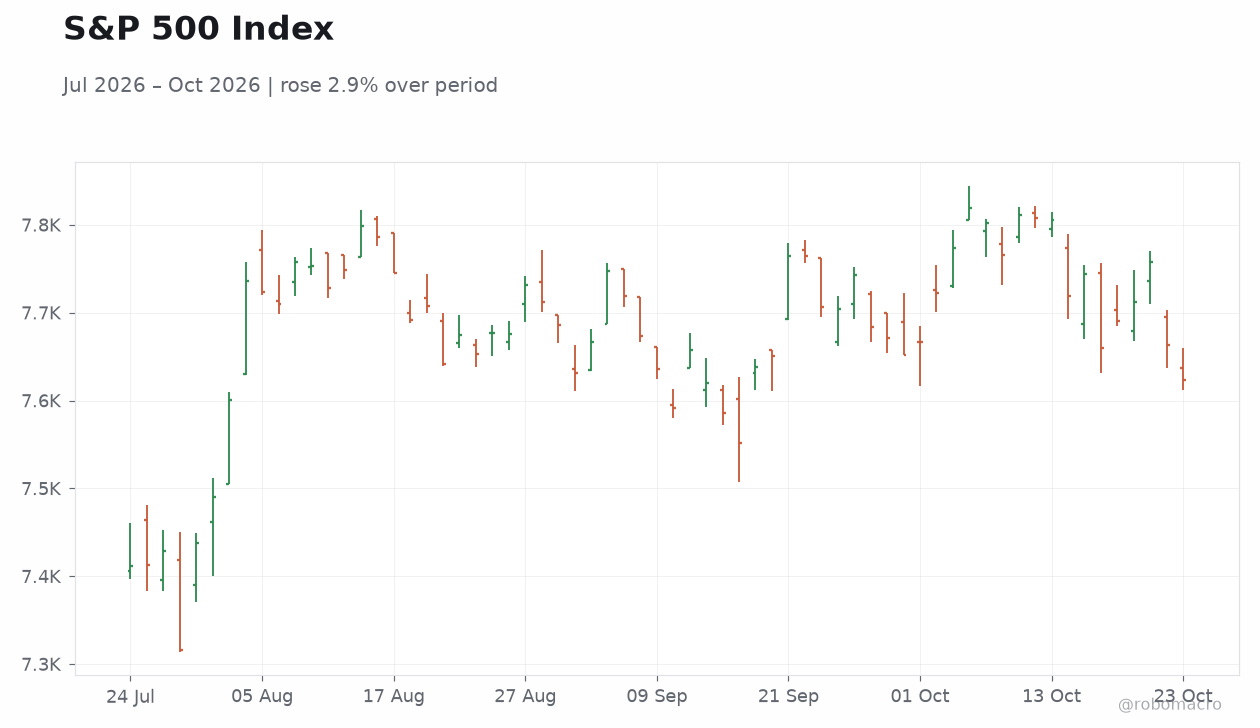
| S&P 500 | 7,623.68 | -0.52% |
| Nasdaq 100 | 28,957.53 | -0.00% |
| Dow Jones | 52,215.16 | -1.23% |
| Russell 2000 | 2,775.90 | -0.29% |
| USD/JPY | 157.35 | +0.55% |
| EUR/USD | 1.12 | -0.20% |
| GBP/USD | 1.33 | -0.41% |
| Gold | 4,024.40 | +0.41% |
| WTI Crude | 101.02 | -2.18% |
| Bitcoin | 80,216.06 | +0.24% |
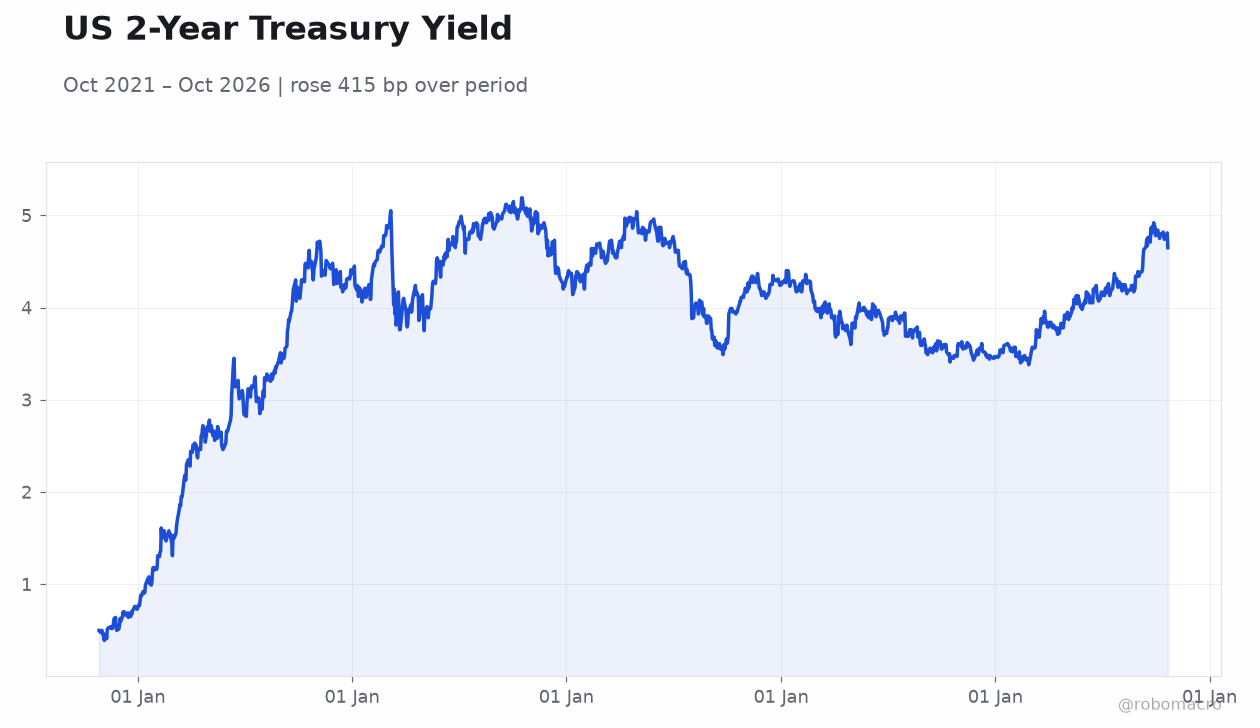
| US 2Y Treasury | 4.69% | +4 bp |
| US 10Y Treasury | 5.00% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
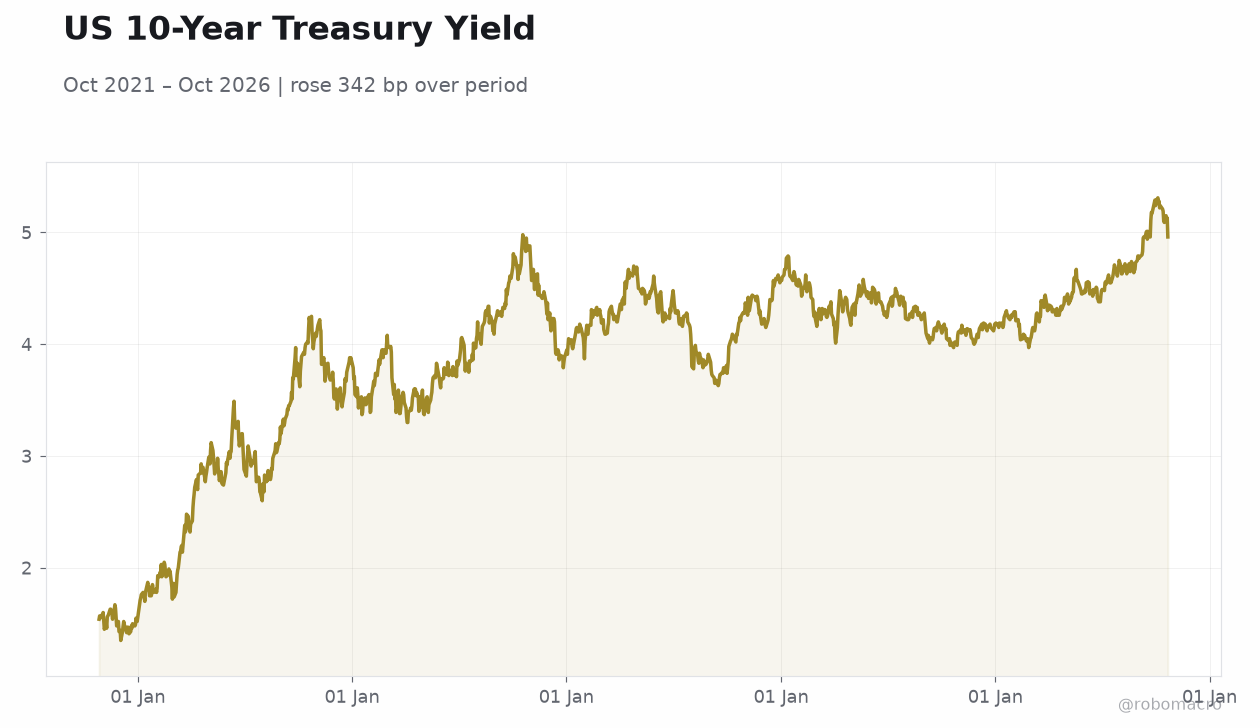 US 10-Year Treasury Yield | Type: macro_line | Yield %: 4.96 (2026-10-22) | Range: 1.35–5.31 | Trend(6pt): 1.54,3.52,4.65,4.43,5.13,4.96
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Chicago Fed National Activity Index | -0.04 | - | 08:30 |
| Dallas Fed Manufacturing Index | 9.80 | - | 10:30 |
| Tuesday (2026-10-27) | |||
| Building Permits Month-over-Month Final | -2.10 | -0.20 | 08:00 |
| ADP Employment Change Weekly | 18,500 | - | 08:15 |
| Durable Goods Orders Month-over-Month | 0 | 0.60 | 08:30 |
| Durable Goods Orders Ex Transp Month-over-Month | 0.30 | 0.60 | 08:30 |
| S&P/Case-Shiller Home Price Year-over-Year | 2.50 | 2.60 | 09:00 |
| Cb Consumer Confidence | 81.90 | - | 10:00 |
| New Home Sales | 684,000 | 660,000 | 10:00 |
- Equities decline with Dow down 1.23% and S&P 500 off 0.52%
- US 10-year yield rises 4 bp to 5.00% while 2-year yield adds 4 bp to 4.69%
- Attention turns to Chicago Fed index and Dallas manufacturing data today
Yesterday's Recap
Equity markets closed lower on October 25 with the Dow Jones falling 1.23% to 52,215.16 and the S&P 500 declining 0.52% to 7,623.68. The Nasdaq 100 held steady while the Russell 2000 slipped 0.29%. Treasury yields moved higher, with the 10-year yield advancing 4 bp to 5.00% and the 2-year yield rising 4 bp to 4.69%.
The dollar strengthened against the yen, with USD/JPY up 0.55% to 157.35, while EUR/USD eased 0.20%. Gold advanced 0.41% to 4,024.40 and WTI crude dropped 2.18% to 101.02. No major US data releases occurred on the session, leaving market moves driven by positioning ahead of the week’s releases and Federal Reserve signals.
Broader risk sentiment reflected caution as investors weighed persistent inflation pressures against resilient consumer spending.
The Day Ahead
The Chicago Fed National Activity Index prints at 8:30 a.m. ET, followed by the Dallas Fed Manufacturing Index at 10:30 a.m. ET.
Both releases carry medium impact and will provide fresh readings on regional activity and factory conditions. Tomorrow brings a heavier slate including final building permits, ADP employment figures, durable goods orders, Case-Shiller home prices, consumer confidence, and new home sales. Markets will also monitor API crude inventories at 4:30 p.m.
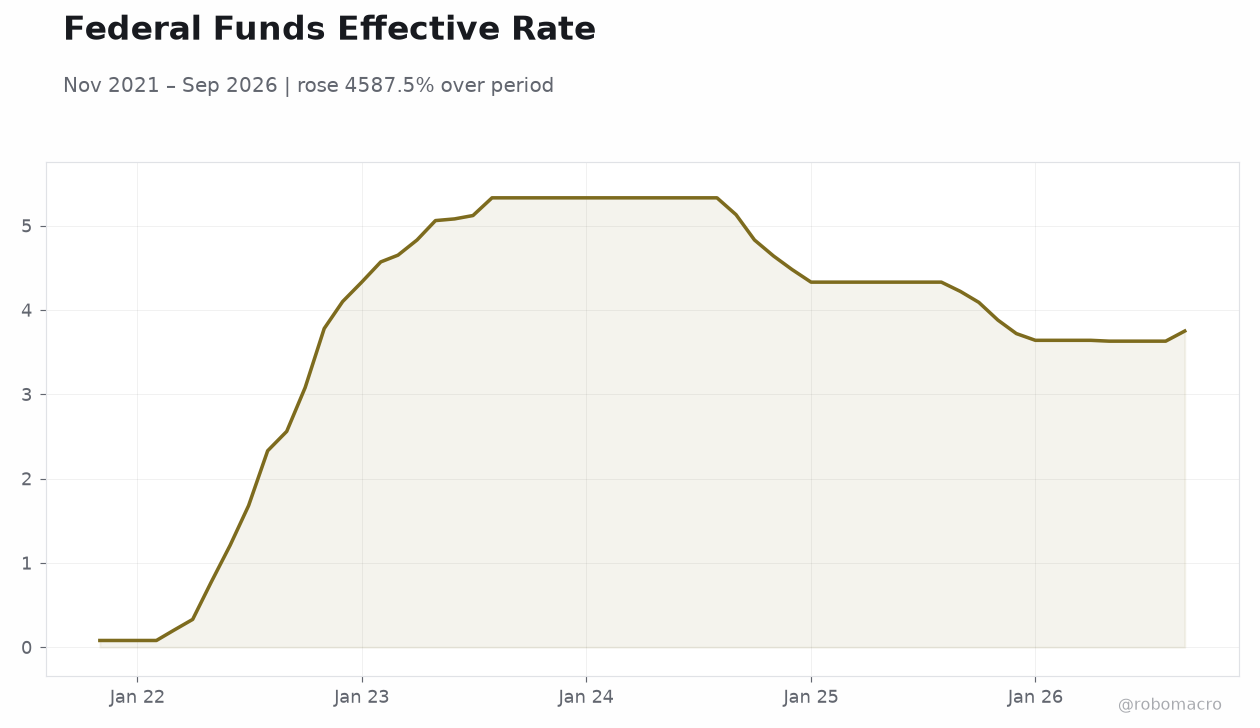
ET. These prints arrive ahead of the mid-week FOMC decision and will help shape expectations for the remainder of the year. Moderate GDP growth of 2.20% QoQ annualized and 2.19% YoY continues to underpin the outlook, while retail sales expanding 6.29% YoY support consumer-driven momentum.
Other Economic Notes
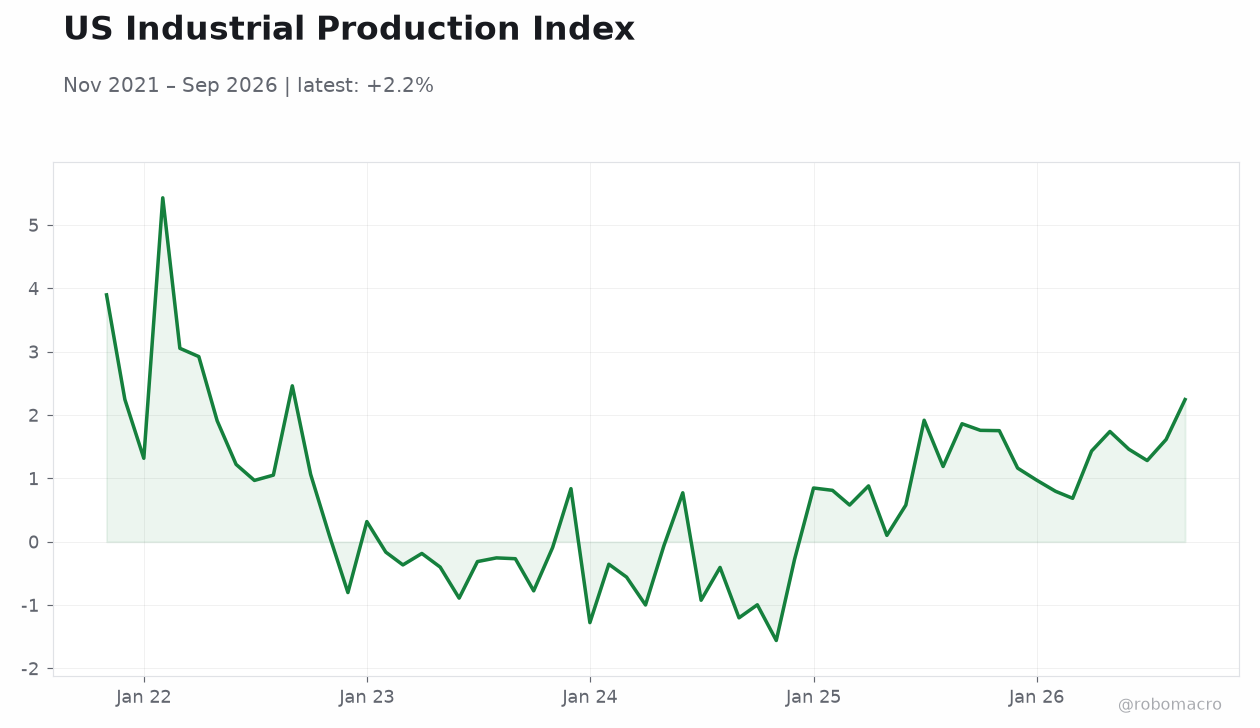
US growth remains moderate with GDP expanding 2.20% QoQ annualized in the latest reading and 2.19% on a year-over-year basis. Inflation sits at 3.70% YoY while the unemployment rate holds at 4.20%. Retail sales continue to expand at a 6.29% annual pace, supporting consumer-driven momentum.
Treasury yields near 5.00% on the 10-year reflect markets pricing in a higher-for-longer policy stance. These levels continue to influence borrowing costs across mortgages and corporate credit. ↓ p.2