US Macro Daily(Beta Mode)
Tech Rallies Into Fed Decision as Yields Creep
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,722.60 | +0.60% |
| Nasdaq 100 | 29,651.44 | +1.29% |
| Dow Jones | 52,377.57 | +0.03% |
| Russell 2000 | 2,818.87 | +1.16% |
| USD/JPY | 157.91 | +0.25% |
| EUR/USD | 1.11 | -0.43% |
| GBP/USD | 1.33 | -0.51% |
| Gold | 4,058.90 | -0.39% |
| WTI Crude | 101.38 | +1.48% |
| Bitcoin | 81,357.18 | +0.68% |
| US 2Y Treasury | 4.70% | +2 bp |
| US 10Y Treasury | 4.99% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
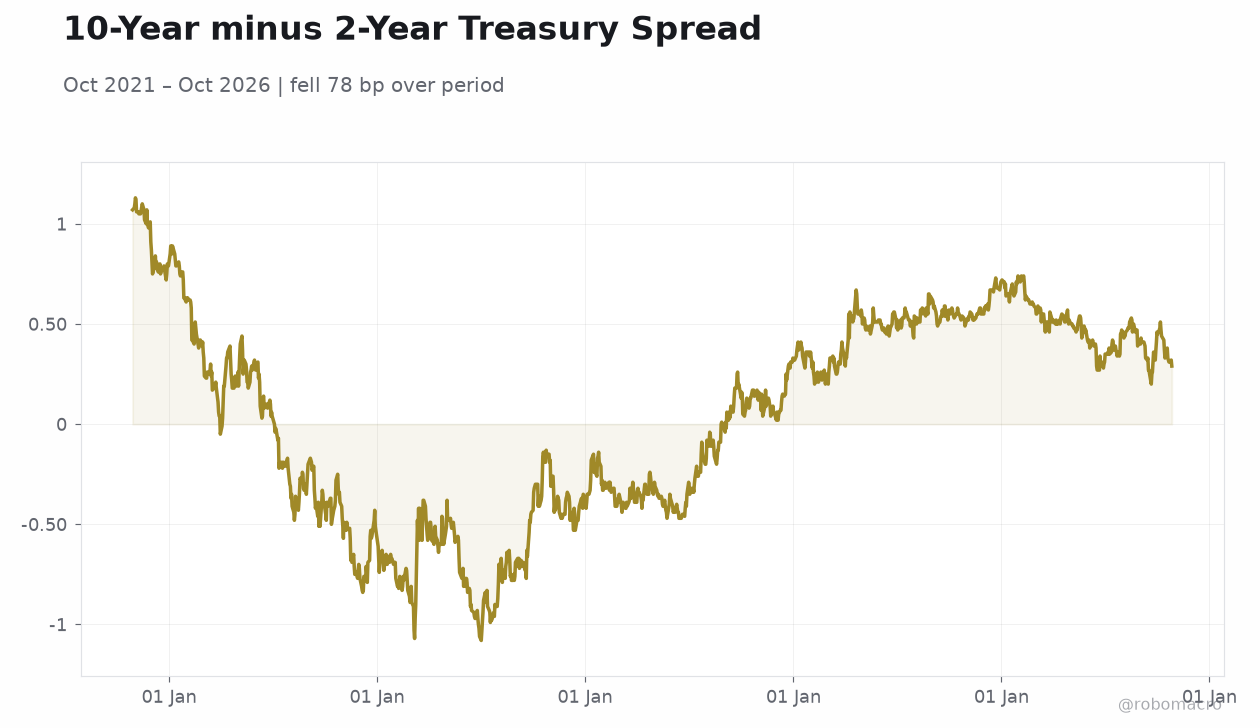 10-Year minus 2-Year Treasury Spread | Type: macro_line | 10-Year minus 2-Year Treasury Spread: 0.29 (2026-10-27) | Range: -1.08–1.13 | Trend(6pt): 1.07,-0.69,-0.29,0.51,0.31,0.29
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
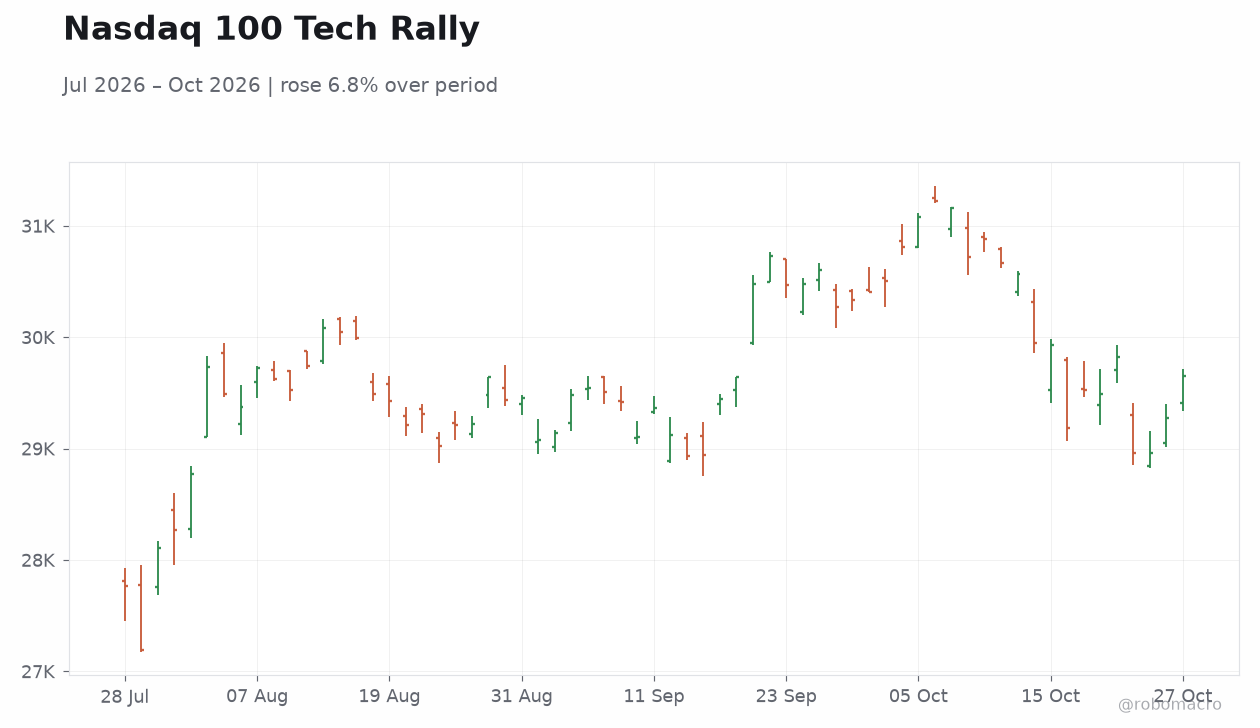
- Risk assets rallied broadly Tuesday, with the Nasdaq 100 up 1.29% and Russell 2000 up 1.16%, while the Dow lagged at +0.03%.
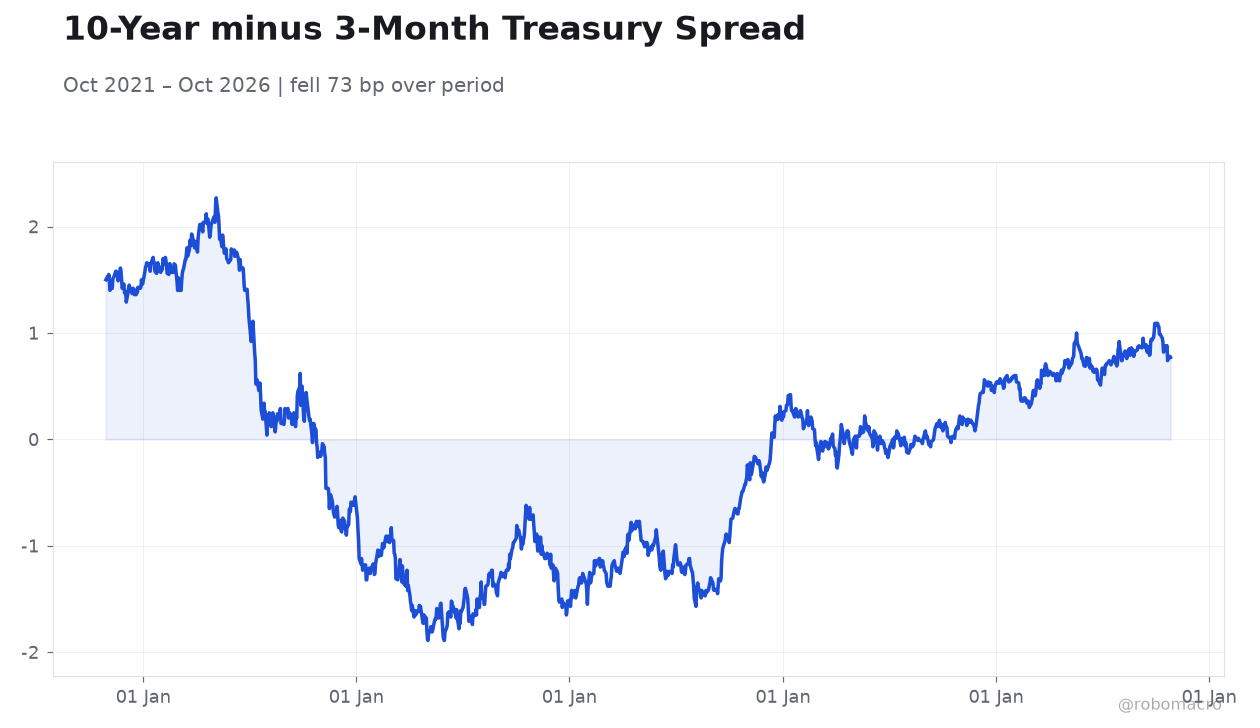
- The 2-year Treasury yield rose 2 bp to 4.70% as the 10-year eased 1 bp to 4.99%, flattening the curve ahead of the Fed.
- WTI crude jumped 1.48% to $101.38 and the dollar firmed against the euro and sterling, with EUR/USD down 0.43%.
Yesterday's Recap
US equities closed sharply higher Tuesday, led by a semiconductor and AI-linked rally that pushed the Nasdaq 100 up 1.29% to 29,651.44 and the Russell 2000 up 1.16% to 2,818.87, while the Dow Jones edged just 0.03% higher to 52,377.57. The S&P 500 added 0.60% to 7,722.60. Treasuries were mixed: the 2-year yield rose 2 bp to 4.70% while the 10-year eased 1 bp to 4.99%, leaving the curve slightly flatter.
The dollar strengthened, with EUR/USD down 0.43% to 1.11 and GBP/USD down 0.51% to 1.33, while USD/JPY rose 0.25% to 157.91. WTI crude advanced 1.48% to $101.38, gold slipped 0.39% to $4,058.90, and Bitcoin gained 0.68% to $81,357.18. No major US data releases were scheduled, leaving positioning ahead of the Fed and megacap tech earnings as the dominant driver.
The Day Ahead
All eyes are on the Federal Reserve's October policy decision, with markets widely expecting the committee to hold the target range at 3.75-4.00% despite elevated inflation running at 3.70% year-over-year. Investors will parse the statement and forward guidance for signals on the path to the December 9 meeting, particularly whether the committee retains a tightening bias. A bumper slate of megacap tech earnings lands alongside the decision, with results likely to extend or reverse Tuesday's AI-driven rally.
Treasury markets will be sensitive to any shift in the Fed's language on the balance sheet and quantitative tightening. The dollar's recent firmness against European crosses will be tested by the policy signal.
Other Economic Notes
The US economy remains resilient on paper, with GDP growth of 2.20% quarter-over-quarter annualized and retail sales up 6.29% year-over-year, though the unemployment rate at 4.20% suggests some labor-market softening. Inflation at 3.70% remains well above target, complicating the Fed's calculus as it balances price stability against growth. The 10-year yield near 5% continues to pressure rate-sensitive sectors and mortgage markets.
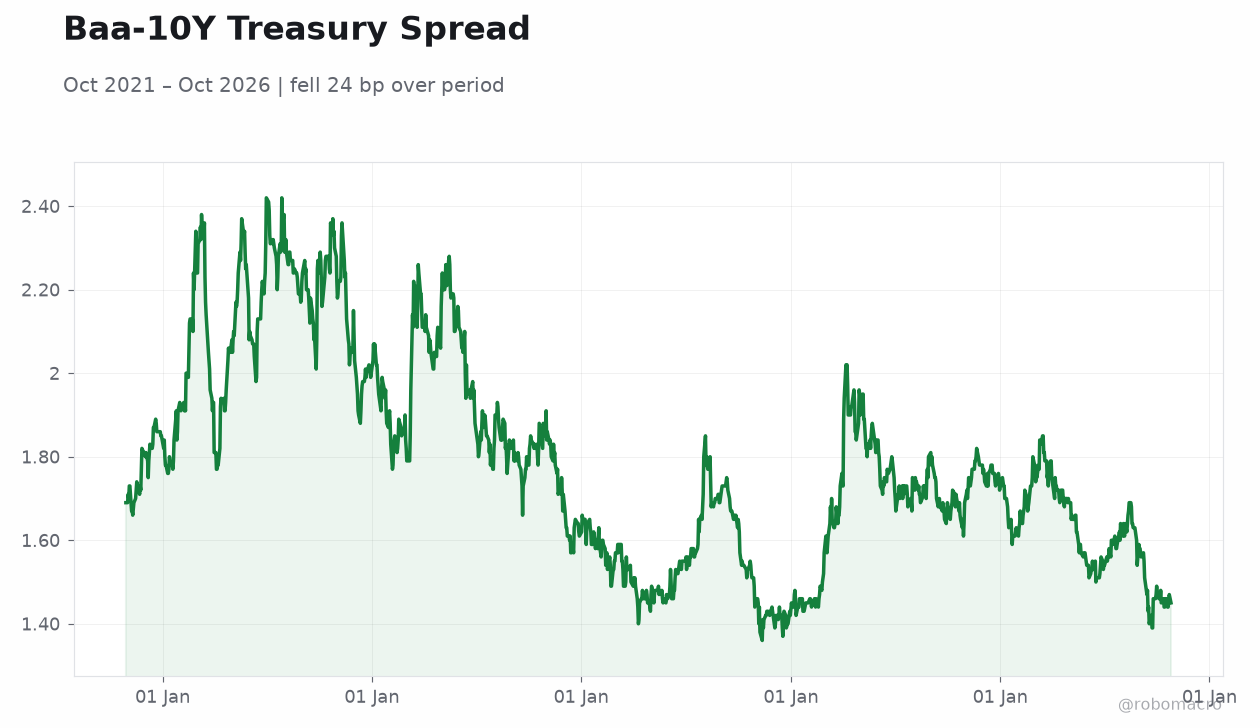
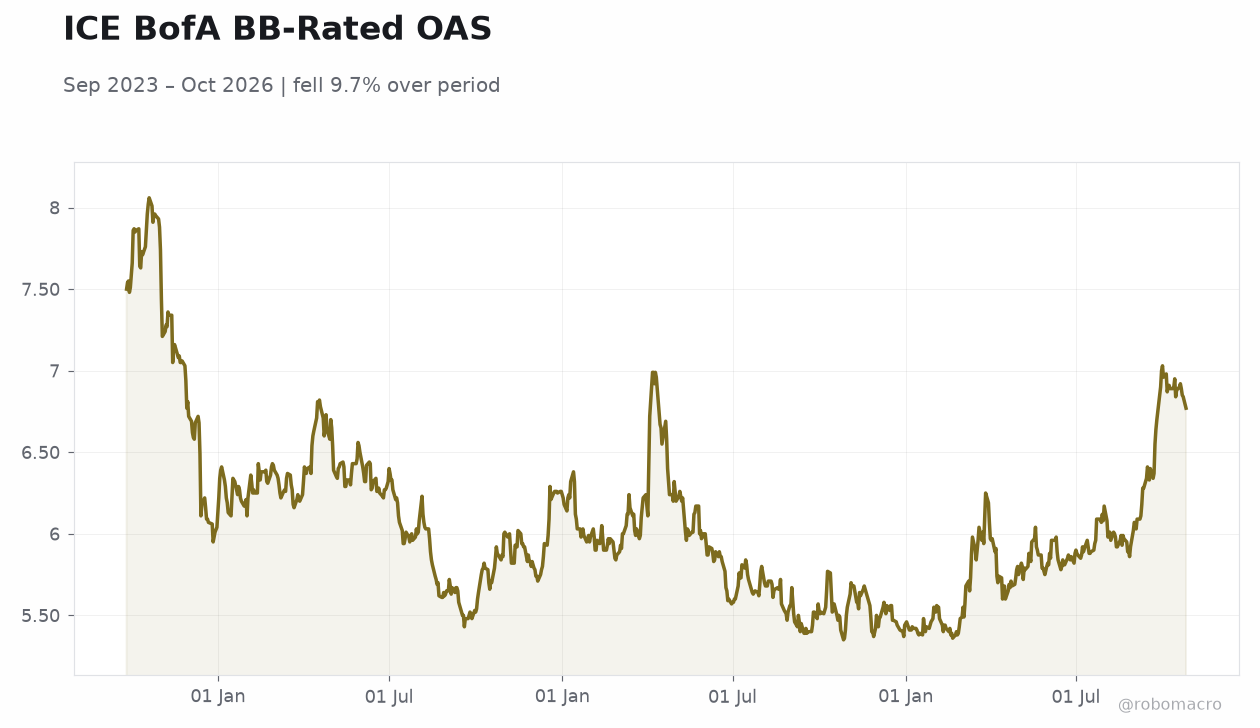
Wall Street's financing of the AI buildout is drawing scrutiny, with early signs of strain in the debt markets bankrolling data centers and chips. Fiscal dynamics remain a background risk as elevated yields raise the cost of servicing federal debt.