US Macro Daily(Beta Mode)
Manufacturing Beats as Tech Selloff Deepens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,541.40 | -0.51% |
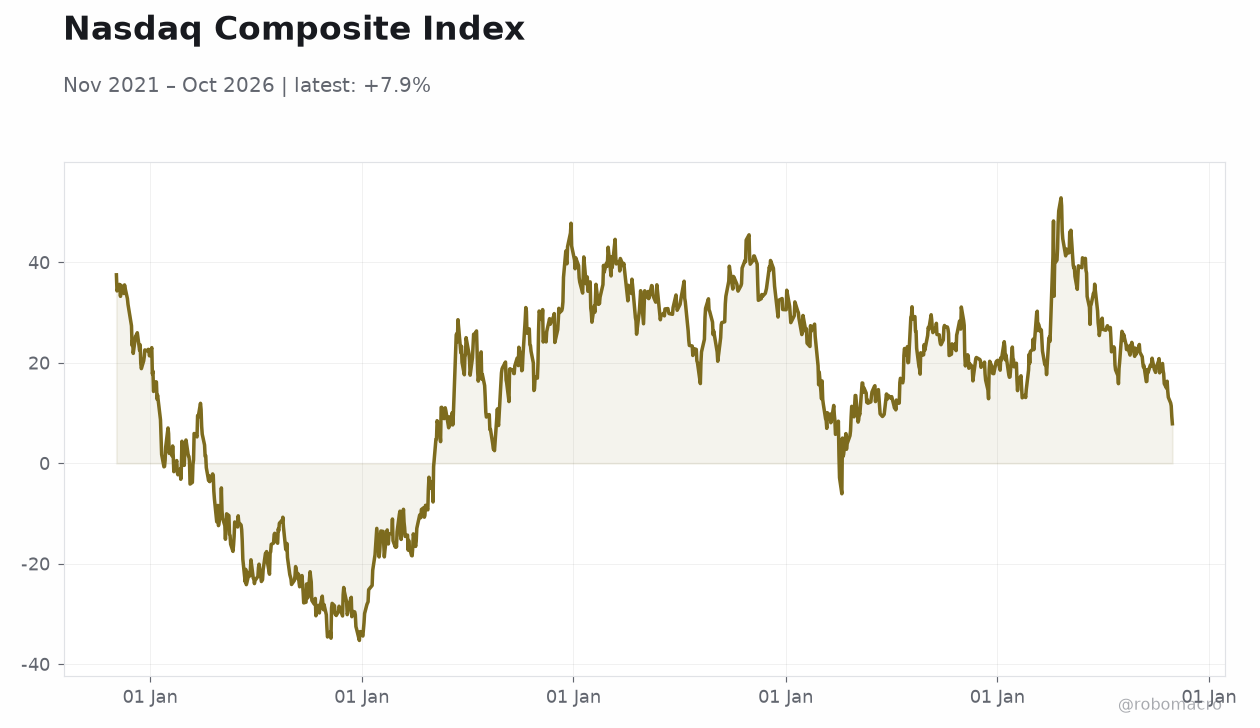
| Nasdaq 100 | 27,989.82 | -1.39% |
| Dow Jones | 51,983.98 | +0.41% |
| Russell 2000 | 2,805.88 | -0.21% |
| USD/JPY | 158.30 | +0.39% |
| EUR/USD | 1.12 | +0.21% |
| GBP/USD | 1.34 | +0.16% |
| Gold | 3,913.00 | -1.43% |
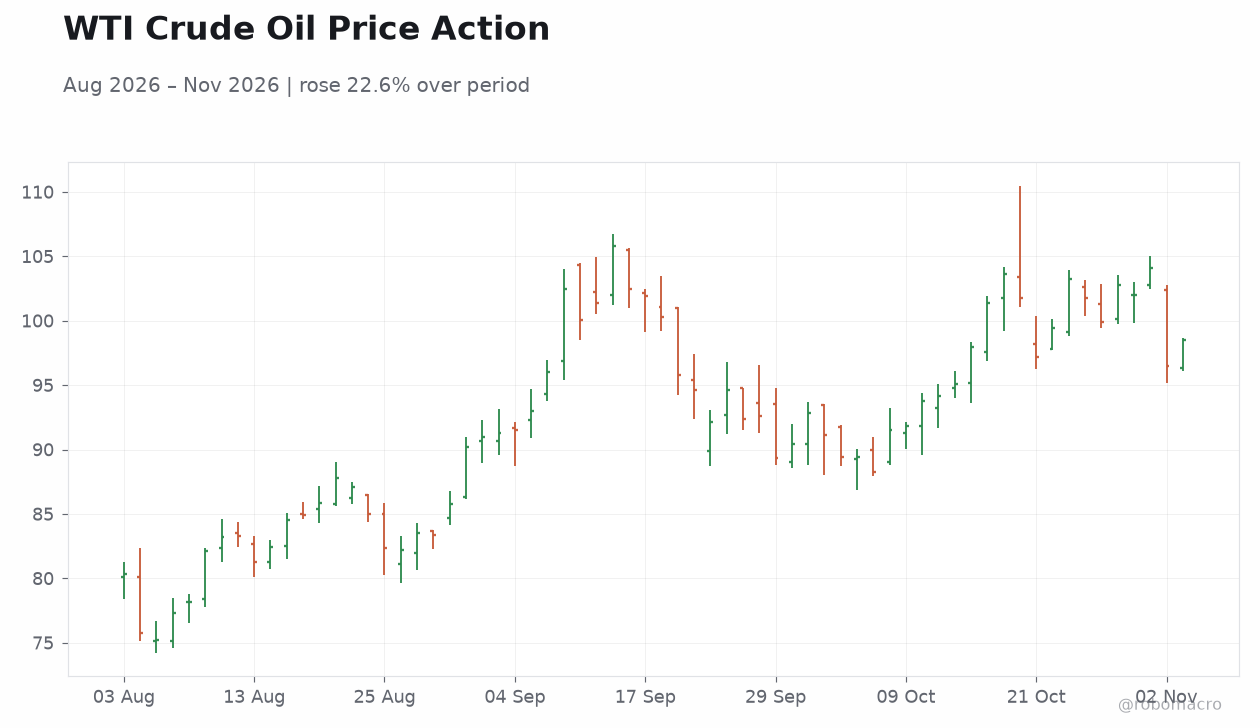
| WTI Crude | 98.53 | +2.15% |
| Bitcoin | 76,972.22 | +0.38% |
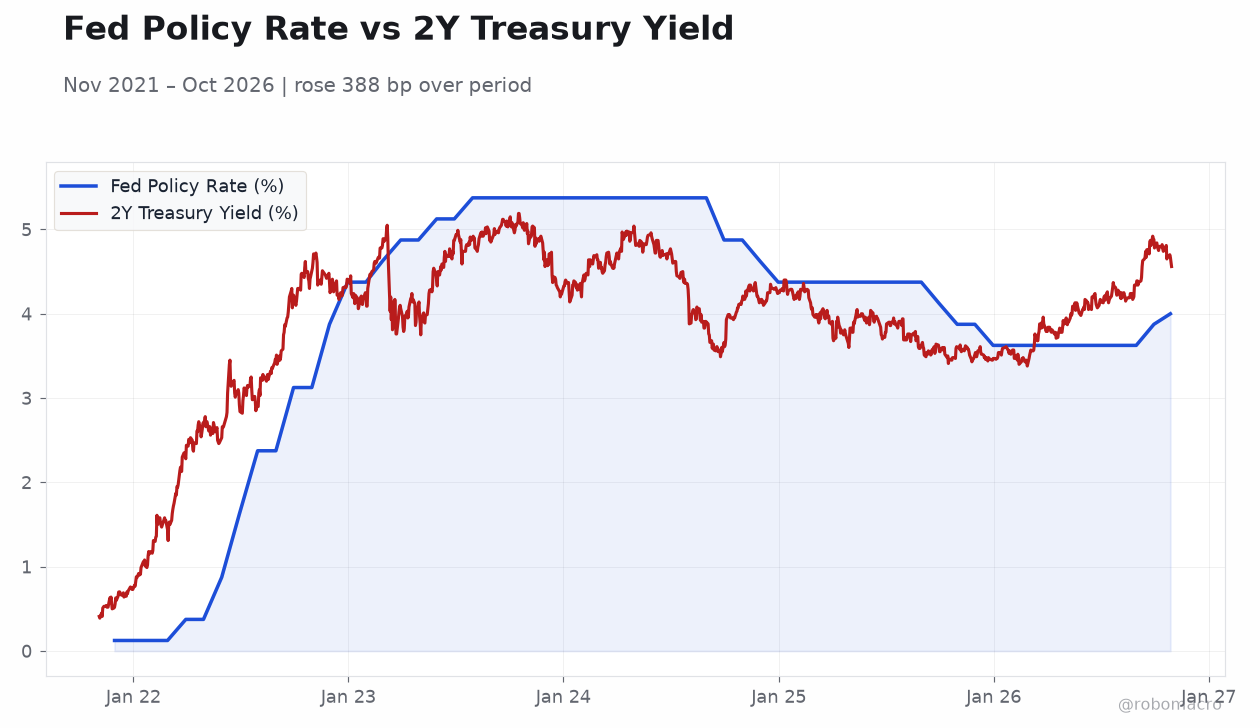
| US 2Y Treasury | 4.59% | +3 bp |
| US 10Y Treasury | 4.91% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| ISM Manufacturing PMI | 54.50 | 54.60 | 55.50 |
| ISM Manufacturing Employment | 52.70 | - | 52.40 |
| Fed Goolsbee Speech | - | - | - |
| Atlanta Fed GDPNow | 3.20 | - | 3.70 |
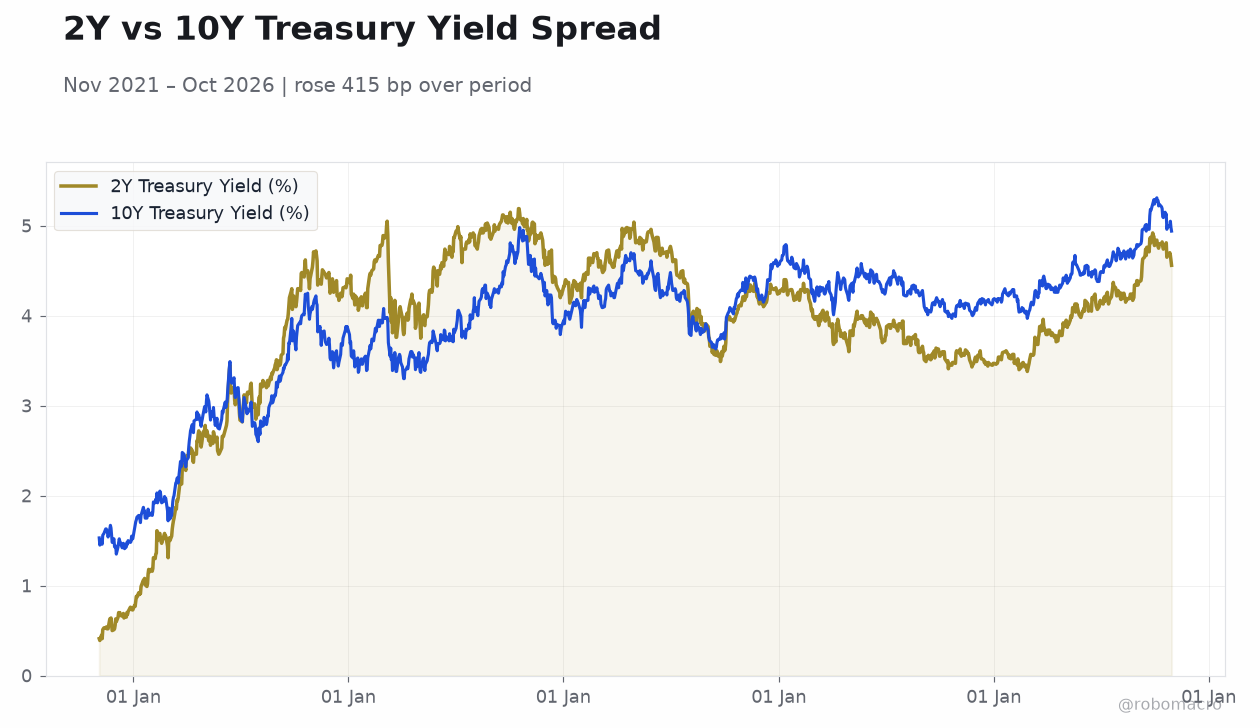 2Y vs 10Y Treasury Yield Spread | Type: macro_line | 2Y Treasury Yield (%): 4.56 (2026-10-30) | Range: 0.39–5.19 | Trend(6pt): 0.41,4.44,4.87,3.69,4.61,4.56 | 10Y Treasury Yield (%): 4.94 (2026-10-30) | Range: 1.35–5.31 | Trend(6pt): 1.53,3.63,4.58,4.23,4.98,4.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| JOLTs Job Openings | 7.1m | 7.1m | 10:00 |
| Factory Orders Month-over-Month | 0.10 | 1.20 | 10:00 |
| API Weekly Crude Oil Stocks | -2.0m | 2.1m | 16:30 |
| Wednesday (2026-11-04) | |||
| MBA 30-Year Mortgage Rate | 7.37 | - | 07:00 |
| ADP Employment Change | 90,000 | 65,000 | 08:15 |
| Exports Level | 315,200m | - | 08:30 |
| Imports Level | 420,800m | - | 08:30 |
| Trade Balance | -105,600m | -108,000m | 08:30 |
| Services Sector PMI | 54.90 | 54.80 | 10:00 |
- ISM Manufacturing PMI unexpectedly rose to 55.5 versus 54.6 consensus, signaling accelerating factory activity even as employment within the sector softened to 52.4.
- Atlanta Fed GDPNow nowcasts Q3 growth at 3.7%, up from 3.2%, reinforcing the case for the Fed's patient stance on rate cuts.
- Equity markets diverged sharply: the Dow gained 0.41% while the Nasdaq 100 fell 1.39%, with the 2s10s curve steepening as the 2-year yield rose 3 bp and the 10-year eased 3 bp.
Yesterday's Recap
US manufacturing activity surprised to the upside on November 2, with the ISM Manufacturing PMI printing at 55.5 against a 54.6 consensus and a 54.5 prior reading. The ISM Manufacturing Employment subindex slipped to 52.4 from 52.7, suggesting hiring momentum in the sector is moderating even as headline activity accelerates. The Atlanta Fed GDPNow estimate was revised up to 3.7% from 3.2%, pointing to robust third-quarter growth momentum.
Markets reacted unevenly: the S&P 500 fell 0.51% to 7,541.40 and the Nasdaq 100 dropped 1.39% to 27,989.82, while the Dow Jones rose 0.41% to 51,983.98 in a rotation away from technology. The Russell 2000 declined 0.21% to 2,805.88. In rates, the 2-year Treasury yield rose 3 bp to 4.59% while the 10-year eased 3 bp to 4.91%, steepening the curve.
Gold fell 1.43% to $3,913.00 and WTI crude jumped 2.15% to $98.53.
The Day Ahead
Attention turns to the JOLTs Job Openings report at 10:00 ET, with consensus at 7.10 million versus a prior 7.079 million, a key gauge of labor demand as the Fed assesses slack. Factory Orders Month-over-Month is also due at 10:00 ET, with consensus at 1.2% following a prior 0.1% gain. The API Weekly Crude Oil Stocks report at 16:30 ET carries a consensus build of 2.1 million barrels after last week's 2.031 million draw.
Wednesday brings ADP Employment Change at 08:15 ET, with consensus at 65,000 versus a prior 90,000, alongside the trade balance and Services Sector PMI at 10:00 ET, where consensus sits at 54.8 versus a prior 54.9. These releases will shape expectations ahead of Friday's payrolls report and the December 9 FOMC meeting.
Other Economic Notes
The US economy continues to show resilience, with GDP growth at 3.40% QoQ SAAR and 2.07% YoY as of Q3, while retail sales YoY stands at a robust 6.29%. Unemployment at 4.20% remains low, though consumer sentiment appears strained despite stable growth and low inflation, a disconnect highlighted in recent commentary. CPI YoY at 3.70% remains above the Fed's target, complicating the case for near-term easing.
↓ p.2