US Macro Daily(Beta Mode)
Risk Assets Surge as Services PMI Cools
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,688.62 | +1.58% |
| Nasdaq 100 | 28,437.17 | +0.91% |
| Dow Jones | 53,356.12 | +3.03% |
| Russell 2000 | 2,856.95 | +1.58% |
| USD/JPY | 158.34 | -0.08% |
| EUR/USD | 1.12 | +0.21% |
| GBP/USD | 1.35 | +0.19% |
| Gold | 4,141.20 | +1.67% |
| WTI Crude | 88.78 | +0.75% |
| Bitcoin | 80,254.03 | -0.19% |
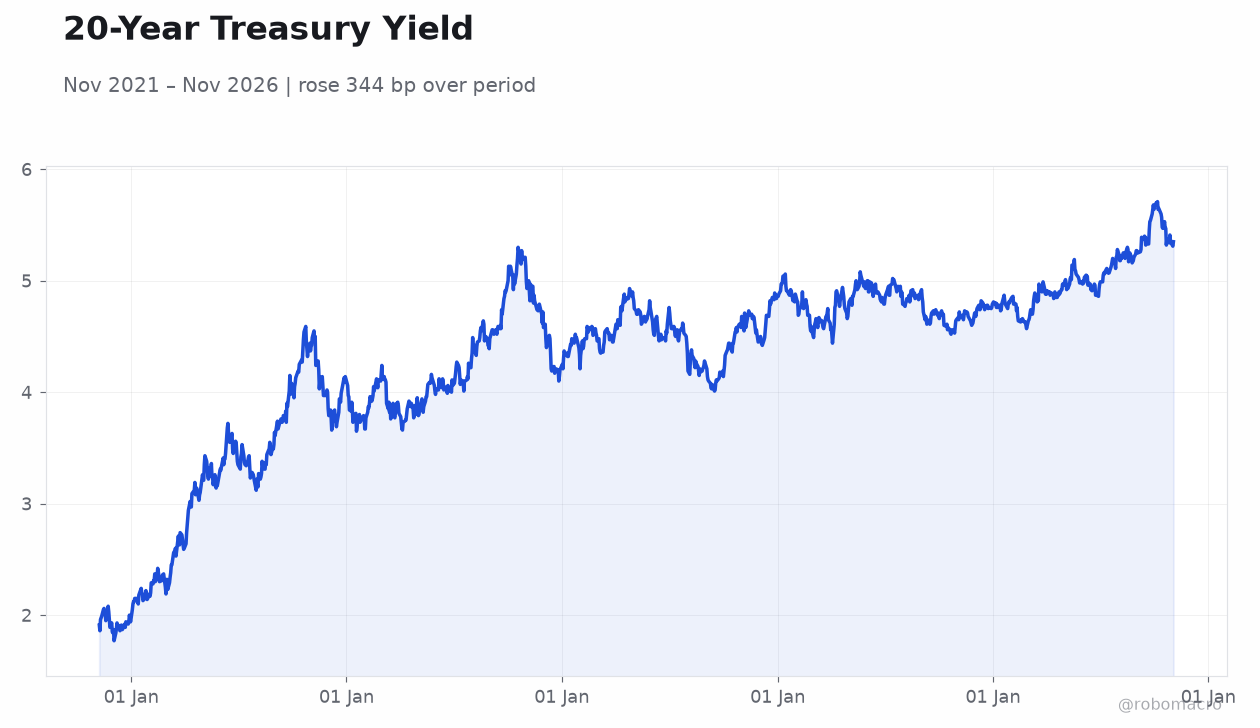
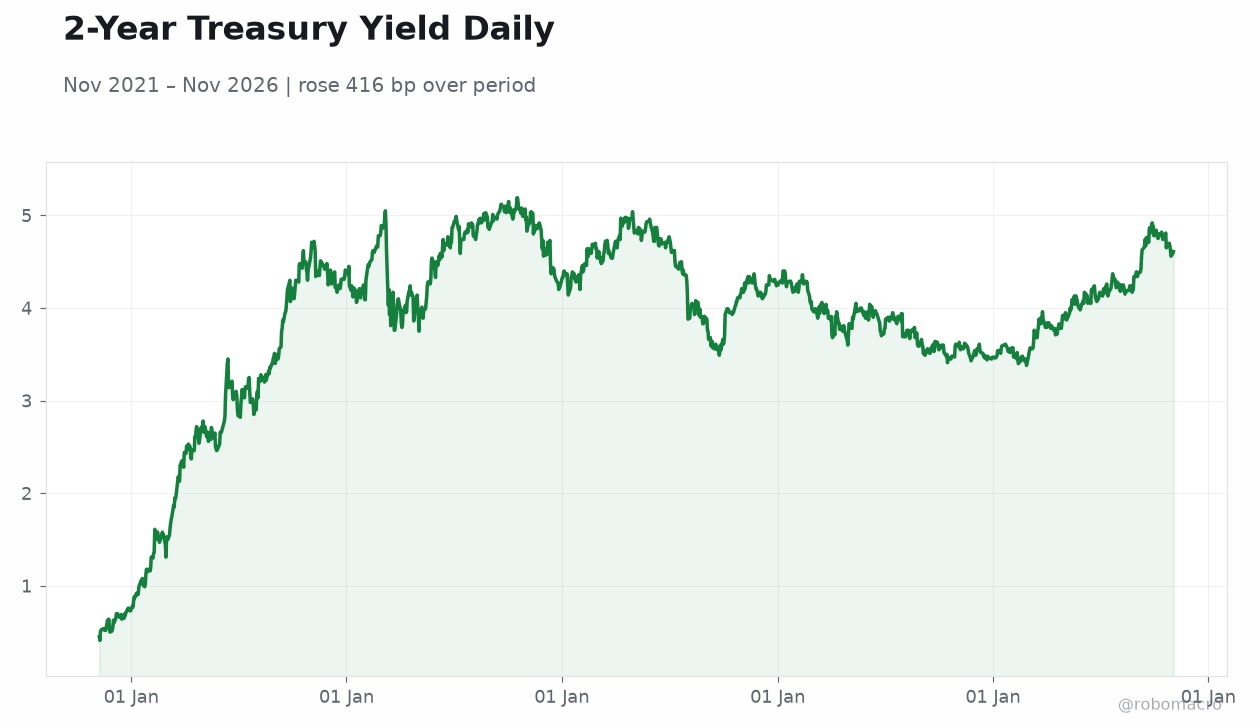
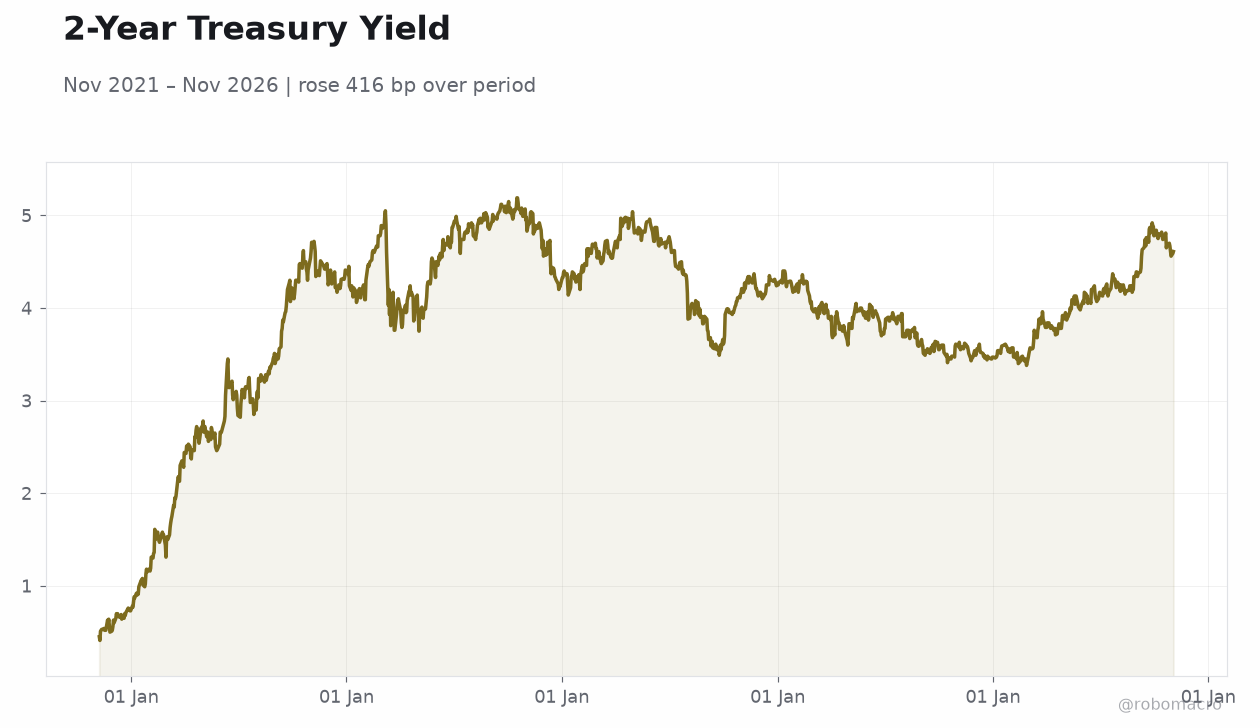
| US 2Y Treasury | 4.58% | -3 bp |
| US 10Y Treasury | 4.90% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| ISM Manufacturing Employment | 52.70 | - | 52.40 |
| Fed Goolsbee Speech | - | - | - |
| Atlanta Fed GDPNow | 3.20 | - | 3.70 |
| JOLTs Job Openings | 7.2m | 7.1m | 7.5m |
| Factory Orders Month-over-Month | 0.30 | 1.20 | 1.80 |
| API Weekly Crude Oil Stocks | -2.0m | 2.1m | -5.3m |
| API Weekly Crude Oil Stocks | -2.0m | 2.1m | -5.3m |
| MBA 30-Year Mortgage Rate | 7.37 | - | 7.30 |
| ADP Employment Change | 86,000 | 69,000 | 86,000 |
| Exports Level | 315,700m | - | 321,500m |
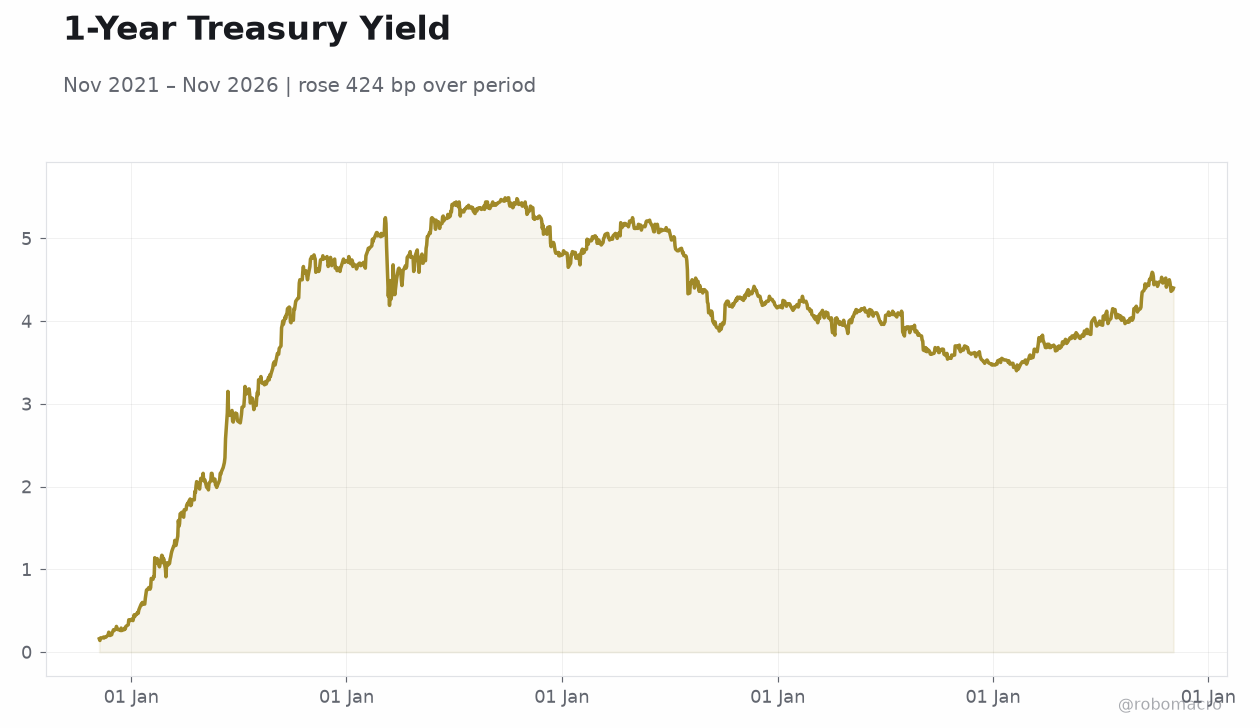 1-Year Treasury Yield | Type: macro_line | 1-Year Treasury Yield: 4.4 (2026-11-03) | Range: 0.14–5.49 | Trend(6pt): 0.16,4.87,5.12,3.92,4.38,4.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Nonfarm Productivity Quarter-over-Quarter Prel | 1.40 | 2.50 | 08:30 |
| Weekly Jobless Claims | 194,000 | 196,000 | 08:30 |
| Fed Hammack Speech | - | - | 08:50 |
| Speech by Fed's Barkin | - | - | 09:10 |
| Speech by Fed's Logan | - | - | 19:00 |
- Equities rallied sharply, with the Dow up 3.03% and S&P 500 up 1.58%, as markets digested a cooler services PMI and softer Treasury yields
- JOLTs job openings surprised to the upside at 7.523M versus 7.10M consensus, signaling labor market resilience
- Trade balance narrowed to -$105B on stronger exports, while services PMI slipped to 54.5 from 54.9
Yesterday's Recap
US equities posted broad-based gains Wednesday, with the Dow Jones surging 3.03% to 53,356.12 and the S&P 500 climbing 1.58% to 7,688.62, while the Russell 2000 rose 1.58% to 2,856.95. The services sector PMI printed at 54.5, modestly below the 54.9 prior reading and 54.8 consensus, suggesting a slight cooling in service-sector momentum. ADP employment change came in at 86,000, matching the prior month's reading but beating the 69,000 consensus estimate.
The trade balance narrowed to -$105.0B from -$105.7B prior, with exports rising to $321.5B and imports at $426.6B. JOLTs job openings unexpectedly jumped to 7.523M versus 7.10M consensus and 7.19M prior, indicating persistent labor demand. Factory orders rose 1.8% month-over-month, well above the 1.2% consensus and 0.3% prior.
The MBA 30-year mortgage rate eased to 7.30% from 7.37%. EIA crude inventories fell 865,000 barrels and gasoline stocks declined 222,000 barrels. Treasury yields moved lower, with the 10-year easing 5 bp to 4.90% and the 2-year down 3 bp to 4.58%, while gold rallied 1.67% to $4,141.20 and WTI crude gained 0.75% to $88.78.
The Day Ahead
Markets will focus on the weekly EIA natural gas storage report and the usual Thursday jobless claims data, which will be scrutinized for signs of labor market deterioration following the strong JOLTs print. Investors will also monitor any Fed speaker appearances for signals on the December 9 FOMC meeting trajectory. The Treasury's quarterly refunding announcements continue to shape duration expectations after the recent guidance revamp.
With midterm election results now in hand and Democrats poised to take Congress, market participants will assess implications for fiscal policy and debt ceiling dynamics heading into 2027. Attention also turns to any revised inflation expectations data given the Fed's November forecast noted by Yahoo Finance as "downright ugly" for Wall Street.
Other Economic Notes
The US economy continues to show mixed signals, with GDP growth at 3.40% QoQ SAAR in Q2 but inflation remaining elevated at 3.70% YoY as of September. Retail sales growth of 6.29% YoY underscores consumer resilience, though the unemployment rate at 4.20% suggests some labor market softening from cycle lows. ↓ p.2