US Macro Daily(Beta Mode)
Jobs Beat Lifts Yields; CPI Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
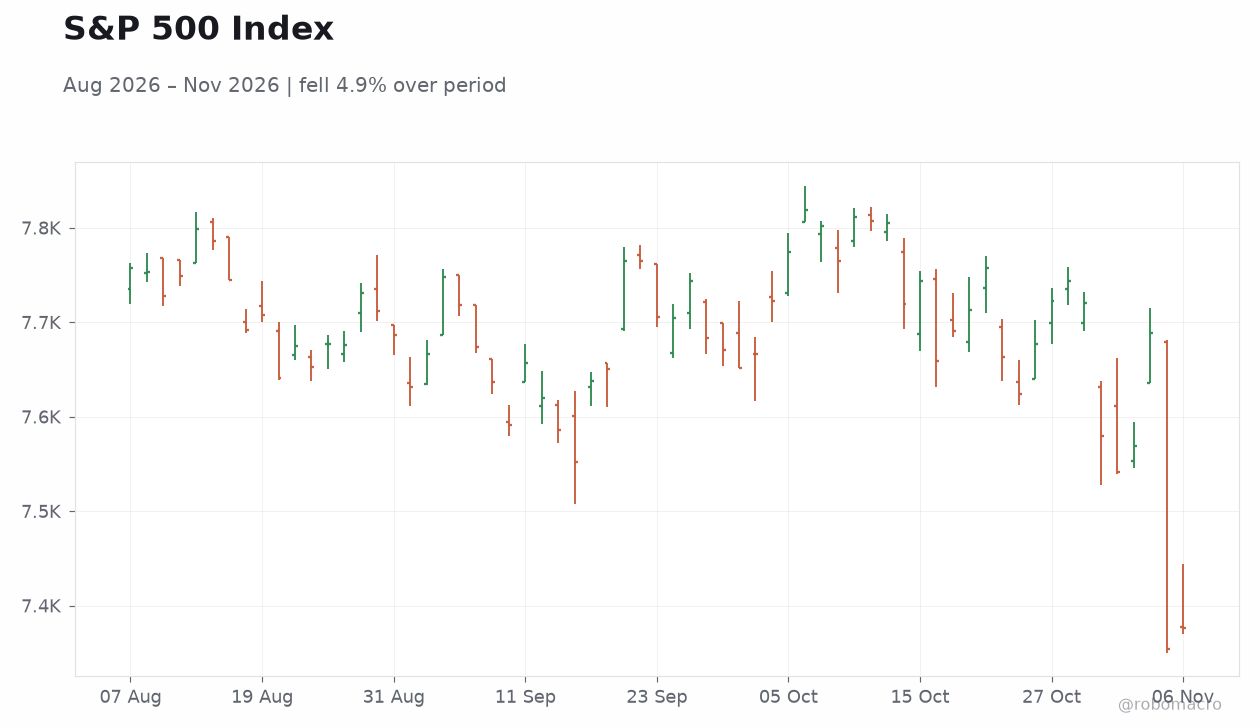
| S&P 500 | 7,376.86 | +0.31% |
| Nasdaq 100 | 26,989.99 | +1.35% |
| Dow Jones | 51,285.73 | -0.46% |
| Russell 2000 | 2,754.11 | +0.89% |
| USD/JPY | 157.89 | +0.25% |
| EUR/USD | 1.12 | -0.30% |
| GBP/USD | 1.34 | -0.26% |
| Gold | 4,110.20 | +0.87% |
| WTI Crude | 88.97 | -2.05% |
| Bitcoin | 74,406.15 | -0.24% |
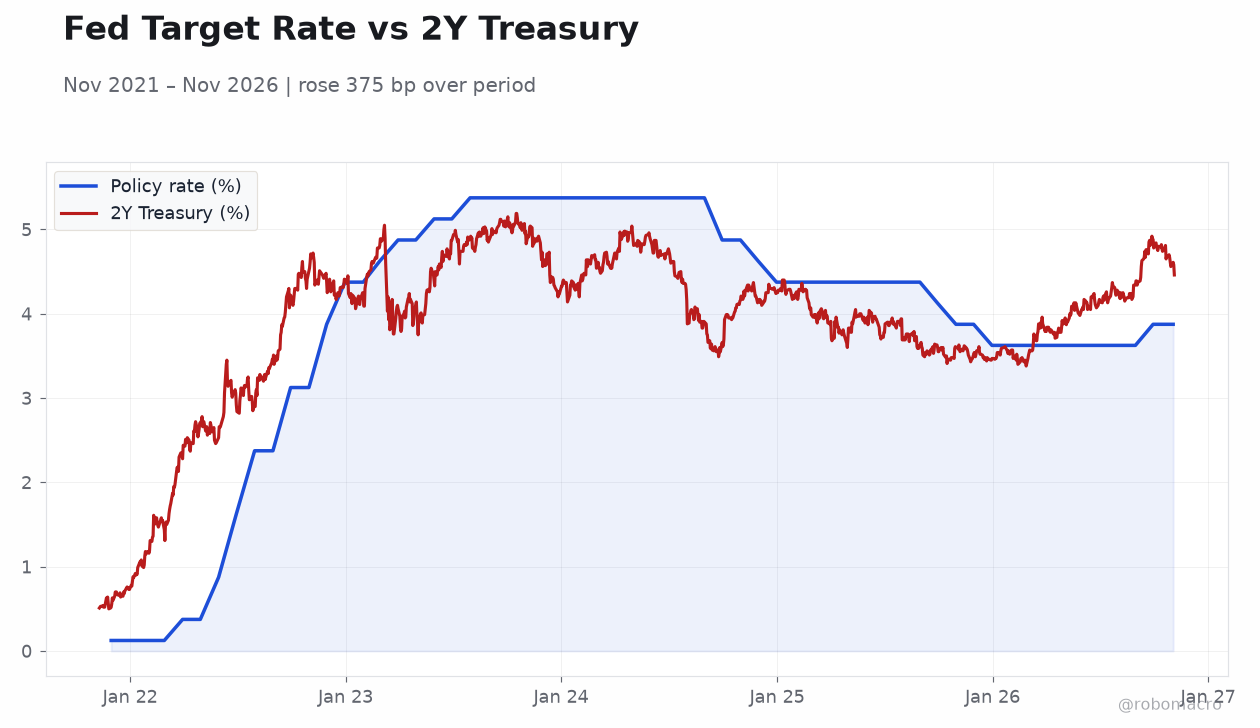
| US 2Y Treasury | 4.51% | +5 bp |
| US 10Y Treasury | 4.86% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
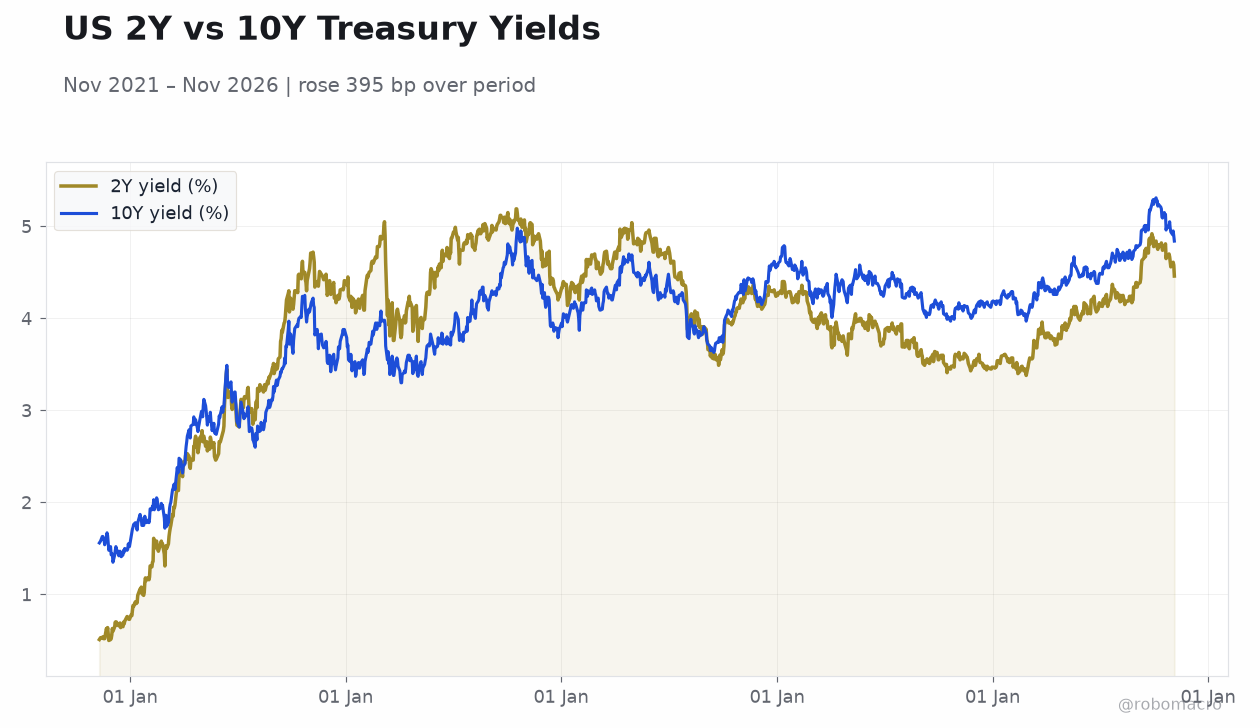 US 2Y vs 10Y Treasury Yields | Type: macro_line | 2Y yield (%): 4.46 (2026-11-05) | Range: 0.5–5.19 | Trend(6pt): 0.51,4.5,4.84,3.72,4.58,4.46 | 10Y yield (%): 4.84 (2026-11-05) | Range: 1.35–5.31 | Trend(6pt): 1.56,3.74,4.48,4.23,4.9,4.84
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | 08:40 |
| Fed Goolsbee Speech | - | - | 10:00 |
| Speech by Fed's Barkin | - | - | 12:15 |
| Speech by Fed's Bowman | - | - | 12:15 |
| Fed Goolsbee Speech | - | - | 15:00 |
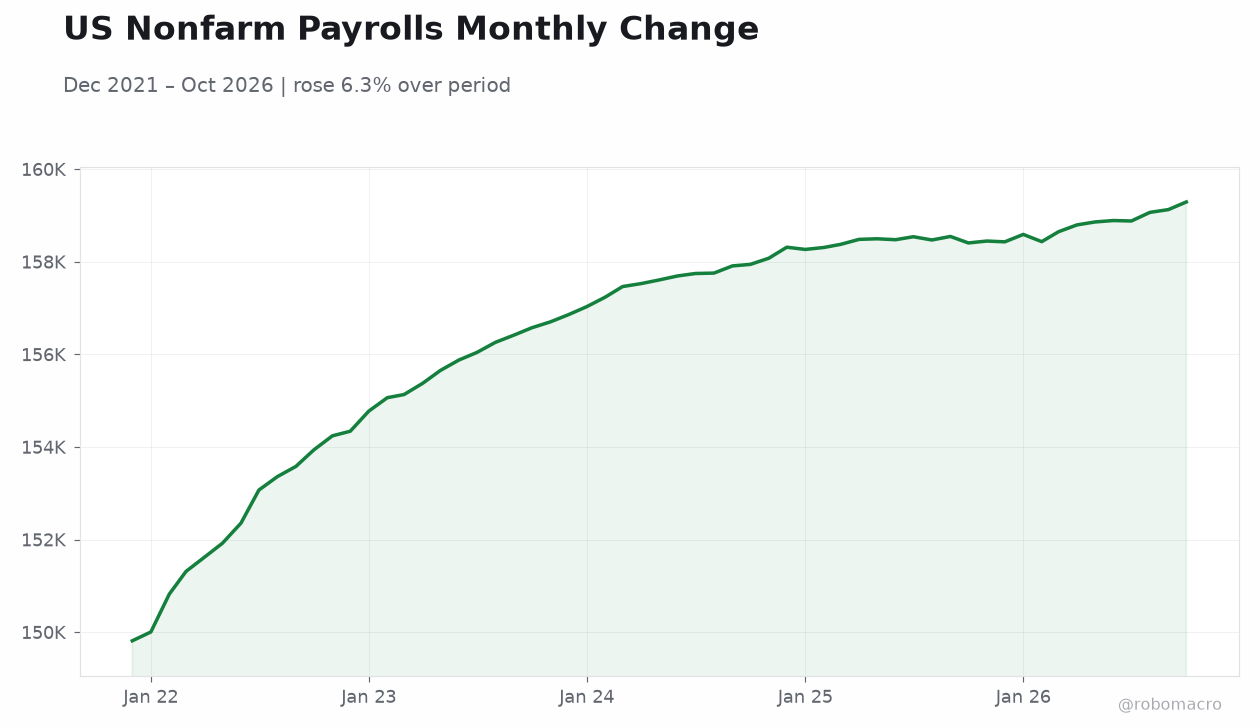
- October payrolls rose 165,000, beating expectations and reinforcing market bets that the Fed will raise rates rather than cut.
- Treasury yields pushed higher on the strong labor data, with the 2-year up 5 bp to 4.51% and the 10-year up 2 bp to 4.86%.
- Attention shifts to tomorrow's CPI, where consensus sees headline inflation at 3.9% y/y and core at 2.8% y/y, both above prior readings.
Yesterday's Recap
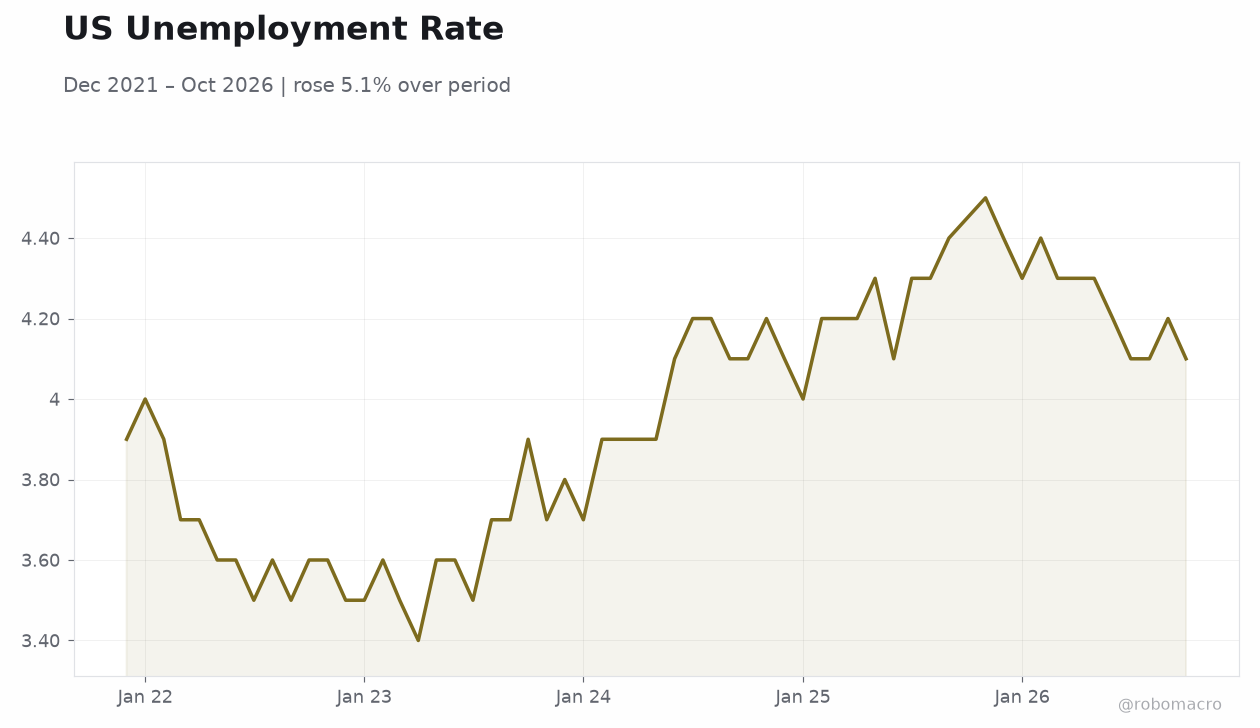
The October employment report dominated Friday's session, with nonfarm payrolls rising 165,000 — comfortably above forecasts — and the unemployment rate declining to 4.10%. The print reinforced the narrative of a resilient labor market and pushed rate-hike expectations higher, lifting the 2-year Treasury yield 5 bp to 4.51% and the 10-year 2 bp to 4.86%. Equity markets were mixed: the Nasdaq 100 gained 1.35% and the Russell 2000 rose 0.89%, while the Dow Jones slipped 0.46% and the S&P 500 added just 0.31%.
The dollar firmed against major crosses, with EUR/USD down 0.30% to 1.12 and USD/JPY up 0.25% to 157.89. Gold rose 0.87% to $4,110.20, while WTI crude fell 2.05% to $88.97 on demand concerns. Bitcoin was roughly flat, down 0.24% at $74,406.
The Day Ahead
The calendar is light on hard data but heavy on Fed communication. Governor Bowman speaks at 08:40 and again at 12:15, while Chicago Fed President Goolsbee — a high-impact event — speaks at 10:00 and 15:00, and Richmond Fed President Barkin speaks at 12:15. Markets will parse these remarks for signals on the December 9 FOMC decision, particularly whether the strong jobs print has shifted the committee's reaction function.
No major Tier-1 releases are scheduled, so positioning ahead of tomorrow's CPI will likely dominate flows. Tomorrow's calendar is far heavier: CPI for October at 08:30, weekly ADP employment at 08:15, and a Waller speech at 04:00.
Other Economic Notes
The October payrolls beat has revived the "higher-for-longer" debate, with markets now leaning toward the possibility of a rate hike rather than a cut at the December meeting. Retail sales growth of 6.29% y/y and GDP running at 3.40% QoQ SAAR suggest demand remains robust, complicating the disinflation story. Tomorrow's CPI is the critical test: consensus expects headline inflation to accelerate to 3.9% y/y from 3.7%, with core at 2.8% y/y from 2.6%.
A hot print would cement expectations for tighter policy and likely extend the Treasury selloff. Separately, the IRS announced higher 2027 tax brackets and standard deductions, a routine inflation adjustment with limited near-term macro impact.