US Macro Daily(Beta Mode)
Hot CPI Lifts Stocks, Yields Jump
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,619.38 | +1.31% |
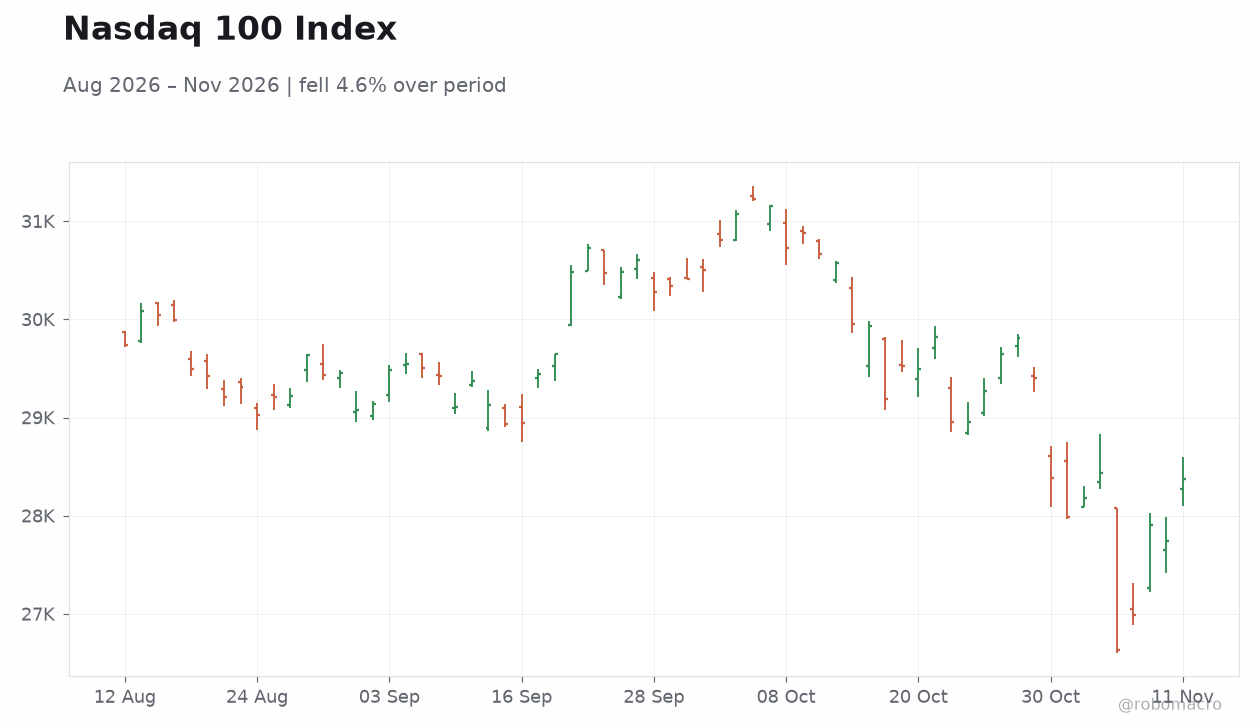
| Nasdaq 100 | 28,374.25 | +2.28% |
| Dow Jones | 52,486.49 | +0.49% |
| Russell 2000 | 2,846.26 | +0.88% |
| USD/JPY | 159.65 | +0.59% |
| EUR/USD | 1.11 | -0.67% |
| GBP/USD | 1.33 | -0.60% |
| Gold | 3,954.60 | -1.15% |
| WTI Crude | 85.98 | -0.64% |
| Bitcoin | 73,250.35 | -0.97% |
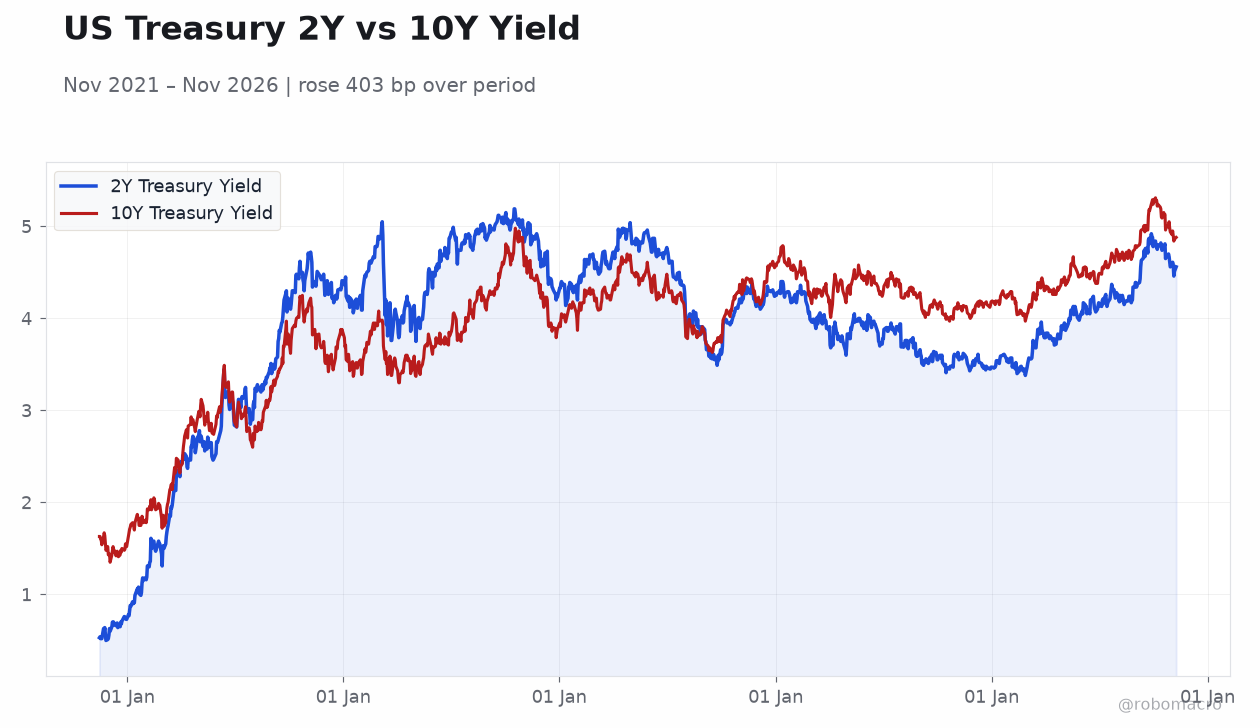
| US 2Y Treasury | 4.73% | +17 bp |
| US 10Y Treasury | 4.98% | +10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| ADP Employment Change Weekly | 16,750 | - | 19,750 |
| Core Inflation Rate Month-over-Month | 0.30 | 0.20 | 0.30 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.80 | "" |
| Inflation Rate Month-over-Month | 0.60 | 0.30 | 0.40 |
| Inflation Rate Year-over-Year | 3.70 | 3.90 | "" |
| CPI s.a | 336.30 | - | 337.48 |
| Consumer Price Index | 336.94 | 337.02 | 337.51 |
| Speech by Fed's Logan | - | - | - |
| Eia Short-Term Energy Outlook | - | - | "" |
| Speech by Fed's Bowman | - | - | - |
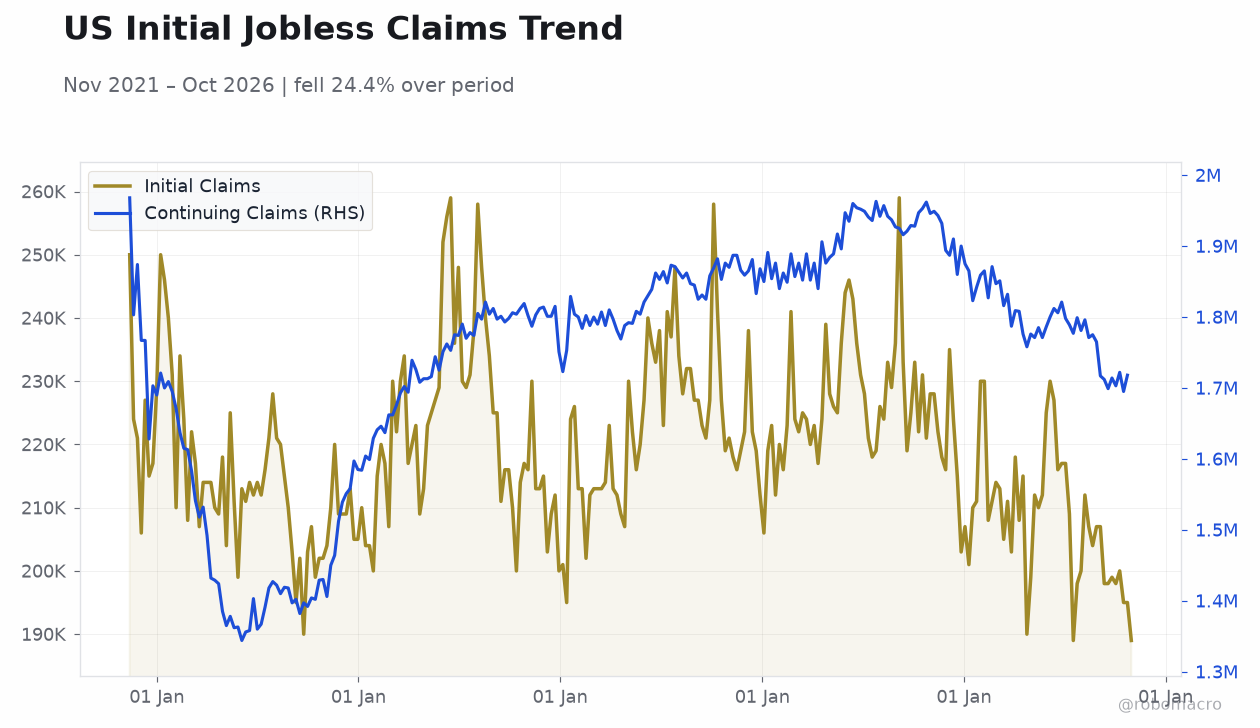 US Initial Jobless Claims Trend | Type: macro_line | Initial Claims: 1.89e+05 (2026-10-31) | Range: 1.89e+05–2.59e+05 | Trend(5pt): 2.5e+05,2.2e+05,2.22e+05,2.24e+05,1.89e+05 | Continuing Claims: 1.718e+06 (2026-10-24) | Range: 1.344e+06–1.968e+06 | Trend(6pt): 1.968e+06,1.641e+06,1.788e+06,1.936e+06,1.722e+06,1.718e+06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Weekly Jobless Claims | 189,000 | 195,000 | 08:30 |
| Fed Hammack Speech | - | - | 09:00 |
| Existing Home Sales | 4.0m | 3.9m | 10:00 |
| Existing Home Sales Month-over-Month | 1.50 | - | 10:00 |
| Speech by Fed's Barr | - | - | 10:00 |
| Fed Goolsbee Speech | - | - | 11:30 |
| EIA Weekly Crude Oil Inventory | -865,000 | -1.1m | 12:00 |
| EIA Weekly Gasoline Inventory | -222,000 | -100,000 | 12:00 |
| Fed Daly Speech | - | - | 13:10 |
| Monthly Budget Statement | -27,000m | -298,600m | 14:00 |
- October core CPI rose 0.3% m/m, above the 0.2% consensus, keeping the Fed's hiking bias intact
- Equities rallied despite the inflation surprise, with Nasdaq 100 up 2.28% and S&P 500 up 1.31%
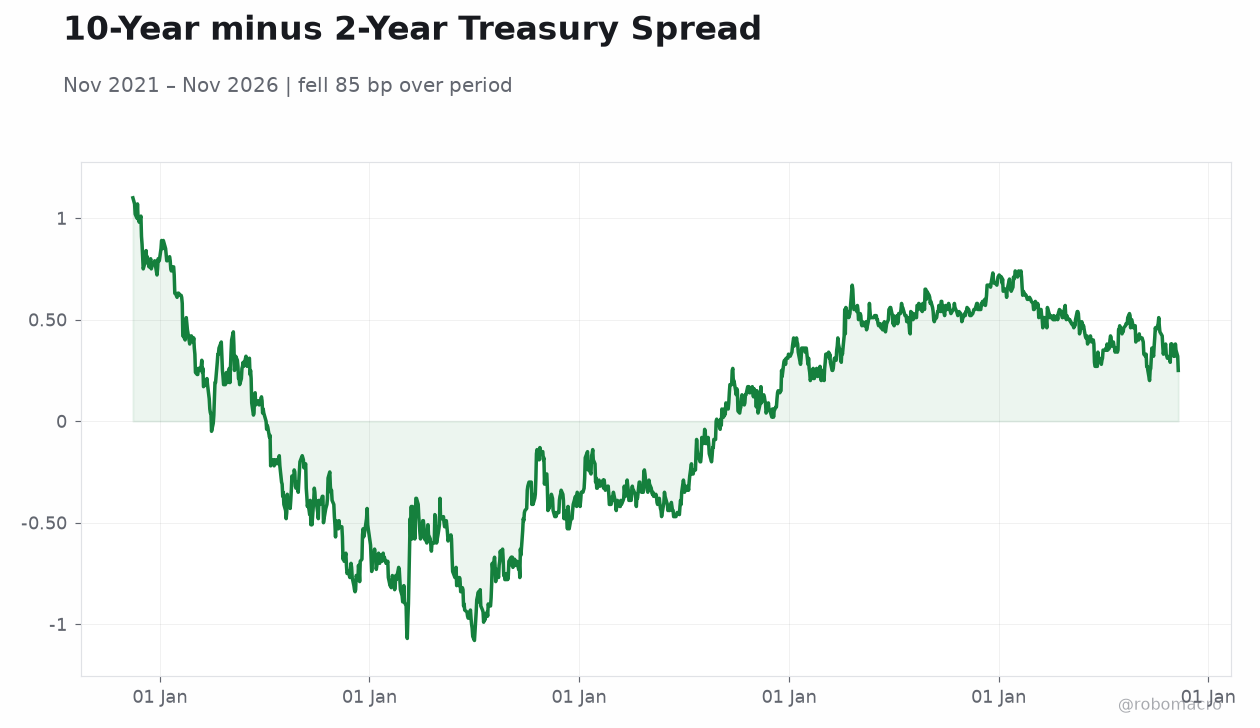
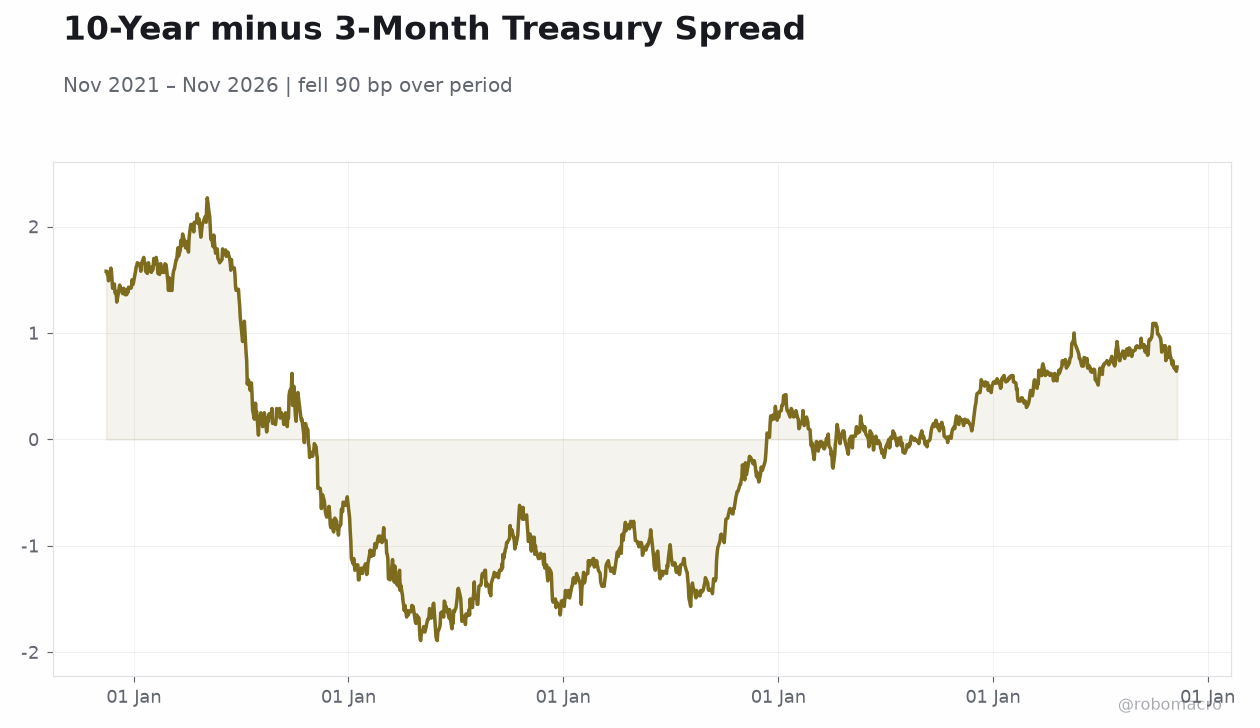
- Treasury curve bear-flattened sharply: 2-year yield +17 bp to 4.73%, 10-year +10 bp to 4.98%
Yesterday's Recap
October CPI delivered an upside surprise, with core inflation at 0.3% m/m versus consensus of 0.2%, while headline CPI rose 0.4% m/m against a 0.3% expectation. The CPI index printed at 337.51 versus a 337.02 consensus. ADP weekly employment change came in at 19,750, up from 16,750 previously, pointing to resilient labor demand.
Markets read the hot print as demand-resilient rather than rate-hike-inducing: the S&P 500 gained 1.31% to 7,619.38, the Nasdaq 100 surged 2.28% to 28,374.25, and the Russell 2000 added 0.88%. The bond market told a different story, with the 2-year yield jumping 17 bp to 4.73% and the 10-year rising 10 bp to 4.98% — a bear-flattening move that signals near-term hike risk. The dollar strengthened, with EUR/USD down 0.67% to 1.11 and USD/JPY up 0.59% to 159.65, while gold fell 1.15% to $3,954.60.
API weekly crude stocks showed a build of 9 million barrels versus a 1 million draw expected, and WTI slipped 0.64% to $85.98.
The Day Ahead
Markets reopen Thursday after the Veterans Day bond-market holiday, with Treasury futures already pointing to a deeper selloff at the cash open following Tuesday's inflation-fueled rout. The MBA 30-year mortgage rate printed at 7.21% on November 11, underscoring persistent housing affordability pressure as financing costs stay elevated. With no major top-tier data on the docket, attention shifts to Fed speakers and the digestion of the CPI surprise across rate-sensitive sectors.
Weekly jobless claims and any incremental Fed commentary will be scrutinized for confirmation that the disinflation trend has stalled. Equity futures will be tested on whether Tuesday's rally can extend without the cushion of imminent rate cuts.
Other Economic Notes
The October CPI surprise complicates the disinflation narrative, with core inflation running at 0.3% m/m and headline at 0.4% m/m — both above target-consistent paces. Unemployment at 4.10% and Q2 GDP growth of 3.40% SAAR suggest the economy retains momentum, giving the Fed little urgency to ease. Retail sales growth of 6.29% y/y points to a consumer that is still spending, though the 7.21% mortgage rate is squeezing housing activity.
The combination of firm growth and sticky inflation keeps the "higher for longer" regime firmly in place.