US Macro Daily(Beta Mode)
Yields Jump as Housing Cracks
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,592.40 | -0.35% |
| Nasdaq 100 | 28,289.19 | -0.30% |
| Dow Jones | 52,297.09 | -0.36% |
| Russell 2000 | 2,799.06 | -1.66% |
| USD/JPY | 159.93 | +0.12% |
| EUR/USD | 1.11 | -0.35% |
| GBP/USD | 1.32 | -0.34% |
| Gold | 3,896.00 | +0.28% |
| WTI Crude | 88.19 | -0.62% |
| Bitcoin | 69,246.71 | -2.94% |
| US 2Y Treasury | 4.86% | +13 bp |
| US 10Y Treasury | 5.10% | +12 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| API Weekly Crude Oil Stocks | -5.3m | -1m | 9m |
| Speech by Fed's Bowman | - | - | - |
| Treasury Secretary Bessent Speech | - | - | - |
| MBA 30-Year Mortgage Rate | 7.30 | - | 7.21 |
| Weekly Jobless Claims | 191,000 | 195,000 | 200,000 |
| Fed Hammack Speech | - | - | - |
| Existing Home Sales | 4.0m | 3.9m | 3.8m |
| Existing Home Sales Month-over-Month | 1 | - | -5.50 |
| Speech by Fed's Barr | - | - | - |
| Fed Goolsbee Speech | - | - | - |
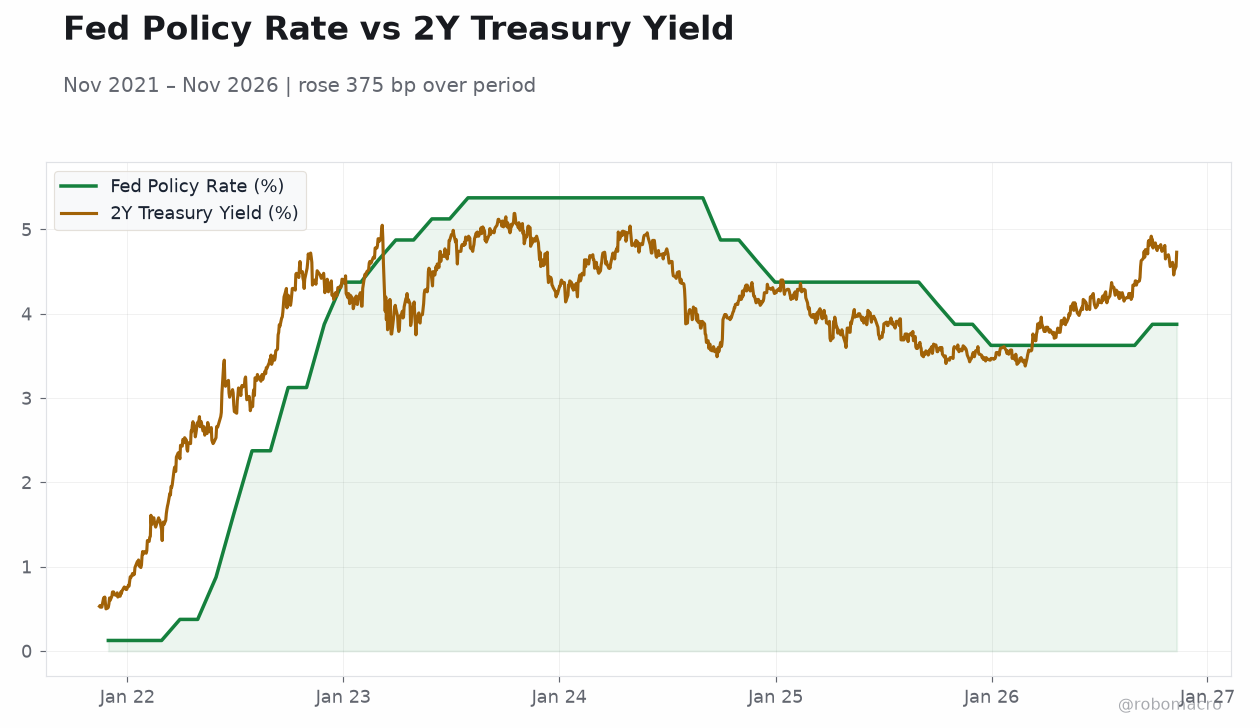
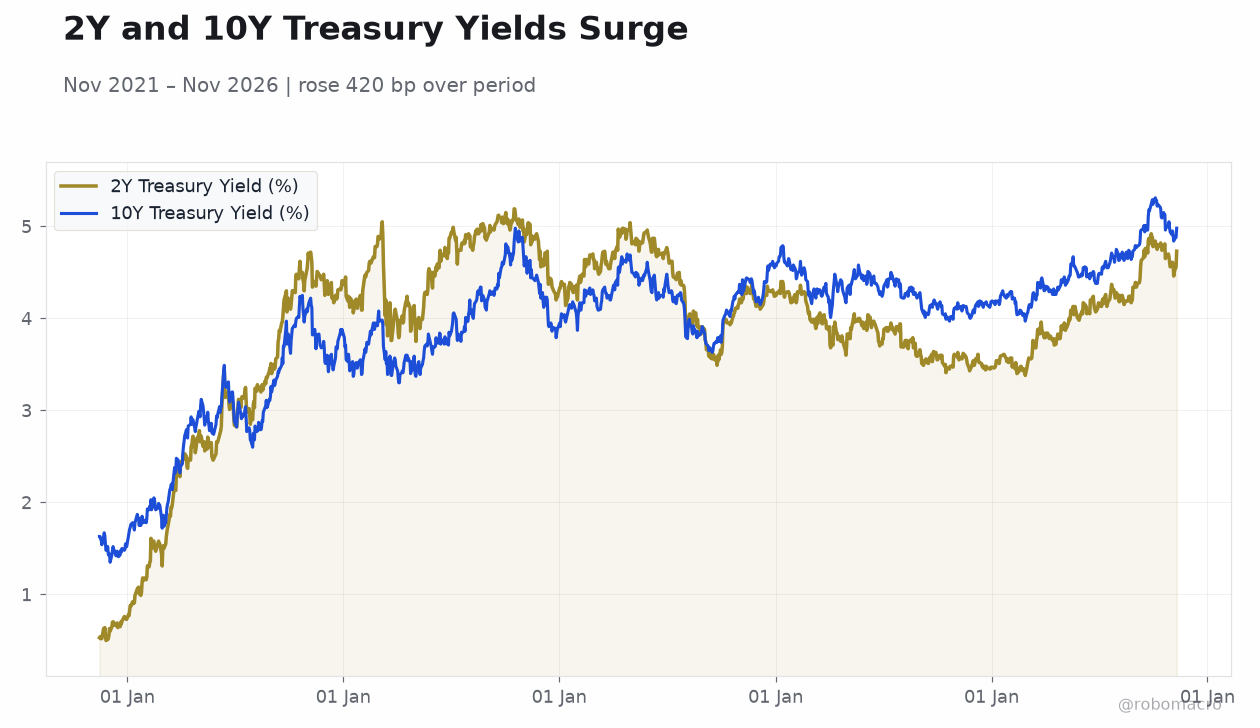 2Y and 10Y Treasury Yields Surge | Type: macro_line | 2Y Treasury Yield (%): 4.86 (2026-11-12) | Range: 0.5–5.19 | Trend(6pt): 0.53,4.6,4.87,3.76,4.51,4.73 | 10Y Treasury Yield (%): 5.1 (2026-11-12) | Range: 1.35–5.31 | Trend(6pt): 1.63,3.77,4.5,4.27,4.86,4.98
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Producer Price Index Month-over-Month | 1.30 | 0.40 | 08:30 |
| Core PPI Month-over-Month | 0.70 | 0.30 | 08:30 |
| Speech by Fed's Bowman | - | - | 10:50 |
| Fed Daly Speech | - | - | 12:00 |
| Speech by Fed's Jefferson | - | - | 19:00 |
- Treasury yields surged, with the 2-year up 13 bp to 4.86% and the 10-year up 12 bp to 5.10%, as markets price a slower path to rate cuts.
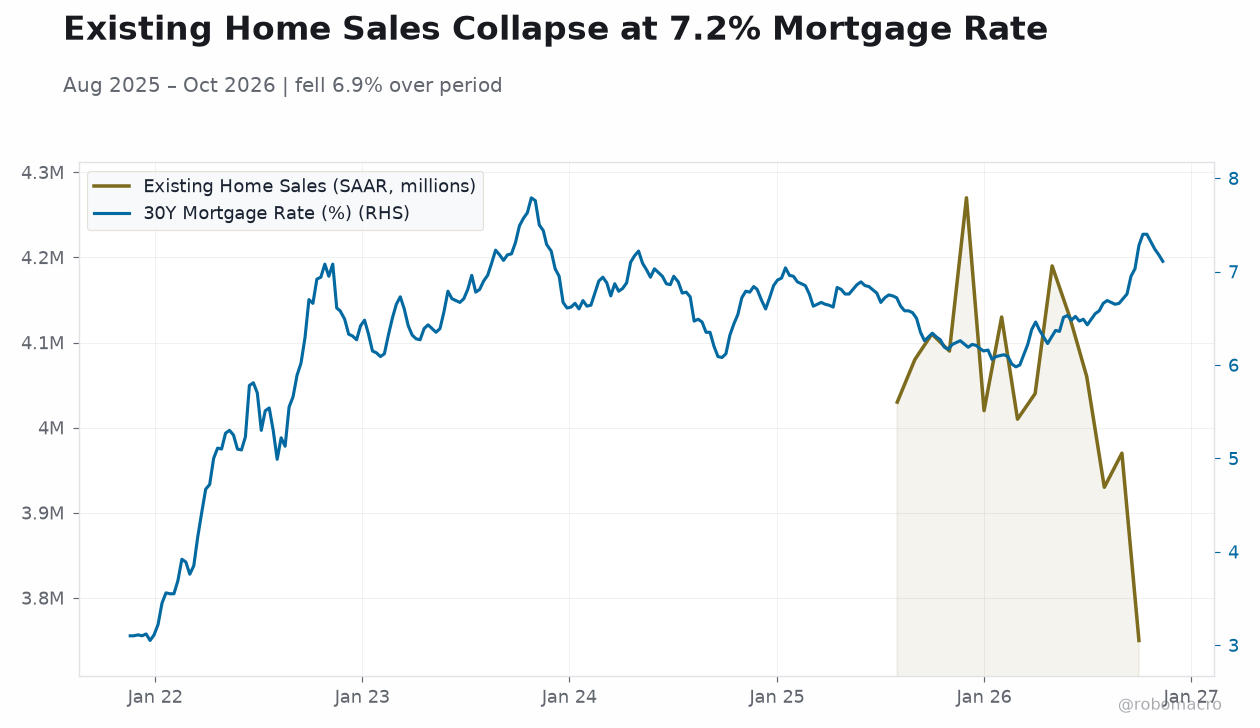
- Existing home sales plunged 5.5% m/m to a 3.75 million annualized pace, well below the 3.85 million consensus, underscoring housing stress at 7.21% mortgage rates.
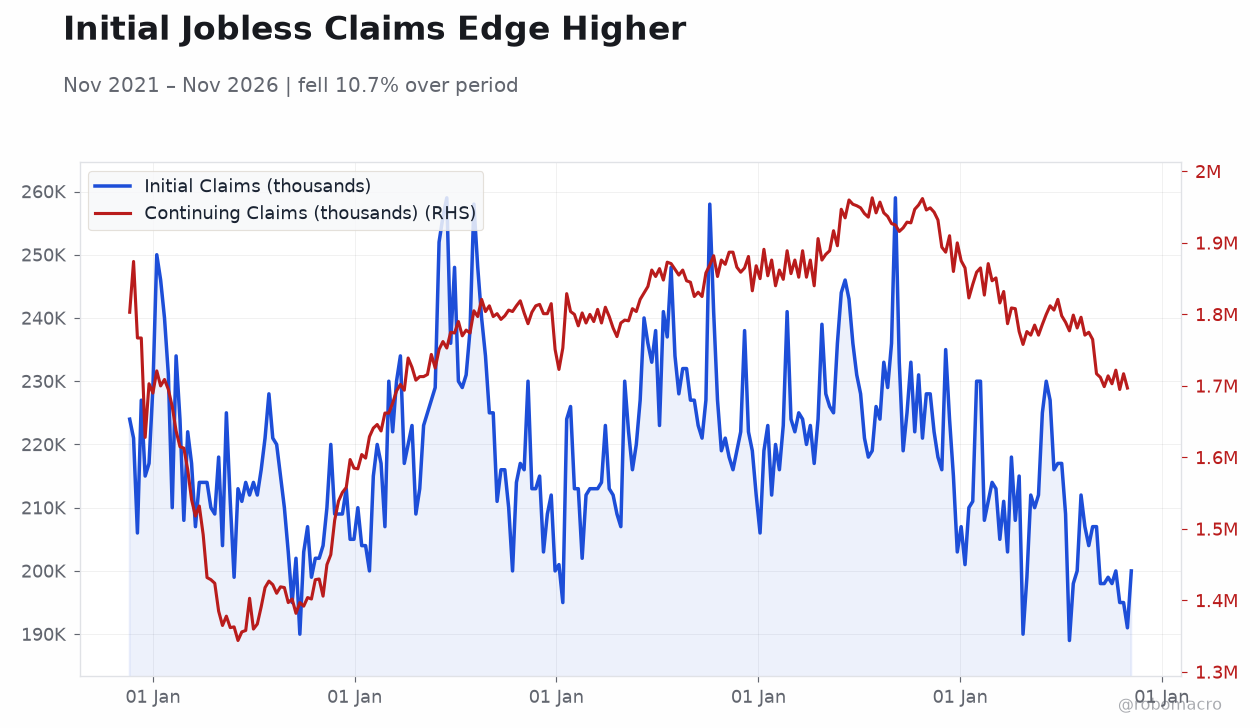
- Weekly jobless claims rose to 200,000, above the 195,000 consensus, while a $404 billion monthly budget deficit added to duration supply concerns.
Yesterday's Recap
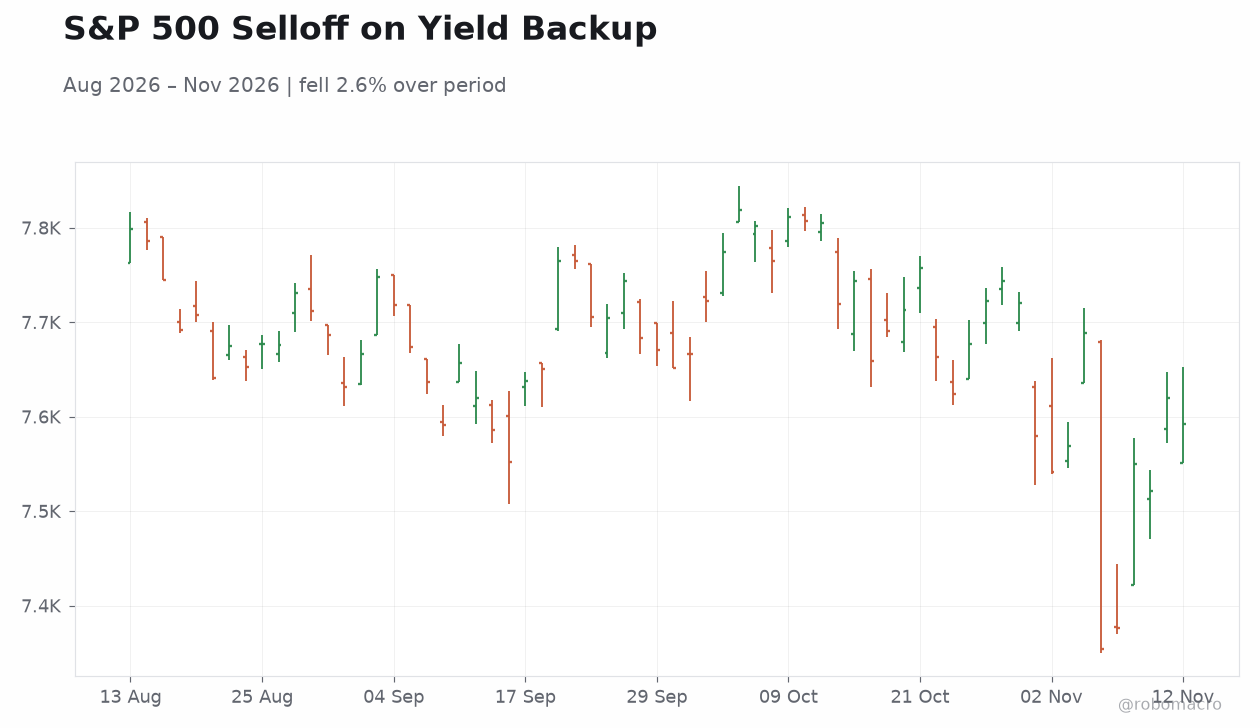
US equities sold off broadly on November 12, with the Russell 2000 down 1.66% and the S&P 500 off 0.35% to 7,592.40 as rate-sensitive small caps bore the brunt of the yield backup. The 2-year Treasury yield jumped 13 bp to 4.86% and the 10-year rose 12 bp to 5.10%, extending a selloff that also dragged European bonds lower. Existing home sales fell 5.5% m/m to a 3.75 million annualized rate, missing the 3.85 million consensus and confirming that 7.21% mortgage rates are freezing transactions.
Weekly jobless claims printed at 200,000 versus 195,000 expected, a modest but notable softening signal. The Monthly Budget Statement showed a $404 billion deficit, far wider than the $298.6 billion consensus, adding to the supply narrative behind the duration selloff. Crude inventories built sharply, with EIA crude up 4.657 million barrels and gasoline up 1.799 million barrels, while API had shown a 9 million barrel build the prior session.
Gold edged up 0.28% to $3,896 and Bitcoin fell 2.94%, while the dollar firmed against the euro and pound.
The Day Ahead
Markets will digest a heavy Fed speaker slate, with Bowman, Hammack, Barr, Goolsbee and Daly all on the calendar, giving investors a read on how officials are framing the inflation backdrop after recent above-forecast prints. Attention turns to whether policymakers acknowledge the housing deterioration evident in yesterday's sales collapse or maintain a hawkish tilt. Traders will also watch for any commentary on the balance sheet and reserve management following the New York Fed's confirmation of roughly $500 million in yen intervention funded from euro holdings.
With the 10-year at 5.10%, auction and supply headlines remain a live risk. No major top-tier data releases are scheduled, leaving Fed rhetoric as the primary catalyst.
Other Economic Notes
The housing channel is deteriorating faster than the broader economy, with existing home sales at 3.75 million and mortgage rates at 7.21% squeezing affordability. ↓ p.2