US Macro Daily(Beta Mode)
AI Selloff Deepens as Retail Sales Loom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,416.59 | -1.92% |
| Nasdaq 100 | 27,197.15 | -2.67% |
| Dow Jones | 51,608.17 | -1.41% |
| Russell 2000 | 2,742.94 | -1.70% |
| USD/JPY | 159.09 | -0.43% |
| EUR/USD | 1.10 | -0.25% |
| GBP/USD | 1.32 | -0.18% |
| Gold | 3,859.40 | +0.17% |
| WTI Crude | 86.07 | +0.41% |
| Bitcoin | 64,344.68 | -0.79% |
| US 2Y Treasury | 4.83% | -5 bp |
| US 10Y Treasury | 5.12% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Barr | - | - | - |
| NY Empire State Manufacturing Index | 25.50 | 18 | 7.80 |
| Speech by Fed's Williams | - | - | - |
| Fed Chair Warsh Speech | - | - | - |
| Speech by Fed's Barkin | - | - | - |
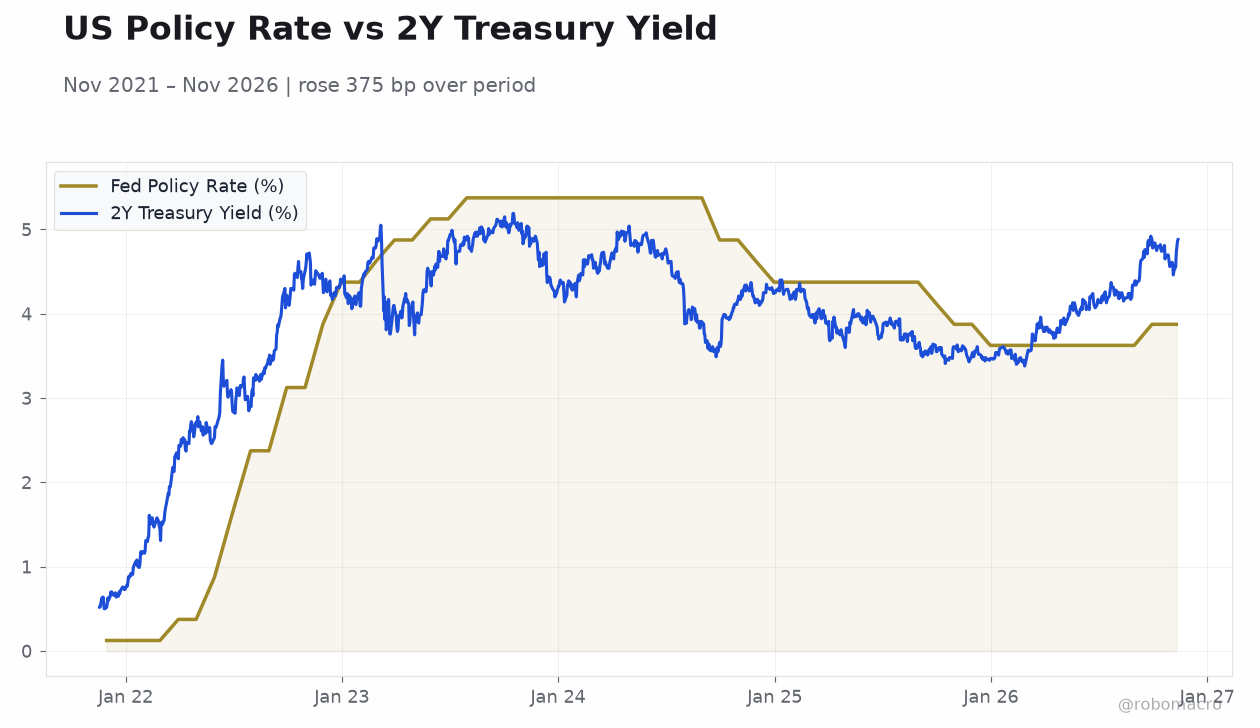 US Policy Rate vs 2Y Treasury Yield | Type: macro_line | Fed Policy Rate (%): 3.875 (2026-11-10) | Range: 0.125–5.375 | Trend(5pt): 0.125,4.625,5.375,4.375,3.875 | 2Y Treasury Yield (%): 4.88 (2026-11-13) | Range: 0.5–5.19 | Trend(6pt): 0.52,4.6,4.73,3.74,4.86,4.88
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Speech by Fed's Musalem | - | - | 07:30 |
| ADP Employment Change Weekly | 19,750 | - | 08:15 |
| Retail Sales Month-over-Month | 0.80 | 0.20 | 08:30 |
| Export Prices Month-over-Month | 2.20 | 0.30 | 08:30 |
| Import Prices Month-over-Month | 1.10 | 0.70 | 08:30 |
| Retail Sales Control Group Month-over-Month | 0.10 | 0.40 | 08:30 |
| Retail Sales Excluding Autos Month-over-Month | 0.90 | 0.40 | 08:30 |
| Industrial Production Month-over-Month | 0.70 | 0.10 | 09:15 |
| Speech by Fed's Waller | - | - | 09:20 |
| Fed Hammack Speech | - | - | 09:30 |
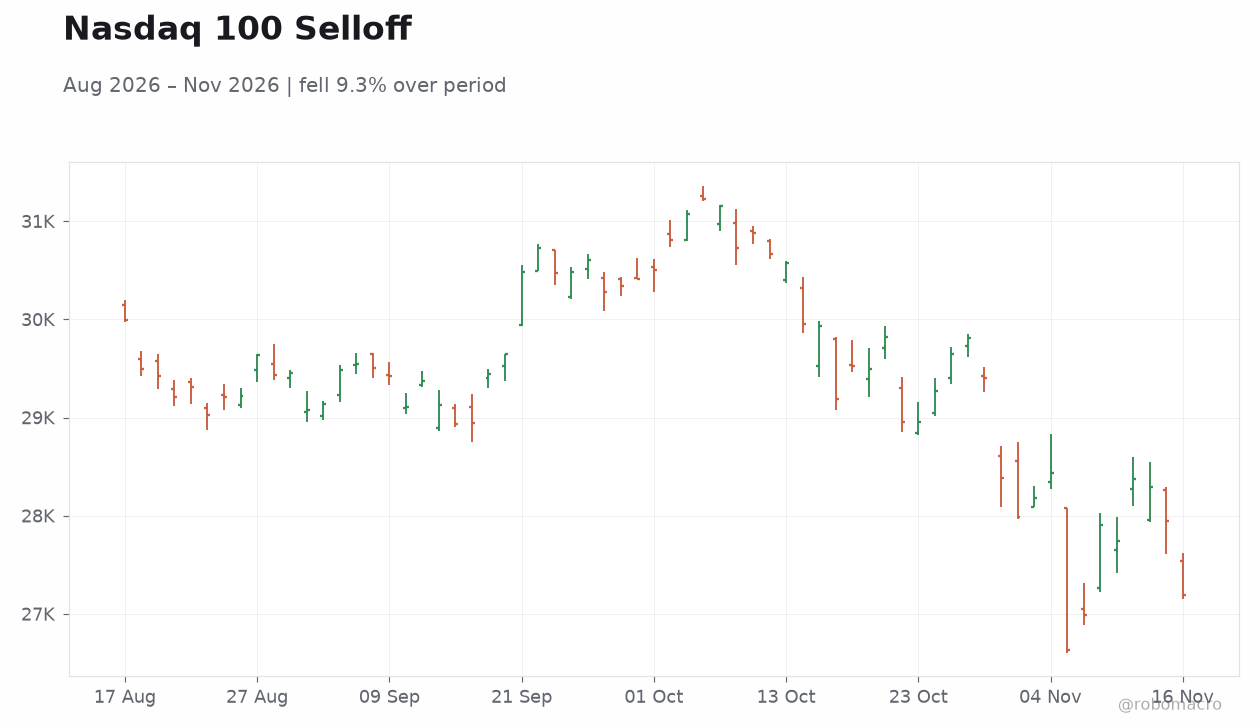
- Risk assets sold off sharply Monday, with the Nasdaq 100 down 2.67% and the S&P 500 off 1.92% as AI-linked names led losses ahead of Nvidia earnings.
- The NY Empire State Manufacturing Index plunged to 7.8 from 25.5, badly missing the 18 consensus, signaling a sharp regional factory slowdown.
- Attention turns to today's high-impact retail sales print (consensus +0.2% m/m) and a heavy Fed speaker slate including Waller and Hammack.
Yesterday's Recap
US equities suffered a broad risk-off session Monday, with the S&P 500 falling 1.92% to 7,416.59, the Nasdaq 100 dropping 2.67% to 27,197.15, and the Russell 2000 down 1.70%, as continued declines in Nvidia and other AI-linked stocks dragged the market lower. The Dow Jones Industrial Average fell 1.41% to 51,608.17. The NY Empire State Manufacturing Index printed at 7.8, far below the 18 consensus and down sharply from the prior 25.5, pointing to a marked cooling in regional factory activity.
Treasuries rallied modestly, with the 2-year yield easing 5 bp to 4.83% and the 10-year yield down 3 bp to 5.12%. The dollar firmed against major peers, with EUR/USD at 1.10 (-0.25%) and USD/JPY at 159.09 (-0.43%). Gold edged up 0.17% to $3,859.40, WTI crude rose 0.41% to $86.07, and Bitcoin slipped 0.79% to $64,344.68.
Fed speakers Barr, Williams, Chair Warsh, and Barkin were on the tape, with Warsh's remarks on AI's economic implications drawing particular attention.
The Day Ahead
The marquee release is November retail sales at 8:30 ET, where consensus looks for a 0.2% m/m headline slowdown from the prior 0.8%, with the control group expected at 0.4% and ex-autos at 0.4%. Import prices are seen at 0.7% m/m and export prices at 0.3% m/m, both well below prior readings, offering a read on pipeline inflation. Industrial production at 9:15 ET is expected to slow to 0.1% m/m from 0.7%.
ADP's weekly employment change at 8:15 ET provides a high-frequency labor read. On the speaker front, Musalem speaks at 7:30 ET, Waller at 9:20 ET, and Hammack at 9:30 ET, giving markets a dense Fed commentary slate into the December 9 FOMC.
Other Economic Notes
The Empire State collapse to 7.8 from 25.5 is a notable downside surprise that may temper optimism about manufacturing resilience, though one regional survey is not decisive. Retail sales remain the key test of consumer durability, with the control group consensus of 0.4% suggesting modest underlying momentum after the prior 0.1% print. ↓ p.2