US Macro Daily(Beta Mode)
Retail Sales Firm, Industrials Slump
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,340.53 | -1.03% |
| Nasdaq 100 | 27,001.78 | -0.72% |
| Dow Jones | 50,759.42 | -1.64% |
| Russell 2000 | 2,701.87 | -1.50% |
| USD/JPY | 159.26 | -0.16% |
| EUR/USD | 1.10 | -0.19% |
| GBP/USD | 1.32 | -0.08% |
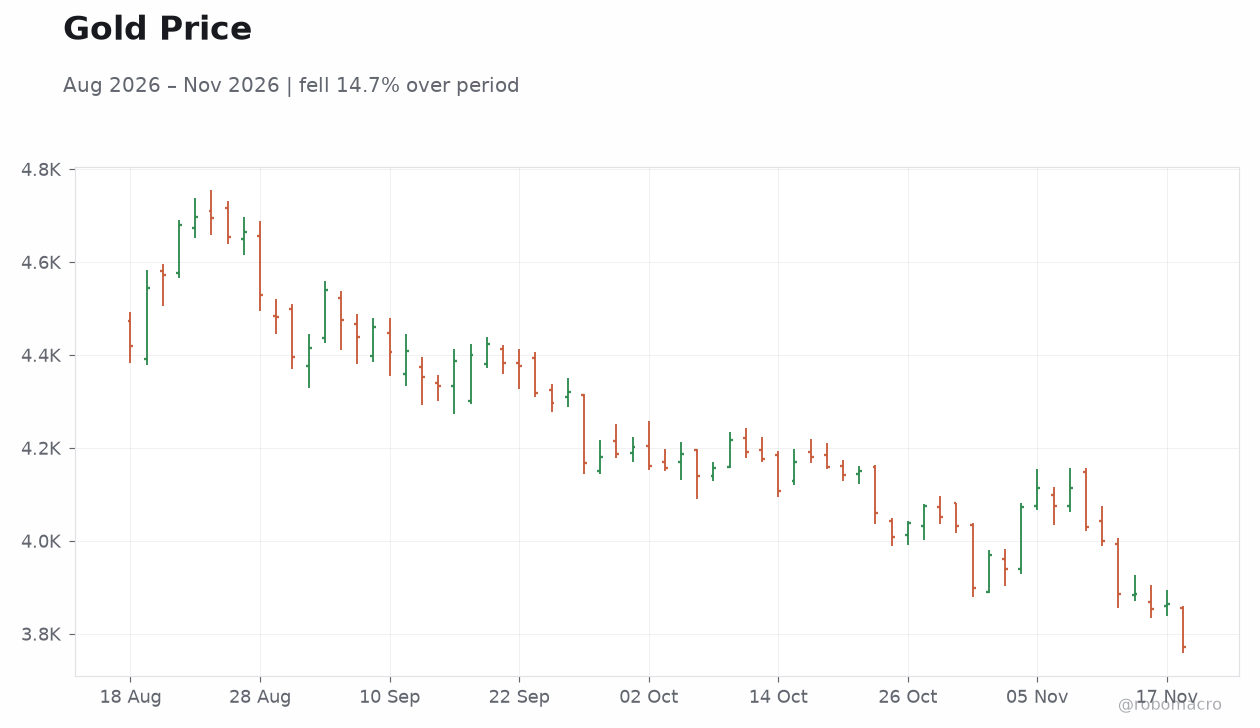
| Gold | 3,770.40 | -2.43% |
| WTI Crude | 83.21 | -3.26% |
| Bitcoin | 64,117.32 | -1.20% |
| US 2Y Treasury | 4.80% | -3 bp |
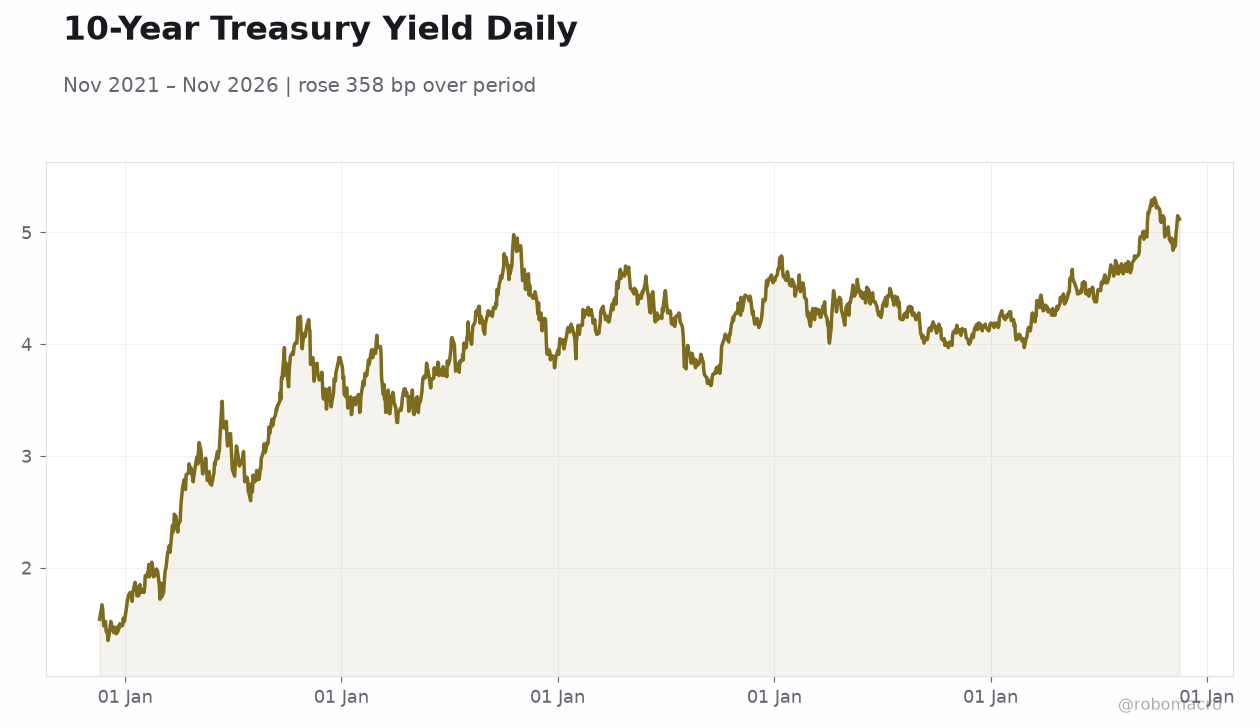
| US 10Y Treasury | 5.10% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Barkin | - | - | - |
| Speech by Fed's Musalem | - | - | - |
| ADP Employment Change Weekly | 19,750 | - | 23,750 |
| Retail Sales Month-over-Month | 0.80 | 0.20 | 0.20 |
| Export Prices Month-over-Month | 2.20 | 0.30 | 1.10 |
| Import Prices Month-over-Month | 1.10 | 0.70 | 1.10 |
| Retail Sales Control Group Month-over-Month | 0.10 | 0.40 | 0.60 |
| Retail Sales Excluding Autos Month-over-Month | 0.90 | 0.40 | 0.60 |
| Industrial Production Month-over-Month | 0.70 | 0.10 | -0.40 |
| Speech by Fed's Waller | - | - | - |
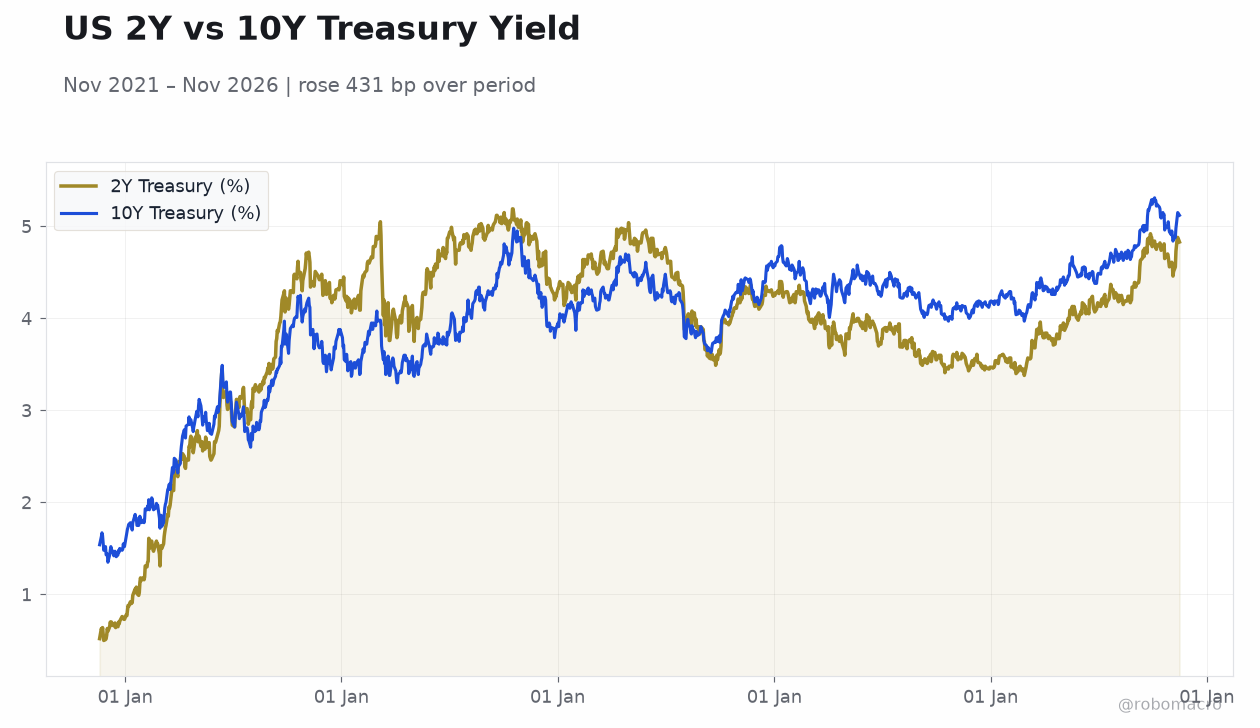 US 2Y vs 10Y Treasury Yield | Type: macro_line | 2Y Treasury (%): 4.83 (2026-11-16) | Range: 0.5–5.19 | Trend(6pt): 0.52,4.67,4.78,3.75,4.88,4.83 | 10Y Treasury (%): 5.12 (2026-11-16) | Range: 1.35–5.31 | Trend(6pt): 1.54,3.95,4.38,4.33,5.15,5.12
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| MBA 30-Year Mortgage Rate | 7.21 | - | 07:00 |
| Building Permits Prel | 1.4m | 1.4m | 08:30 |
| Housing Starts Level | 1.2m | 1.3m | 08:30 |
| Pending Home Sales Month-over-Month | -7.30 | -2.10 | 10:00 |
| Pending Home Sales Year-over-Year | -11.30 | - | 10:00 |
| EIA Weekly Crude Oil Inventory | 4.7m | - | 10:30 |
| EIA Weekly Gasoline Inventory | 1.8m | - | 10:30 |
| Speech by Fed's Barr | - | - | 13:35 |
| FOMC Meeting Minutes | - | - | 14:00 |
| Speech by Fed's Williams | - | - | 14:30 |
- Retail sales rose 0.2% m/m in October, in line with consensus, while the control group jumped 0.6% versus 0.4% expected, signaling resilient consumer demand.
- Industrial production fell 0.4% m/m, missing the 0.1% consensus, as manufacturing activity softened; NAHB housing sentiment dropped to 25 from 29.
- Equities sold off broadly, with the Dow down 1.64% and the S&P 500 off 1.03%, while Treasury yields eased modestly and gold plunged 2.43%.
Yesterday's Recap
US October retail sales printed at 0.2% m/m, matching consensus but slowing sharply from the prior 0.8% pace, while the control group rose 0.6% versus 0.4% expected and ex-autos came in at 0.6%. Industrial production contracted 0.4% m/m against a 0.1% consensus gain, a notable downside surprise pointing to softer factory activity. The NAHB housing market index fell to 25 from 29, undershooting consensus and signaling deepening stress in residential construction sentiment.
Import prices rose 1.1% m/m versus 0.7% expected, while export prices climbed 1.1%, both hotter than consensus and complicating the disinflation narrative. Business inventories rose 0.5% m/m, in line with expectations, and the Atlanta Fed GDPNow estimate edged down to 3.4% from 3.5%. Weekly ADP employment change came in at 23,750, up from the prior 19,750.
Markets reacted defensively: the Dow fell 1.64%, the Russell 2000 dropped 1.50%, and the S&P 500 lost 1.03%, while the 2-year Treasury yield eased 3 bp to 4.80% and the 10-year fell 2 bp to 5.10%. Gold tumbled 2.43% to $3,770/oz and WTI crude slid 3.26% to $83.21, with Bitcoin down 1.20%.
The Day Ahead
The US calendar for November 18 is light on tier-one data, with attention centered on Fed communications and any follow-through from yesterday's softer industrial and housing prints. Markets will parse remarks from regional Fed officials for signals on the December 9 FOMC decision, particularly given the recent hawkish tilt from St. Louis Fed President Musalem.
Housing-related sentiment remains fragile after the NAHB drop, keeping focus on whether residential weakness bleeds into broader activity. With the 10-year yield at 5.10% and equities testing technical support, traders will watch for any stabilization in risk appetite. No major Treasury auctions or inflation prints are scheduled, leaving positioning flows and Fed speak as the primary intraday catalysts.
Other Economic Notes
The mix of firm consumer spending and contracting industrial output paints a bifurcated picture of the US economy, with services and consumption holding up while goods-producing sectors weaken. ↓ p.2