US Macro Daily(Beta Mode)
AI Fears Hit Risk Assets as Fed Flags Overheating
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,175.83 | -2.02% |
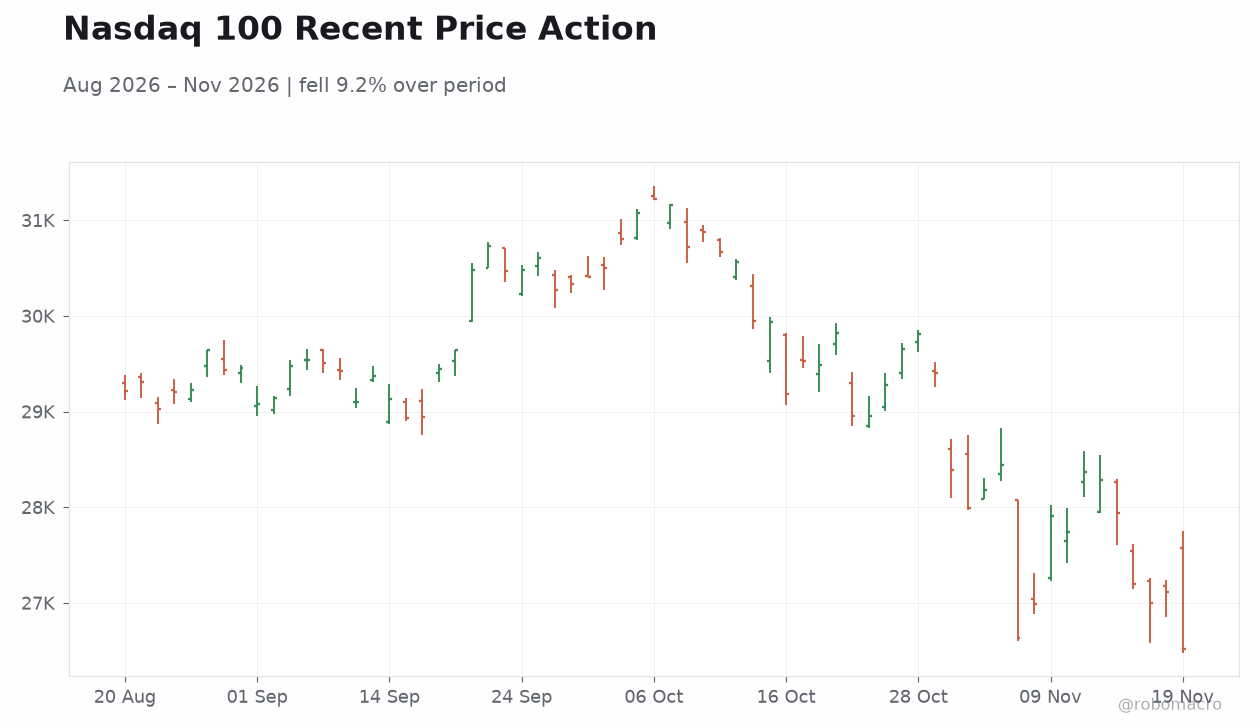
| Nasdaq 100 | 26,517.05 | -2.21% |
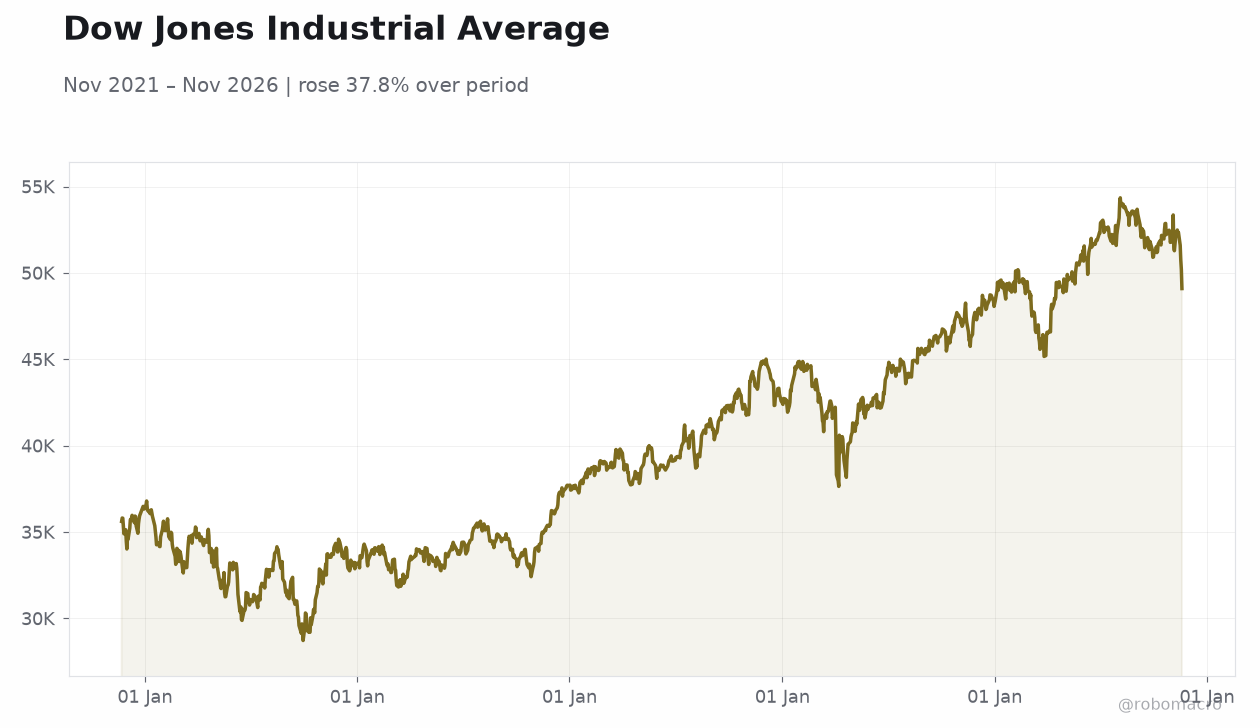
| Dow Jones | 49,097.06 | -2.19% |
| Russell 2000 | 2,655.11 | -2.18% |
| USD/JPY | 158.74 | -0.40% |
| EUR/USD | 1.10 | -0.04% |
| GBP/USD | 1.31 | -0.27% |
| Gold | 3,589.20 | -2.61% |
| WTI Crude | 81.84 | -1.65% |
| Bitcoin | 61,652.41 | -0.40% |
| US 2Y Treasury | 4.76% | -4 bp |
| US 10Y Treasury | 5.04% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Pending Home Sales Year-over-Year | -11.30 | - | -16.70 |
| EIA Weekly Crude Oil Inventory | 4.7m | - | 3.4m |
| EIA Weekly Gasoline Inventory | 1.8m | - | 5.2m |
| Atlanta Fed GDPNow | 3.40 | - | 3.20 |
| Speech by Fed's Barr | - | - | - |
| FOMC Meeting Minutes | - | - | - |
| Speech by Fed's Williams | - | - | - |
| Net Long-term TIC Flows | 279,200m | 160,700m | 155,300m |
| Philadelphia Fed Manufacturing Index | 20.90 | 20 | 6.30 |
| Weekly Jobless Claims | 200,000 | 197,000 | 203,000 |
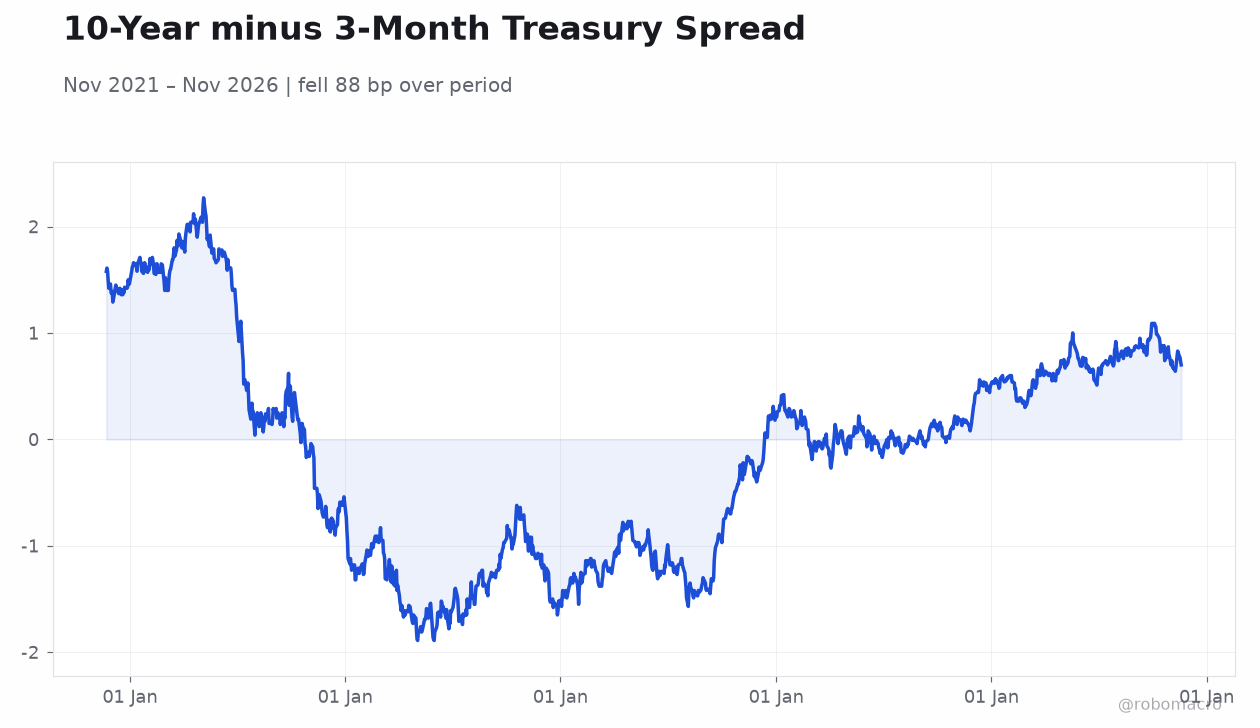
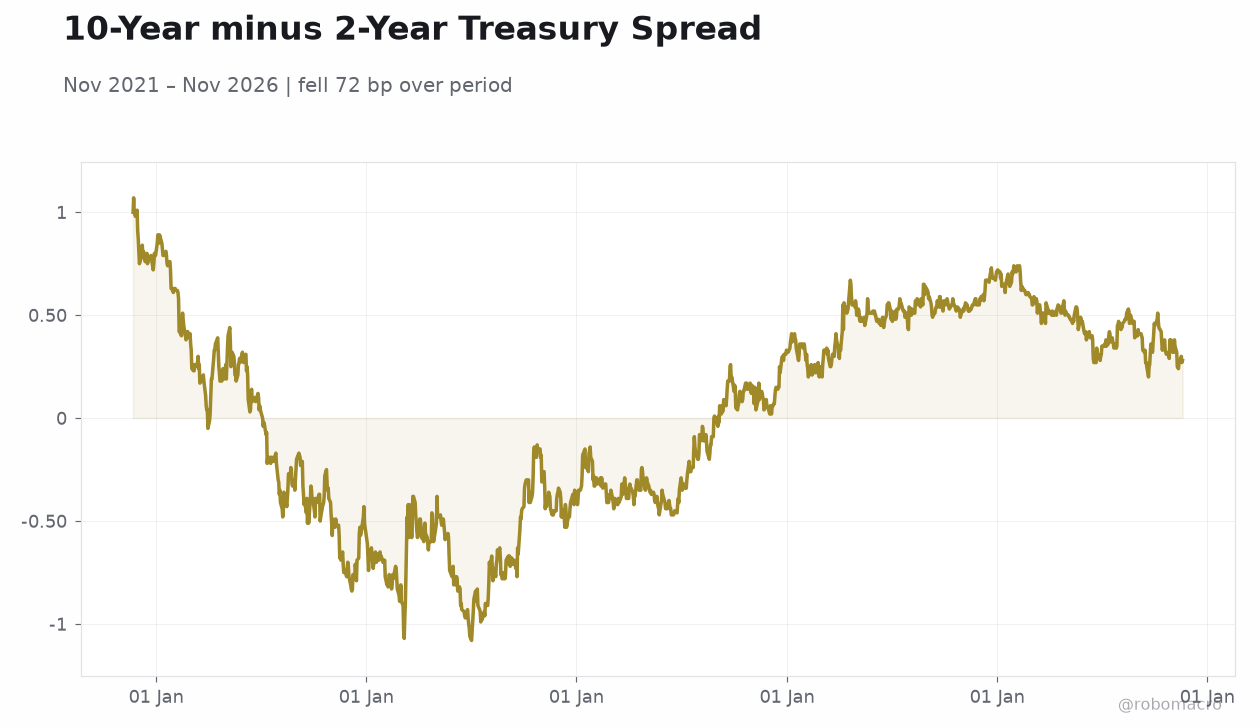 10-Year minus 2-Year Treasury Spread | Type: macro_line | 10-Year minus 2-Year Treasury Spread: 0.28 (2026-11-19) | Range: -1.08–1.07 | Trend(5pt): 1,-0.78,-0.41,0.54,0.28
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Speech by Fed's Waller | - | - | 08:25 |
| Michigan Consumer Sentiment Final | 48 | 51.50 | 10:00 |
| Fed Cook Speech | - | - | 12:15 |
- Equities sold off sharply, with the S&P 500 down 2.02% and Nasdaq 100 off 2.21%, as AI-linked anxiety and a soft Philadelphia Fed print weighed on sentiment.
- Fed October minutes showed widespread concern that an AI-driven demand surge could overheat the economy and strain capacity, reinforcing a hawkish policy backdrop.
- Treasury yields slipped modestly (10Y to 5.04%, 2Y to 4.76%) in a risk-off bid, while gold fell 2.61% and WTI dropped 1.65%.
Yesterday's Recap
US equities suffered a broad risk-off session Thursday, with the S&P 500 falling 2.02% to 7,175.83, the Nasdaq 100 dropping 2.21%, and the Dow and Russell 2000 each down roughly 2.2%. The Philadelphia Fed Manufacturing Index collapsed to 6.3 from a prior 20.9 and well below the 20 consensus, signaling a sharp regional slowdown. Weekly jobless claims rose to 203,000 versus 197,000 expected, a modest labor-market softening.
Pending home sales year-over-year plunged to -16.7% from -11.3%, underscoring housing weakness under elevated rates. The Atlanta Fed GDPNow estimate eased to 3.2% from 3.4%. EIA data showed crude inventories up 3.38 million barrels and gasoline up 5.192 million barrels, pressuring energy.
Net long-term TIC flows came in at $155.3 billion, below the $160.7 billion consensus. Treasuries rallied modestly, with the 10-year yield easing 3 bp to 5.04% and the 2-year down 4 bp to 4.76%.
The Day Ahead
Friday's calendar is dominated by Fed speakers rather than top-tier data. Waller speaks at 8:25 ET, with markets attentive to whether he reinforces a hawkish December stance. Additional Fed communications are scheduled through the morning and afternoon, keeping policy messaging in focus.
The Michigan Consumer Sentiment Final is also due at 10:00 ET. With no major first-tier releases on deck beyond that, traders will parse speaker tone for signals on the December 9 FOMC. Positioning into the weekend may amplify volatility given Thursday's sharp equity drawdown.
Watch for any commentary on AI-driven demand and capacity constraints following the October minutes.
Other Economic Notes
The October FOMC minutes revealed near-universal concern among officials that an AI investment boom could overheat the economy if investor enthusiasm disappoints, a theme echoed publicly by Goolsbee. Housing remains a clear weak spot, with pending sales contracting 16.7% year-over-year as mortgage costs track elevated Treasury yields. ↓ p.2