RoboMacro AI Economic Research

Global Macro Watch

BETA
June 28, 2026 robomacro.com
Global Macro Watch
June 28, 2026
  • US S&P Global Manufacturing PMI Flash beat and Core PCE alignment anchored Fed OIS curves to no cut before mid-2027.
  • Brent crude fell 6.8 percent to 72.60, extending disinflationary pressure across commodity-linked economies.
  • DM central banks reinforced data dependence, with BoJ tightening signals and BoC/Banxico holds limiting near-term easing.
  • Equities rotated lower in tech and Asia while DXY rose 0.5 percent to 101.36, tightening global financial conditions.
US Resilience Delays Global Rate-Cut Hopes

US Activity Resilience Anchors Global Cycle Expectations

The global economic cycle remains in mid-expansion as of the week ending June 28, 2026. US data resilience has emerged as the dominant narrative, overriding further oil-price relief and re-anchoring policy expectations higher. We note that the S&P Global Manufacturing PMI Flash rose and beat consensus while Core PCE matched expectations, confirming activity strength that shifted market pricing for the first Fed cut to no earlier than mid-2027. This repricing occurred even as New Home Sales declined month-over-month, highlighting housing sensitivity to elevated mortgage rates. The combination leaves the expansion intact but tilts financial conditions tighter through the dollar channel rather than through outright contraction signals. Markets therefore enter July 2026 with clearer evidence that above-target US inflation will continue to shape global rate paths into the second half of the year.

Developed Market Divergence Highlights Selective Resilience

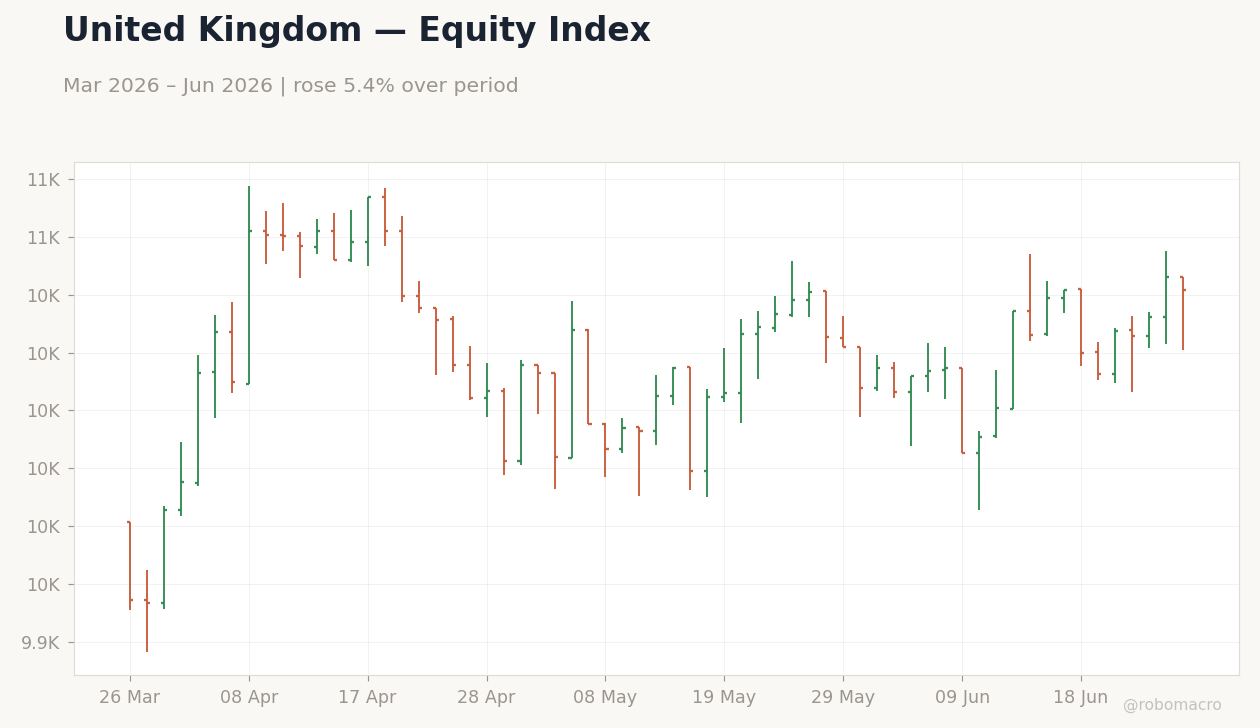
Across developed markets the read-through centers on selective resilience and shared data dependence. US industrial momentum contrasted with euro-area splits, where French S&P Global Composite PMI Flash rose while German Composite fell, confirming regional divergence inside the single currency bloc. Japanese Flash PMIs delivered clear beats that reinforced private-sector momentum into the second half, lifting 10-year JGB yields and keeping OIS pricing tilted toward additional BoJ adjustment. In the United Kingdom, Flash PMIs delivered the clearest downside surprise as services contracted, yet the FTSE 100 still closed at 10508.0 after a 0.67 percent gain. Canadian May CPI rose more than expected to a multi-month high, prompting the Bank of Canada to hold the policy rate unchanged with OIS-implied easing limited by year-end. The common thread is that DM central banks are tolerating above-target prints to support growth, with OIS curves showing only limited near-term repricing after the June 28 data flow.
Join the AIeconomist.app Waitlist

Published every Sunday afternoon 100% AI-generated — not financial advice
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com

US Activity Resilience Anchors Global Cycle Expectations

The global economic cycle remains in mid-expansion as of the week ending June 28, 2026. US data resilience has emerged as the dominant narrative, overriding further oil-price relief and re-anchoring policy expectations higher. We note that the S&P Global Manufacturing PMI Flash rose and beat consensus while Core PCE matched expectations, confirming activity strength that shifted market pricing for the first Fed cut to no earlier than mid-2027. This repricing occurred even as New Home Sales declined month-over-month, highlighting housing sensitivity to elevated mortgage rates. The combination leaves the expansion intact but tilts financial conditions tighter through the dollar channel rather than through outright contraction signals. Markets therefore enter July 2026 with clearer evidence that above-target US inflation will continue to shape global rate paths into the second half of the year.
Developed Market Divergence Highlights Selective Resilience

Across developed markets the read-through centers on selective resilience and shared data dependence. US industrial momentum contrasted with euro-area splits, where French S&P Global Composite PMI Flash rose while German Composite fell, confirming regional divergence inside the single currency bloc. Japanese Flash PMIs delivered clear beats that reinforced private-sector momentum into the second half, lifting 10-year JGB yields and keeping OIS pricing tilted toward additional BoJ adjustment. In the United Kingdom, Flash PMIs delivered the clearest downside surprise as services contracted, yet the FTSE 100 still closed at 10508.0 after a 0.67 percent gain. Canadian May CPI rose more than expected to a multi-month high, prompting the Bank of Canada to hold the policy rate unchanged with OIS-implied easing limited by year-end. The common thread is that DM central banks are tolerating above-target prints to support growth, with OIS curves showing only limited near-term repricing after the June 28 data flow.

Emerging Markets Split Along Commodity and Policy Lines

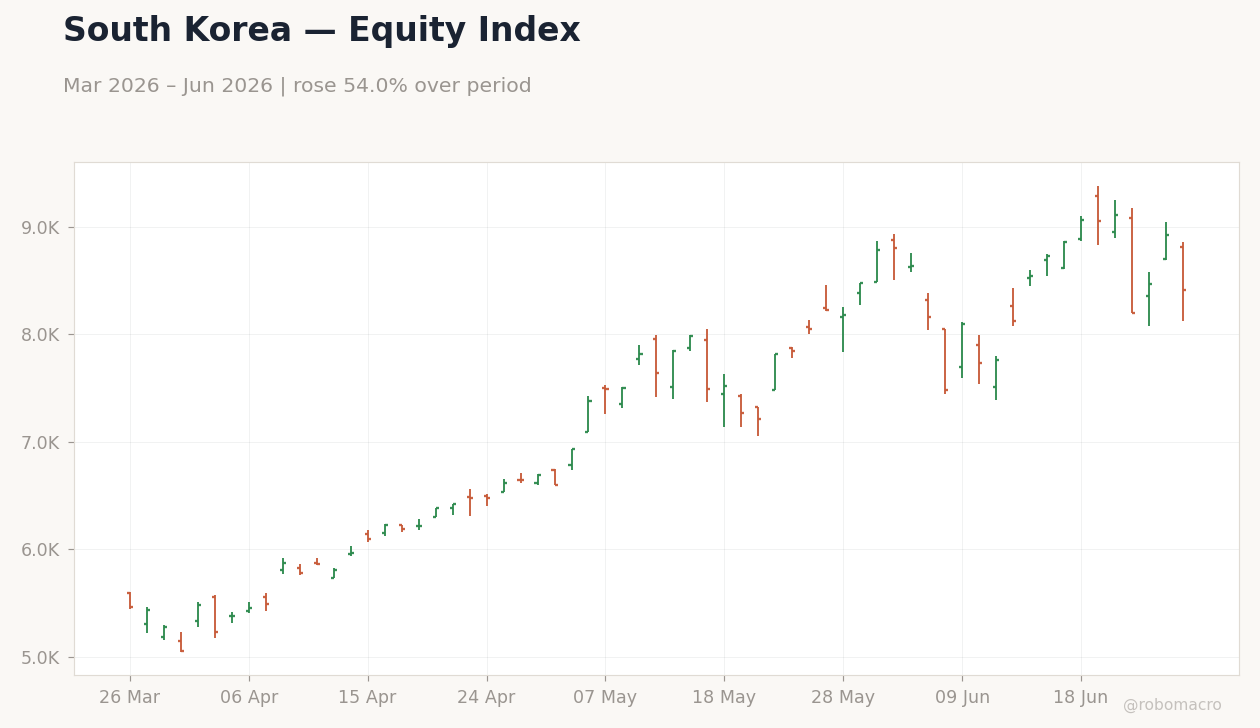
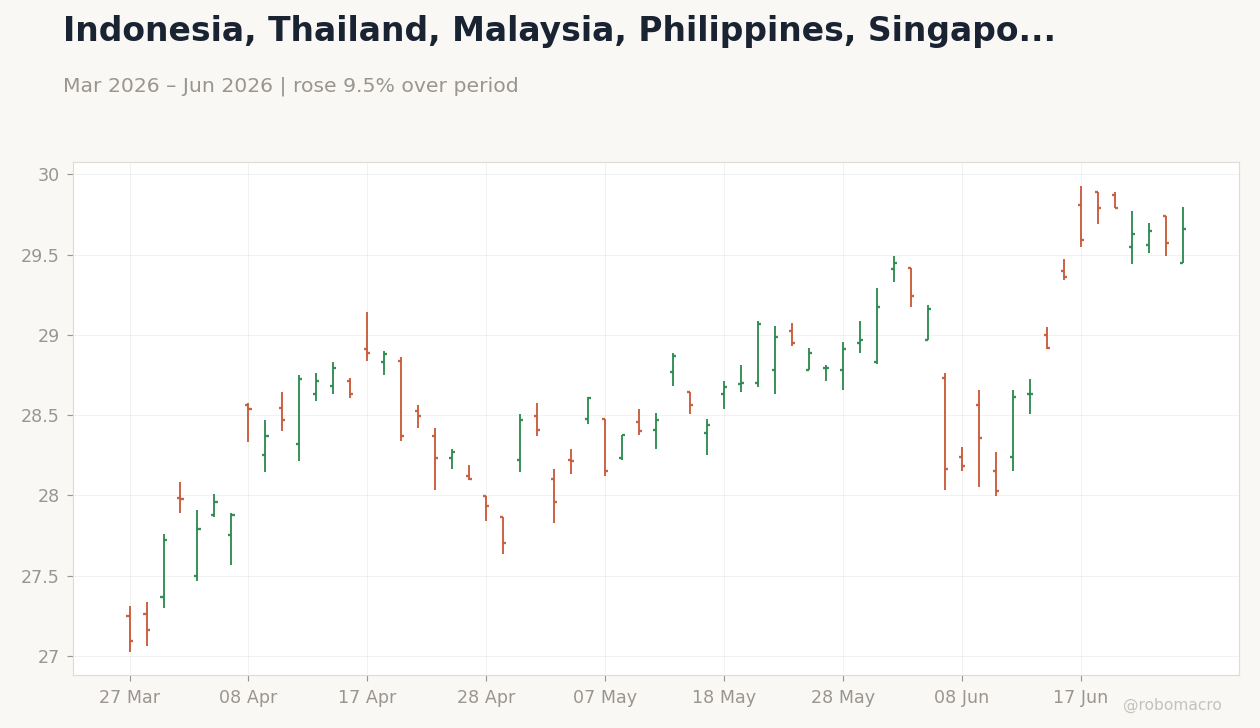
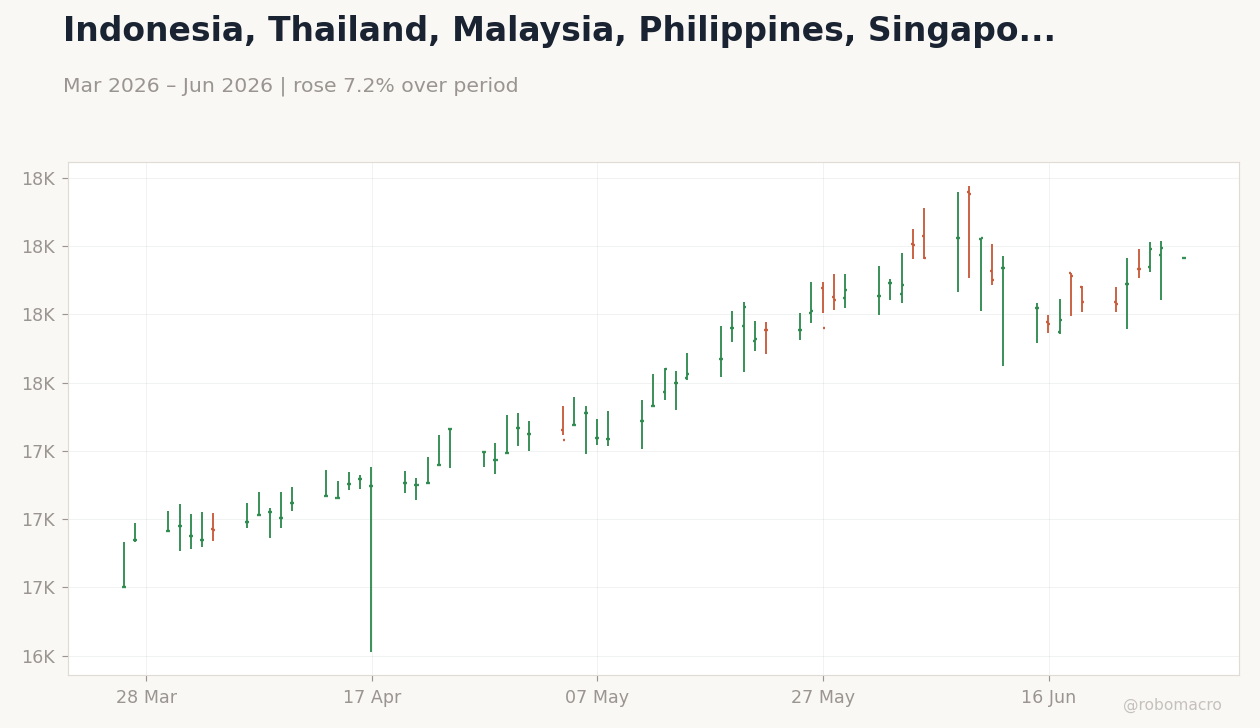
Emerging-market outcomes diverged between domestic inflation surprises and external commodity exposure. Mexico’s inflation eased more than expected, allowing Banxico to hold the policy rate steady with OIS curves pricing only limited near-term cuts, while the May trade balance missed consensus. Brazil’s Bovespa rose 1.72 percent week-over-week even as WTI Crude fell 7.47 percent, illustrating selective equity gains amid commodity weakness. In Asia, Bank Indonesia delivered an additional rate hike while the rupiah traded near 17957, and the Bank of Thailand held its policy rate while revising its 2026 GDP forecast higher. Regional equities posted sharp weekly losses, with the KOSPI declining 7.72 percent to 8411.21 and the Hang Seng falling 4.61 percent to 22671.86. The pattern is one of selective domestic policy tightening offset by dollar-driven pressure on external balances after the June 28 commodity moves.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com

Cross-Asset Markets Signal Persistent Dollar Strength

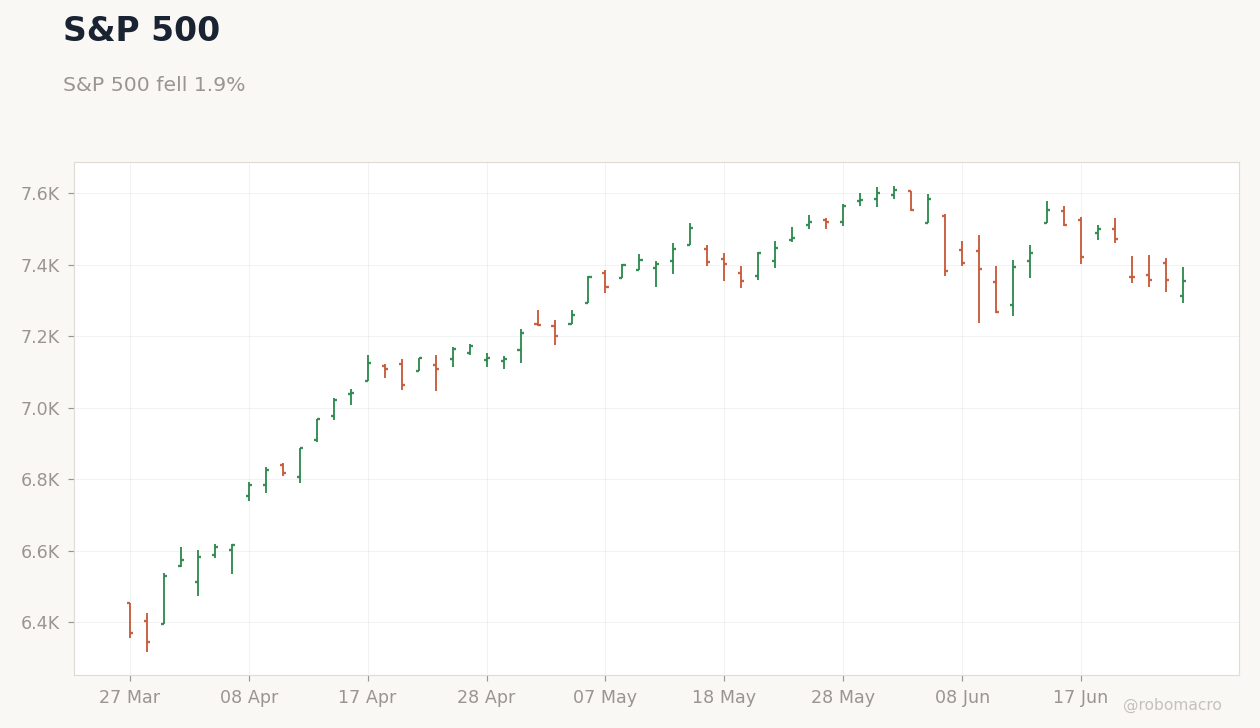
Cross-asset price action reflected the higher-for-longer US narrative and commodity weakness. The Nasdaq 100 declined 4.2 percent while the S&P 500 fell 1.9 percent to 7354, pointing to rotation out of growth-sensitive assets. Brent crude’s 6.8 percent drop to 72.60 reinforced external disinflation impulses that supported lower European yields, with German 10-year Bunds falling 14 basis points to 2.85 percent. The DXY rose 0.5 percent to 101.36, lifting USD/JPY to 161.73 and pressuring AUD/USD down 1.45 percent to 0.69. Equity markets in commodity-exposed regions mirrored the energy decline, with the JSE Top 40 falling 2.24 percent to 58.99 and MSCI Chile declining 3.16 percent. This configuration indicates that financial conditions are tightening through the currency and commodity channels rather than through synchronized equity or bond-market stress.

Central Bank Paths Diverge on Inflation Tolerance

Global central-bank landscapes show clear rate-path divergences driven by domestic inflation tolerance. The Fed’s June communications left OIS curves anchored to the prevailing funds rate through the summer, while the BoJ reinforced expectations for further tightening after the PMI beats. In contrast, the Riksbank minutes revealed internal divisions on easing pace amid higher Swedish producer prices, leaving OIS curves with limited near-term repricing. Emerging-market banks split between Bank Indonesia’s hike and the Bank of Thailand’s hold, both of which kept regional OIS curves little changed after the June 28 data. The overarching policy outlook is one of measured patience, with most committees prioritizing data dependence over pre-emptive easing even as external price relief continues.

Key Releases to Shape July Policy Bets

Next week’s calendar features US employment and ISM data that will test whether the mid-2027 cut pricing remains intact. Euro-area final PMIs and German Ifo releases will clarify whether the observed regional divergence persists. In emerging markets, focus will fall on Brazilian and Mexican inflation prints alongside any follow-through from Bank Indonesia’s recent tightening. Commodity and FX volatility around the July 4 holiday will also influence positioning, particularly in energy-sensitive currencies and equity indices. Markets will therefore watch whether the US resilience narrative extends or whether fresh data finally reopen space for earlier global easing.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Global Economic Outlook Summary
Consensus forecasts, % change year-on-year. Sources: IMF WEO, OECD, World Bank, national central bank projections. Generated by xAI Grok from public institutional data as of June 28, 2026.
Economy Real GDP (% y/y) Consumer Prices (% y/y)
2026E2027E2028E 2026E 2027E2028E
Americas
United States2.01.81.72.32.22.1
Canada1.71.91.82.12.02.0
Mexico2.02.22.13.53.33.2
Brazil2.32.42.34.03.73.5
Argentina3.84.23.542.028.018.0
Colombia2.83.02.94.23.83.5
Chile2.42.62.53.33.13.0
Peru2.72.92.82.82.62.5
Asia / Pacific
Japan1.00.90.81.31.21.1
China4.64.34.11.61.82.0
India6.36.26.14.54.34.2
Australia2.22.32.22.52.42.3
New Zealand2.02.12.02.32.22.1
South Korea2.12.22.12.02.02.0
Indonesia5.05.15.02.82.72.6
Malaysia4.44.54.42.52.42.3
Philippines5.85.95.83.23.13.0
Singapore2.82.92.82.22.12.0
Thailand2.93.02.91.81.92.0
Taiwan2.52.62.51.92.02.0
Vietnam6.56.46.33.53.43.3
Western Europe
Euro area1.31.41.32.01.91.9
Germany1.01.21.12.12.02.0
France1.21.31.21.91.81.8
Italy0.80.90.81.81.71.7
Spain2.01.91.82.32.22.1
United Kingdom1.41.51.42.42.22.1
Sweden1.82.01.92.02.02.0
Norway1.61.71.62.22.12.0
Denmark1.51.61.52.02.02.0
Switzerland1.31.41.31.01.11.2
Netherlands1.61.71.62.12.02.0
Poland3.33.23.13.53.02.8
Czech Republic2.42.52.42.52.32.2
Hungary2.82.92.83.83.33.0
Romania3.03.13.04.03.53.2
EMEA Emerging
Turkey3.23.43.328.018.012.0
South Africa1.51.81.94.84.54.3
Israel3.53.43.32.82.62.5
Saudi Arabia3.83.63.52.22.12.0
UAE4.24.03.92.02.02.0
Egypt4.04.54.322.015.010.0
Nigeria3.23.53.624.018.014.0
Kenya5.25.35.25.55.04.8
Global Aggregates
Global3.23.13.03.63.33.1
Developed markets1.71.71.62.12.02.0
Emerging markets4.14.03.95.24.64.2
E = estimate/forecast. Sources: IMF WEO, OECD Economic Outlook, World Bank GEP, FOMC SEP, ECB staff projections, national MPRs. Median consensus where sources diverge. Data synthesised by Grok from publicly available institutional forecasts.
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Global Central Bank Watch
Policy rates and quarterly forecasts as of June 28, 2026. Sources: central bank official releases, OIS market pricing, consensus surveys.
Central Bank Instrument Current
Rate
Last
Change
bp Next
Meeting
Expected
Move
Q1
2026
Q2
2026
Q3
2026
Q4
2026
The Americas
Federal ReserveFed funds upper3.75%Jun 2025-25Jul 29Hold4.003.753.503.25
Bank of CanadaO/N rate2.75%Apr 2026-25Jul 15Hold3.253.002.752.50
BCB (Brazil)SELIC9.50%May 2026-50Jul 30-25bp10.5010.009.509.00
BanxicoO/N rate7.75%Mar 2026-50Aug 6Hold8.758.257.757.25
BCRA (Argentina)Repo rate32.00%Jun 2026-500Jul 16-500bp42.0037.0032.0028.00
BanRep (Colombia)Repo8.75%Apr 2026-50Jul 31-25bp9.759.258.758.25
BCCh (Chile)MPR4.75%Jun 2026-25Jul 29Hold5.505.004.754.50
Europe / Africa
ECBDepo rate2.25%Jun 2026-25Jul 23Hold2.752.502.252.00
Bank of EnglandBank rate4.00%May 2026-25Aug 6Hold4.504.254.003.75
RiksbankRepo rate2.00%Jun 2026-25Sep 3Hold2.502.252.001.75
Norges BankDep rate4.00%Jun 2026-25Aug 20Hold4.504.254.003.75
SNBPolicy rate0.25%Mar 2026-25Sep 17Hold0.750.500.250.00
CNB (Czech)2-wk repo3.25%May 2026-25Aug 6Hold3.753.503.253.00
NBH (Hungary)Base rate6.00%Jun 2026-25Jul 22-25bp6.756.506.005.50
NBP (Poland)Ref rate5.25%Apr 2026-25Sep 3Hold5.755.505.255.00
SARBRepo rate7.00%May 2026-25Jul 23Hold7.507.257.006.75
CBRT (Turkey)1-wk repo42.50%Jun 2026-250Jul 23-250bp47.5045.0042.5040.00
Asia / Pacific
RBACash rate3.60%May 2026-25Aug 4Hold4.103.853.603.35
RBNZOCR3.00%May 2026-25Aug 19Hold3.503.253.002.75
BoJPol rate0.50%Jun 2026+25Jul 30Hold0.250.500.500.75
PBoC1-yr LPR3.10%Feb 2026-10Jul 15Hold3.203.153.103.05
RBI (India)Repo rate6.00%Apr 2026-25Aug 6Hold6.256.256.005.75
BoK (Korea)Base rate2.75%May 2026-25Jul 16Hold3.253.002.752.50
BI (Indonesia)BI-Rate5.50%Apr 2026-25Jul 16Hold5.755.755.505.25
BSP (Philippines)Rev repo5.25%Jun 2026-25Aug 13Hold5.755.505.255.00
BoT (Thailand)1-day repo1.75%Apr 2026-25Aug 6Hold2.252.001.751.50
CBC (Taiwan)Disc rate2.00%Jun 2026-12.5Sep 17Hold2.252.132.001.88
MAS (Singapore)SGD NEER0% slope%Apr 20260Oct 2026Hold0% slope0% slope0% slope-0.5% slope
Rate forecasts: OIS market pricing + central bank forward guidance + consensus surveys. Generated by xAI Grok from publicly available sources. Shaded rows denote regional groupings. Data as of June 28, 2026.
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewRates & Fixed Income
Rates & Fixed Income Chart 1
Rates & Fixed Income Chart 2
Rates & Fixed Income Chart 3
Rates & Fixed Income Chart 4

Week in Review

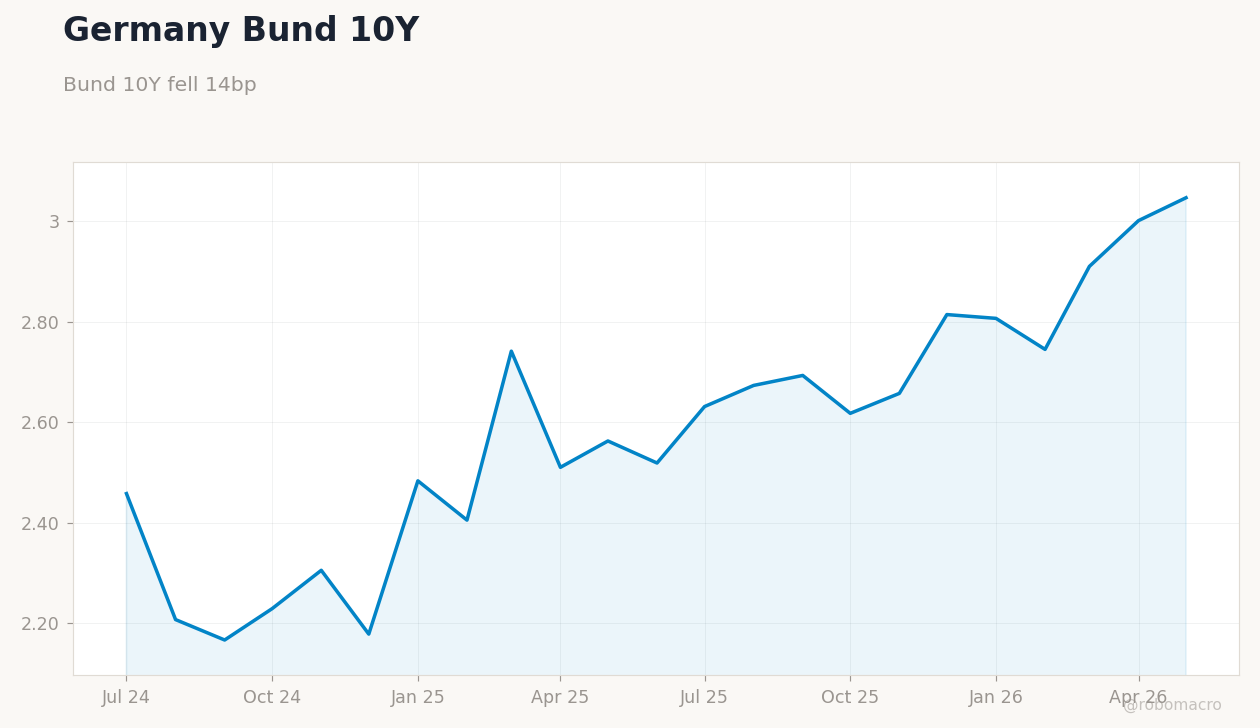
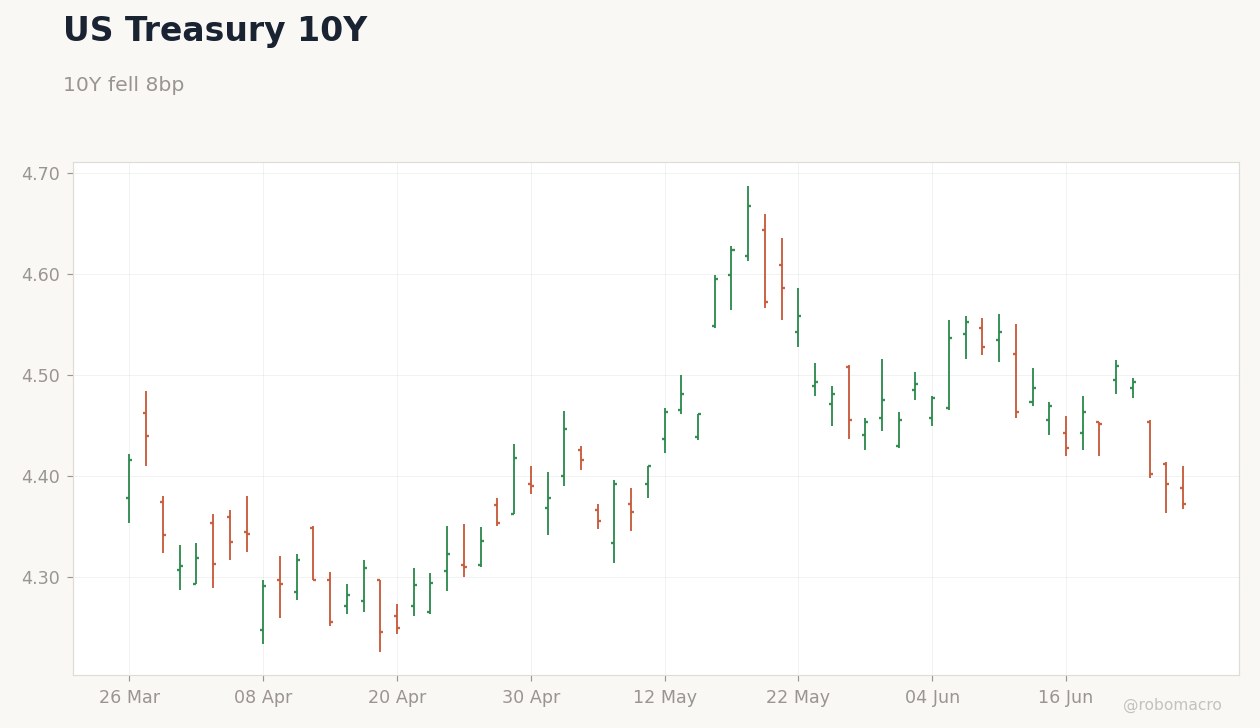
German 10-year Bund yields fell the most among major DM markets, declining 14bp to 2.85%. U.S. Treasury 10-year yields fell 8bp to 4.37%, while U.K. 10-year gilt yields dropped 11bp to 4.73%. Japanese 10-year JGB yields eased 4bp to 2.60%. The decline in U.S. yields unfolded steadily, with the 10-year moving from 4.5090 on Monday to 4.4930 on Tuesday, 4.4020 on Wednesday, 4.3920 on Thursday, and closing at 4.3720 on Friday. Similar downward pressure was evident in the 5-year yield, which fell from 4.2870 to 4.1300 over the same period. This broad-based decline in yields came amid easing geopolitical tensions and falling oil prices.

Curve & Spreads

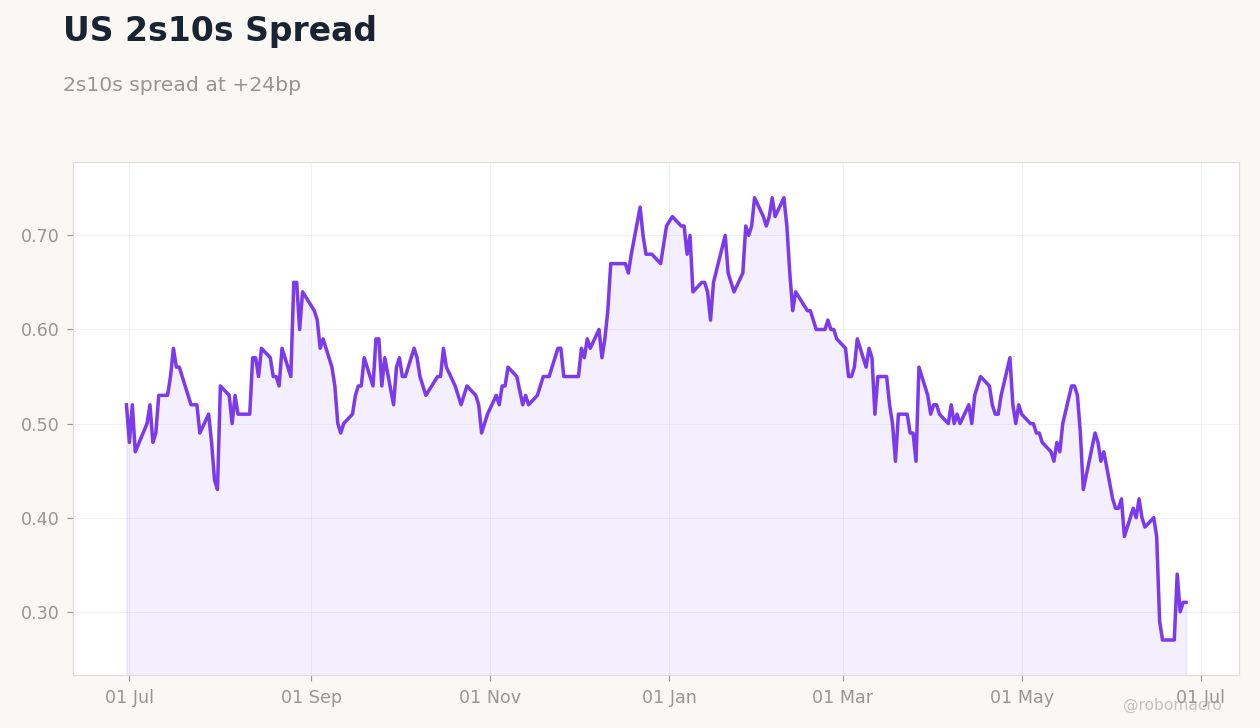
The U.S. 2s10s spread stands at +24bp, narrower than Germany's +33bp and the U.K.'s +59bp. This flatter curve in the U.S. relative to European peers points to more cautious growth expectations. In contrast, the steeper curves in the U.K. and Germany suggest relatively better growth outlooks. The curve shape overall implies tempered expectations for economic expansion in the near term.

EM Bonds

In emerging markets, Brazilian 10-year yields stand at 14.47% while Turkish 10-year yields are at 33.23%. South African 10-year yields closed at 8.34% and Indonesian 10-year yields at 7.18%. These levels remain markedly higher than DM counterparts such as the U.S. at 4.37% and Germany at 2.85%, reflecting substantial spread differentials. Turkish yields moved significantly lower on the week, contrasting with more modest moves in DM rates.

Central Bank Read

Front-end yields fell broadly in line with or slightly more than back-end rates across major markets. In the U.S., the 2-year yield declined 9bp versus 8bp for the 10-year, while in Germany the 2-year fell 13bp against a 14bp drop in the 10-year. The U.K. saw larger front-end easing with the 2-year down 14bp compared to 11bp for the 10-year. These moves leave the curve implying an easing bias in policy expectations. In Japan, the front end edged higher while the back end fell, suggesting the curve implies a tightening bias from the BoJ.

Week Ahead

Attention turns to central bank meetings from the Fed, ECB, BoE and BoJ. Treasury auctions will provide technical cues on demand for duration. These events matter most for duration risk as they will shape views on policy paths. Any accompanying CPI or GDP releases could also influence growth expectations and bond positioning.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewFixed Income
Global Government Bond Yields
Yields in %. WoW change in basis points. Source: CBOE/yfinance (US), FinanceFlowAPI (international).
Country2Y2Y WoW10Y10Y WoW30Y30Y WoW2s10s
United States4.13%-9bp4.37%-8bp4.86%-4bp+24bp
United Kingdom4.14%-14bp4.73%-11bp5.45%-9bp+59bp
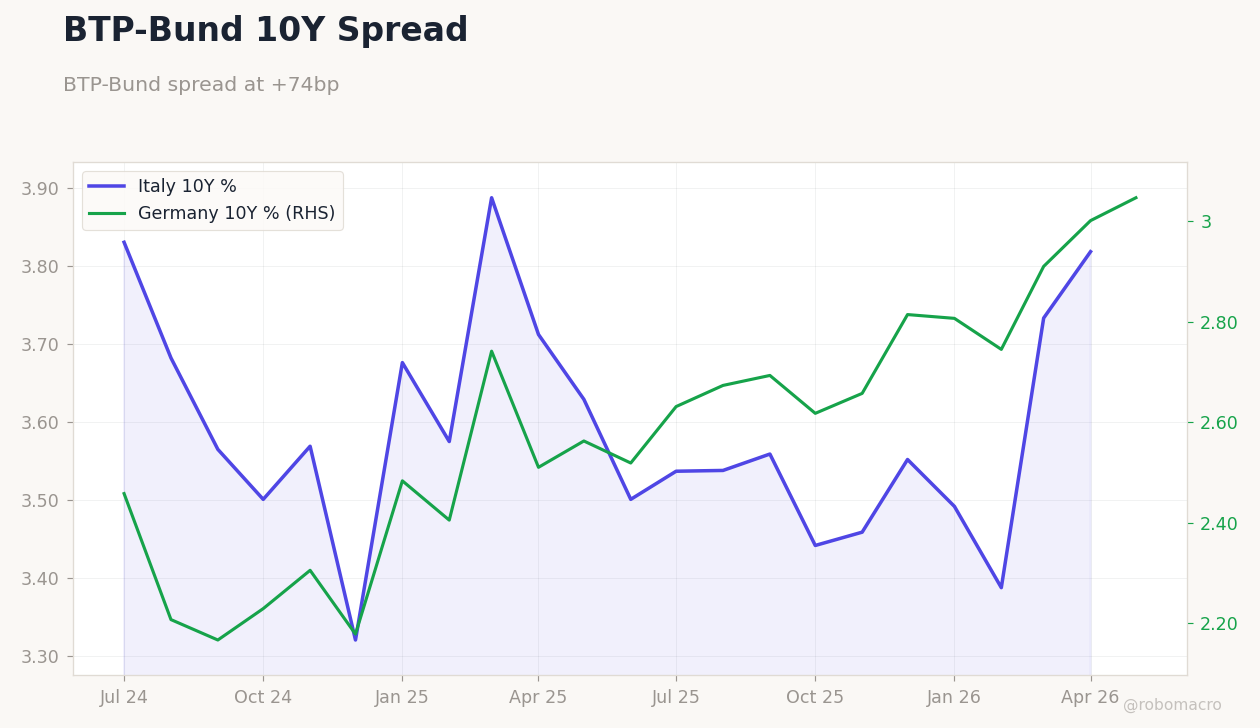
Germany2.52%-13bp2.85%-14bp3.41%-13bp+33bp
France2.69%-12bp3.52%-11bp4.42%-10bp+83bp
Italy2.69%-13bp3.59%-13bp4.46%-10bp+90bp
Spain2.60%-14bp3.35%-11bp4.06%-11bp+74bp
Japan1.41%+1bp2.60%-4bp3.80%-4bp+119bp
Canada2.75%-3bp3.39%-1bp3.79%-2bp+64bp
Australia4.47%-7bp4.76%-7bp5.27%-4bp+29bp
China1.24%-0bp1.73%+0bp2.22%-0bp+50bp
India5.97%-9bp6.77%-7bp7.37%-11bp+80bp
Brazil14.18%-64bp14.47%-35bp——+29bp
Mexico——8.91%-4bp———
South Korea3.65%+2bp4.14%-5bp4.34%+8bp+48bp
Indonesia——7.18%+11bp7.17%-29bp—
Turkey40.54%-68bp33.23%-20bp——-731bp
South Africa——8.34%-14bp8.78%-15bp—
Poland——5.30%-15bp———

Government bond yields fell across most major markets. Turkey’s 2Y led declines, dropping 68bp to 40.54%, while Brazil’s 2Y fell 64bp to 14.18%. The UK 2Y eased 14bp to 4.14% and Germany’s 10Y declined 14bp to 2.85%. US 2Y and 10Y yields fell 9bp and 8bp to 4.13% and 4.37%. Curves steepened, with the US 2s10s widening 24bp and Japan’s reaching +119bp. Indonesia’s 10Y rose 11bp, the sole notable increase, while China yields were unchanged. Next week’s focus turns to G10 inflation data and ECB, BoE and Fed speeches.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewGlobal Equities
Global Equities Chart 1
Global Equities Chart 2
Global Equities Chart 3
Global Equities Chart 4

Week in Review

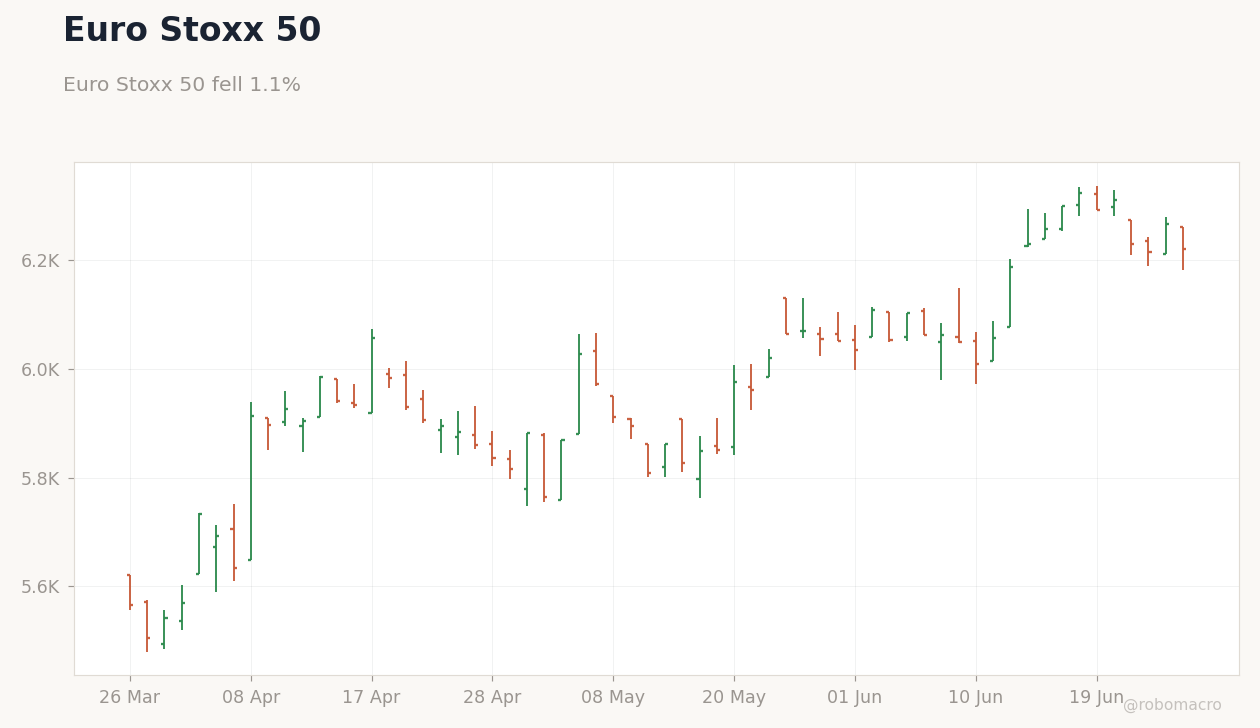
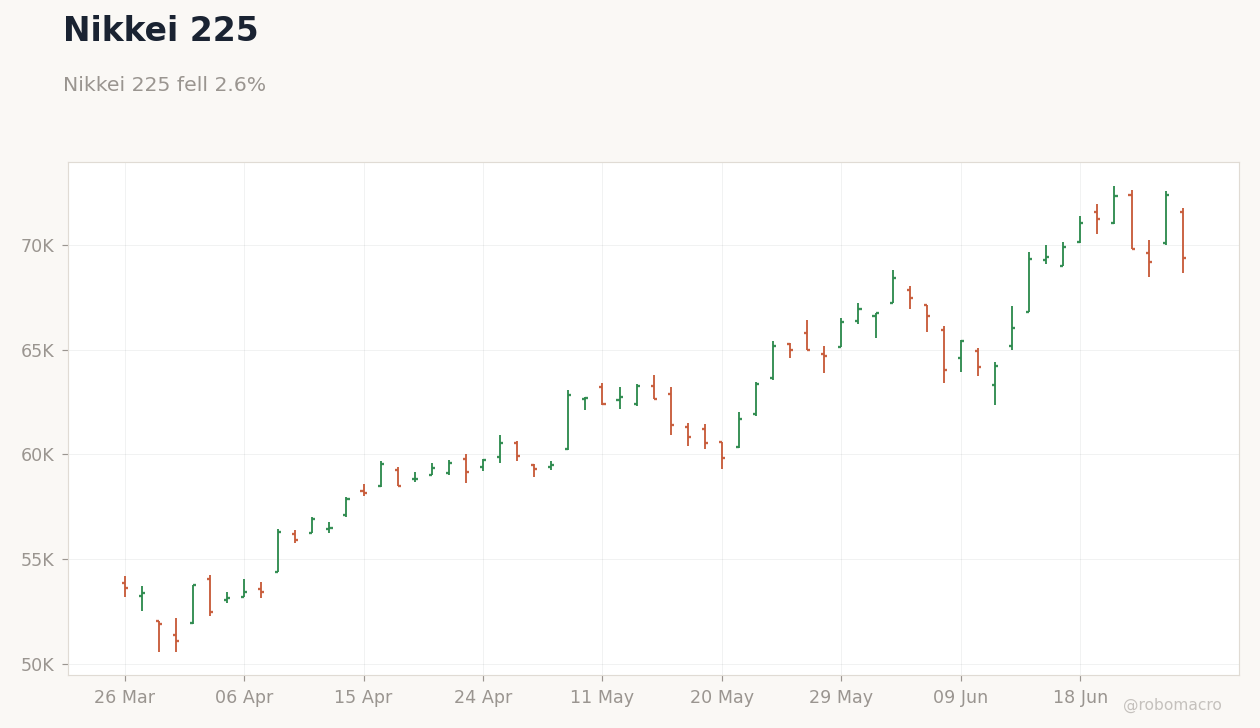
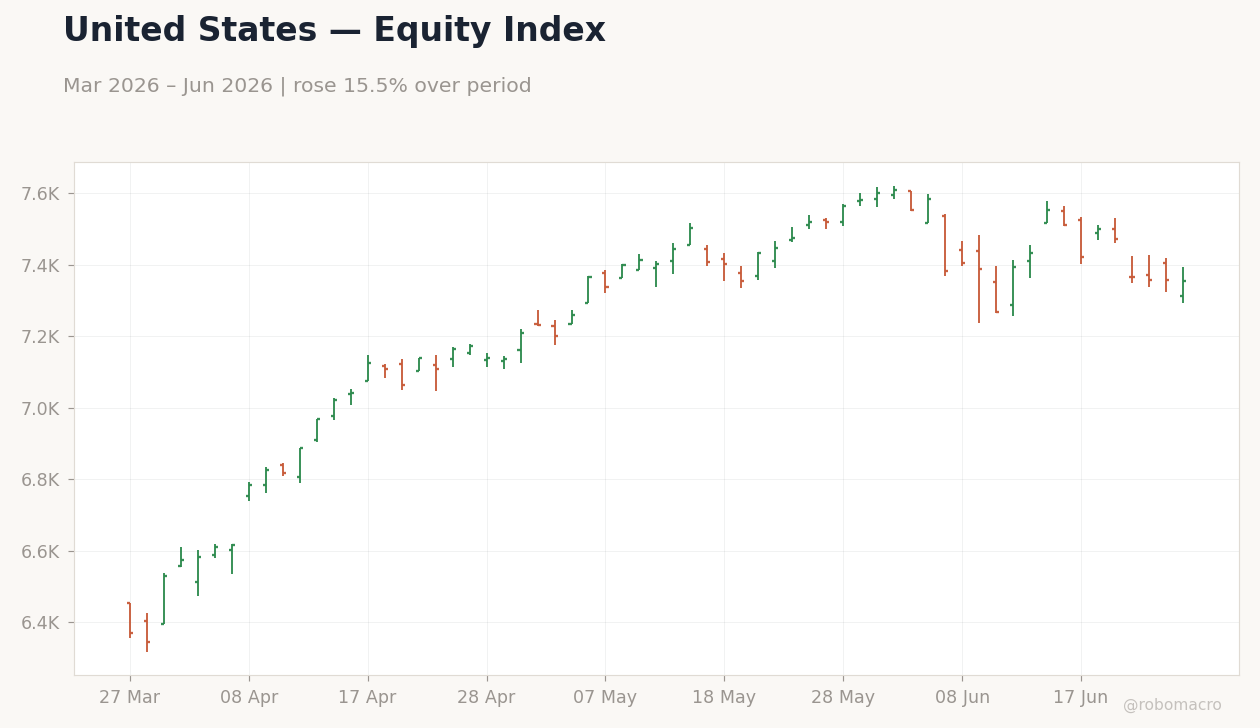
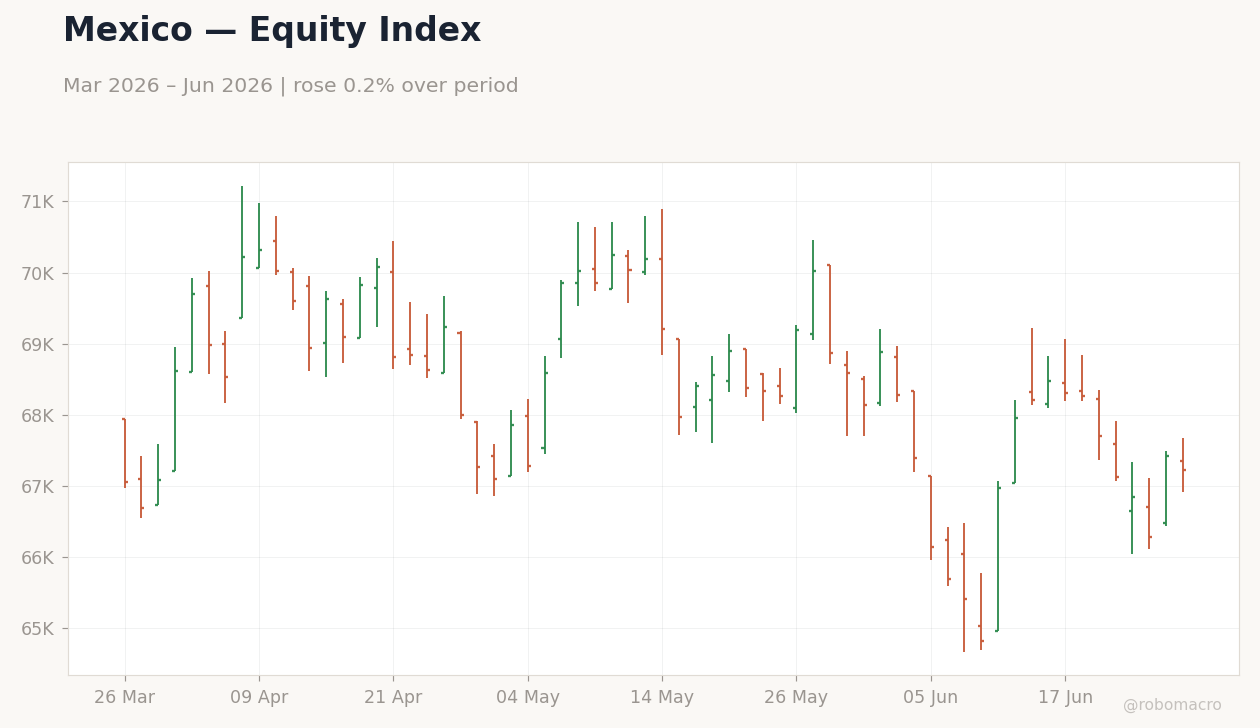
The S&P 500 fell 1.9% week-over-week to close at 7,354. The index opened the week at 7,473 on Monday before declining to 7,365 on Tuesday, 7,358 on Wednesday, 7,357 on Thursday and 7,354 on Friday, reflecting steady selling pressure. US equities displayed clear internal splits, with the Nasdaq 100 dropping 4.2% to 29,118 while the Dow Jones rose 0.6% to 51,876 and the Russell 2000 advanced 1.0% to 3,010. European markets ended mixed as the Euro Stoxx 50 fell 1.1% to 6,222, the FTSE 100 gained 1.4% to 10,508, the DAX declined 1.3% to 24,671, the CAC 40 eased 0.4% to 8,385 and the FTSE MIB dropped 3.0% to 51,265. Asian indices came under heavier pressure with the Nikkei 225 down 2.6% to 69,361, the Hang Seng falling 5.2% to 22,672, the CSI 300 off 1.5% to 4,868 and the KOSPI plunging 7.1% to 8,411. Emerging market performance diverged, as the Ibovespa rose 2.8% to 173,295 while the IPC Mexico fell 0.7% to 67,226 and the JSE Top 40 declined 2.3% to 6,654.

Regional Divergences

Asian equities posted the weakest weekly results, with the KOSPI down 7.1%, the Hang Seng down 5.2% and the Nikkei 225 down 2.6%, contrasting with more modest moves in the S&P 500 at minus 1.9% and the Euro Stoxx 50 at minus 1.1%. Within Europe the FTSE 100 bucked the trend with a 1.4% gain while the FTSE MIB fell 3.0%, underscoring regional divergence. These differences aligned with macro catalysts including US S&P Global Manufacturing PMI that beat consensus and confirmed activity resilience, French and German composite PMI prints that highlighted regional splits, and Japanese flash PMIs that delivered clear beats. In Latin America the Ibovespa’s 2.8% rise occurred amid selective equity gains despite commodity weakness, while UK flash PMIs delivered downside surprises in services and manufacturing. Overall the pattern reflected technology and AI-related pressures weighing more on Asia and growth-sensitive markets.

Volatility & Risk Appetite

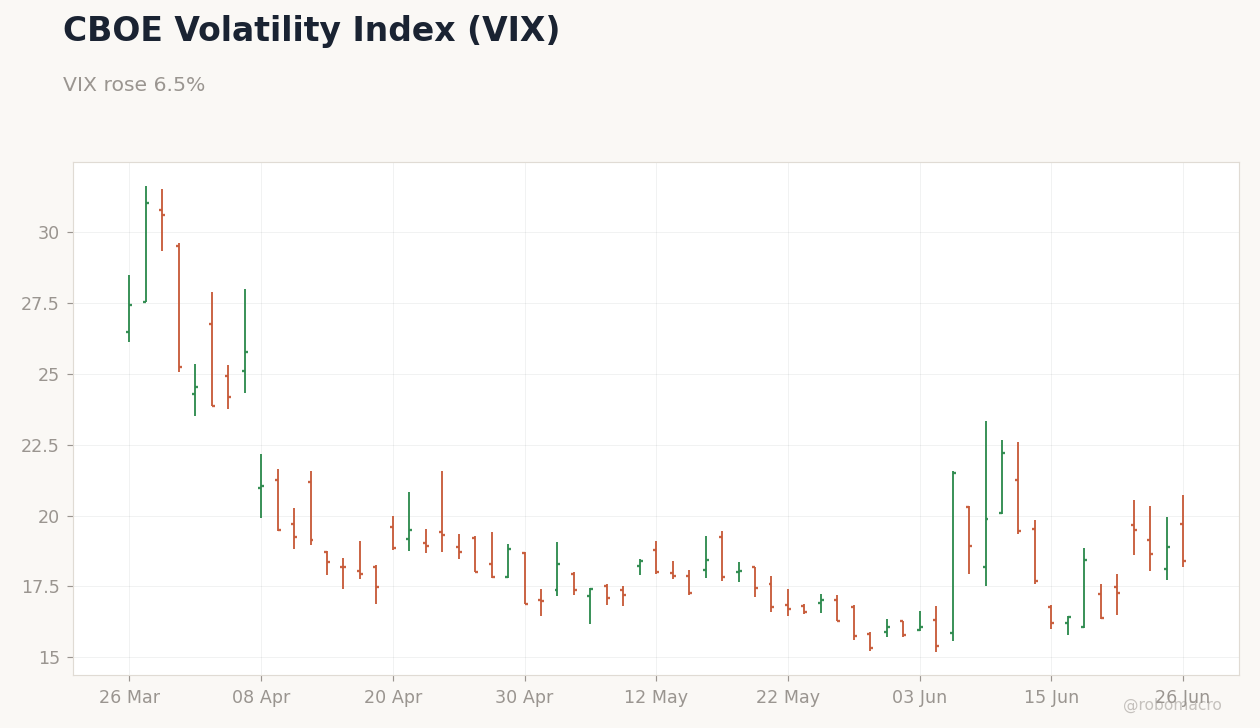
The VIX closed the week at 18.4 after rising from 17.3 on Monday to 19.5 on Tuesday before easing. Growth underperformed value markedly, with the Nasdaq 100 down 4.2% versus the Dow Jones gain of 0.6%. Small caps outperformed large caps as the Russell 2000 rose 1.0% against the S&P 500’s 1.9% decline. Sector signals from commodity and rate moves pointed to risk aversion, with WTI Crude down 9.6%, Brent Crude down 9.1%, silver down 9.9%, copper down 2.6% and gold down 3.0%, consistent with rotation out of technology and cyclical exposure amid concerns over AI costs and trade tensions. Declines in sovereign yields, including US 10Y at 4.37% (-8bp), UK 10Y at 4.73% (-11bp) and German 10Y at 2.85% (-14bp), offered limited support but failed to restore broad risk appetite.

Week Ahead

Next week’s calendar is relatively light, yet several PMI releases and central bank communications could still sway sentiment. Any hotter-than-expected CPI prints would pose the biggest risk to equities by reinforcing higher-for-longer pricing and favoring risk-off moves. Earnings reports from technology and semiconductor names remain focal given this week’s weakness and could amplify volatility depending on guidance around AI-related costs. GDP prints and central bank meetings, where scheduled, would be watched for confirmation of regional resilience or policy tightening, with outcomes likely to tilt markets toward risk-on only if they clearly ease inflation concerns.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewGlobal Equities
Global Equity Indices
Week-on-week, month-to-date, year-to-date. Source: Yahoo Finance.
IndexLevelWoWMTDYTD
S&P 5007,354-1.9%-3.2%+7.2%
Nasdaq 10029,118-4.2%-4.6%+15.5%
Dow Jones51,876+0.6%+1.6%+7.2%
Russell 20003,010+1.0%+3.6%+20.0%
S&P/TSX34,980+0.0%+0.7%+9.7%
FTSE 10010,508+1.4%+1.6%+5.6%
Euro Stoxx 506,222-1.1%+3.1%+5.0%
DAX24,671-1.3%-1.3%+0.5%
CAC 408,385-0.4%+2.9%+2.3%
FTSE MIB51,265-3.0%+3.0%+13.0%
IBEX 3519,425+0.4%+6.8%+11.1%
Nikkei 22569,361-2.6%+3.6%+33.8%
Hang Seng22,672-5.2%-10.7%-13.9%
CSI 3004,868-1.5%+0.5%+3.2%
S&P/ASX 2008,764-0.7%+0.4%+0.4%
KOSPI8,411-7.1%-4.3%+95.2%
Nifty 5024,056-0.5%+2.9%-8.0%
Ibovespa173,295+2.8%+0.6%+8.0%
IPC Mexico67,226-0.7%-1.3%+4.8%
JSE Top 406,654-2.3%-2.7%-5.7%

US equities diverged, as the Nasdaq 100 fell 4.2% while the Dow Jones rose 0.6% and the Russell 2000 gained 1.0%; the S&P 500 slipped 1.9%. In Europe, the FTSE MIB declined 3.0% and the DAX dropped 1.3%, offset by the FTSE 100’s 1.4% advance. Asian benchmarks weakened sharply, with the KOSPI plunging 7.1%, the Hang Seng falling 5.2%, and the Nikkei 225 losing 2.6%. The CSI 300 eased 1.5% while the S&P/ASX 200 declined 0.7%. Among emerging markets, the Ibovespa rose 2.8% and the IPC Mexico fell 0.7%. Year-to-date, the KOSPI remains up 95.2% and the Nikkei 225 up 33.8%. Next week, focus turns to US jobs data and ECB speeches for policy signals.

Equity Performance Heat Map
IndexWoWMTDYTD
S&P 500-1.9%-3.2%+7.2%
Nasdaq 100-4.2%-4.6%+15.5%
Dow Jones+0.6%+1.6%+7.2%
Russell 2000+1.0%+3.6%+20.0%
S&P/TSX+0.0%+0.7%+9.7%
FTSE 100+1.4%+1.6%+5.6%
Euro Stoxx 50-1.1%+3.1%+5.0%
DAX-1.3%-1.3%+0.5%
CAC 40-0.4%+2.9%+2.3%
FTSE MIB-3.0%+3.0%+13.0%
IBEX 35+0.4%+6.8%+11.1%
Nikkei 225-2.6%+3.6%+33.8%
Hang Seng-5.2%-10.7%-13.9%
CSI 300-1.5%+0.5%+3.2%
S&P/ASX 200-0.7%+0.4%+0.4%
KOSPI-7.1%-4.3%+95.2%
Nifty 50-0.5%+2.9%-8.0%
Ibovespa+2.8%+0.6%+8.0%
IPC Mexico-0.7%-1.3%+4.8%
JSE Top 40-2.3%-2.7%-5.7%
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewFX & Digital Assets
FX & Digital Assets Chart 1
FX & Digital Assets Chart 2
FX & Digital Assets Chart 3
FX & Digital Assets Chart 4

Week in Review

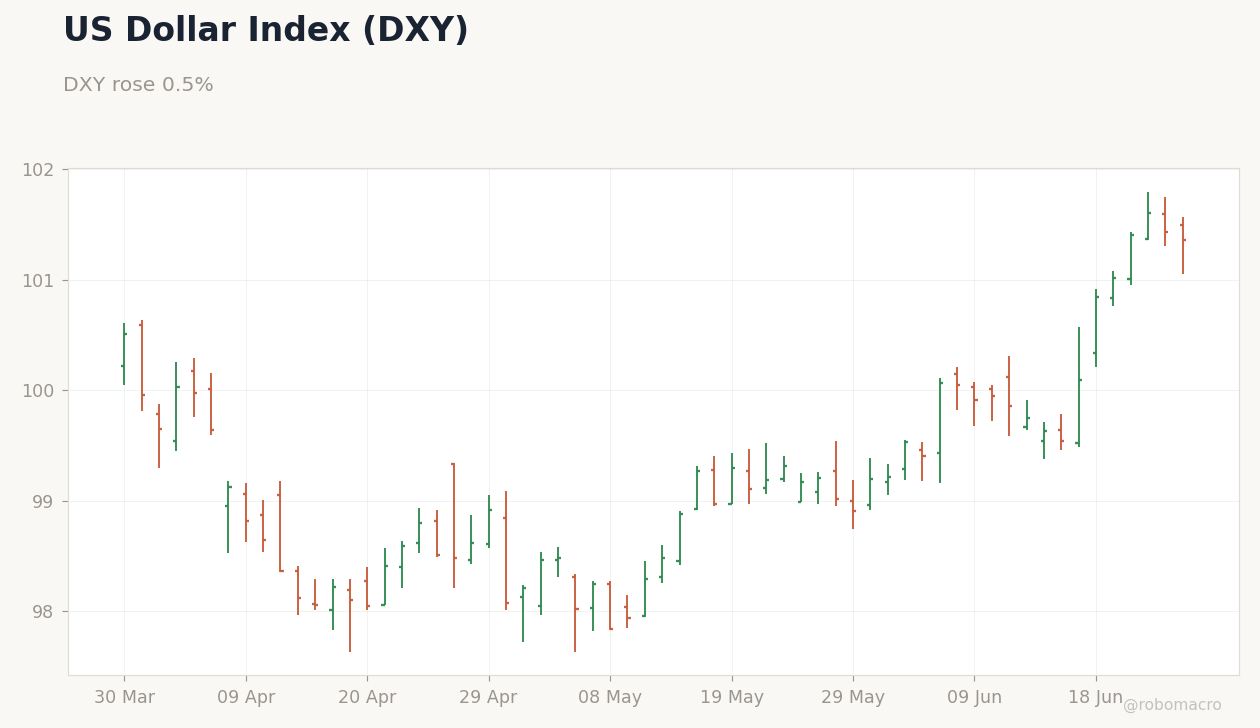
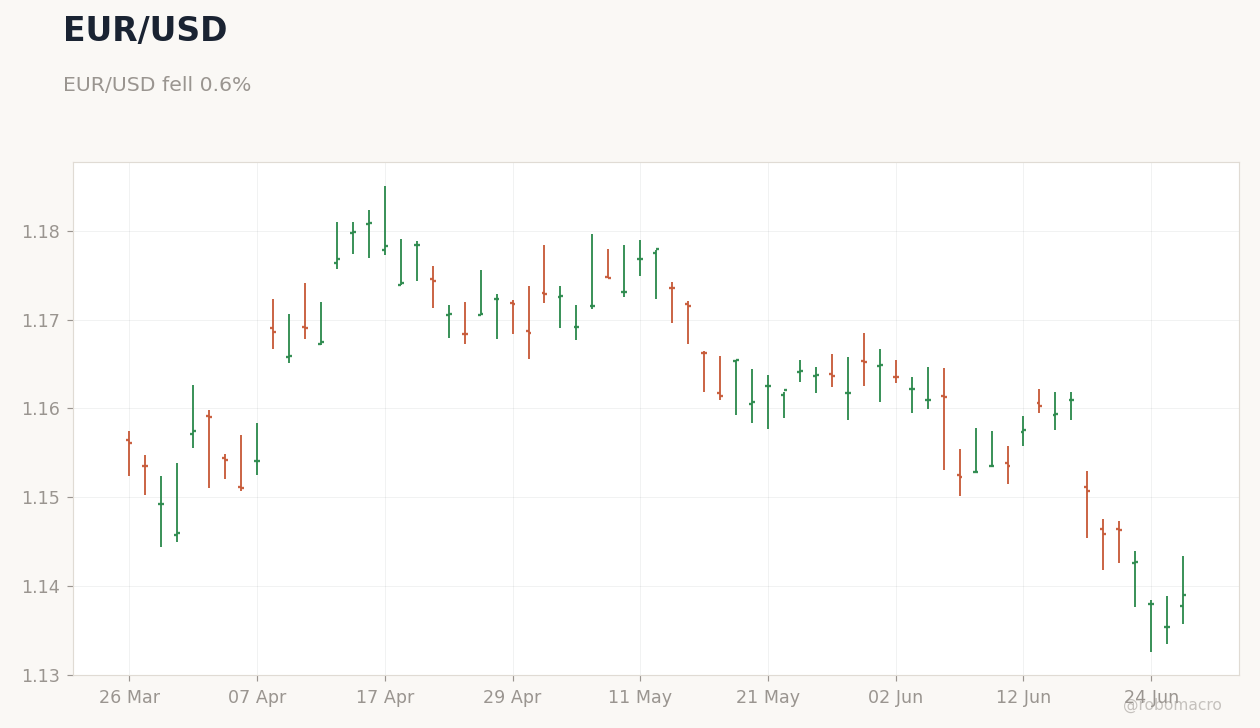
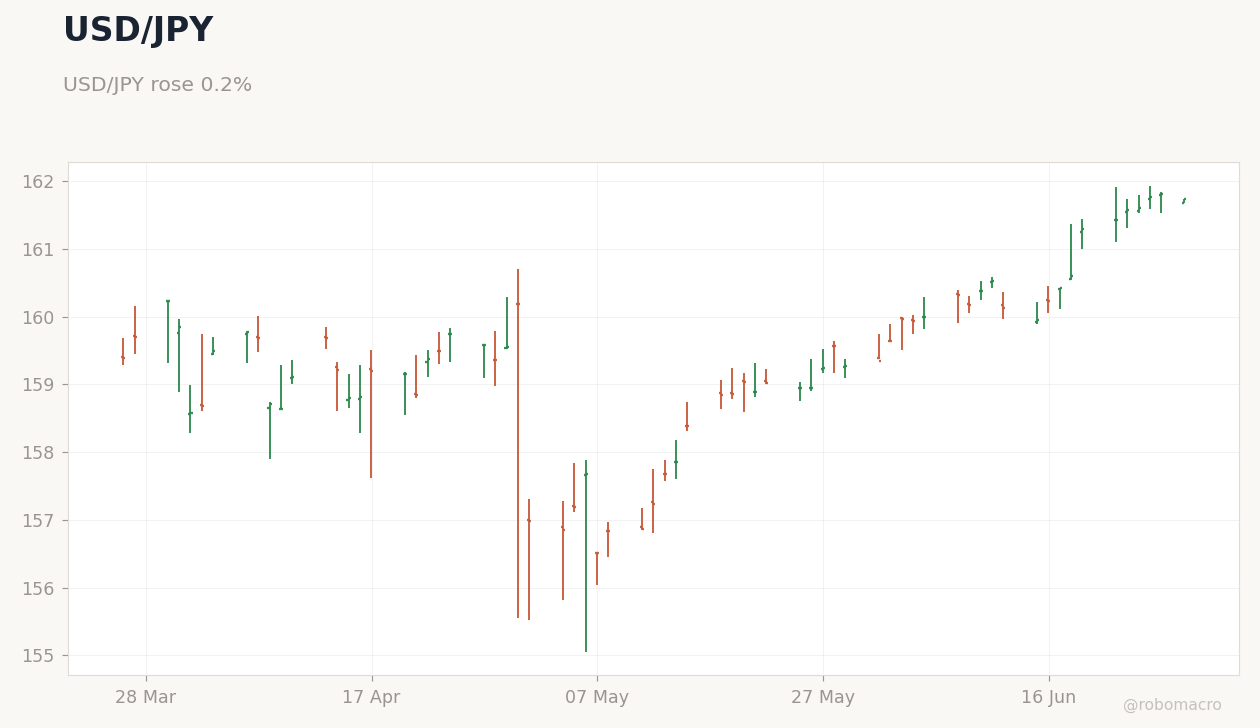
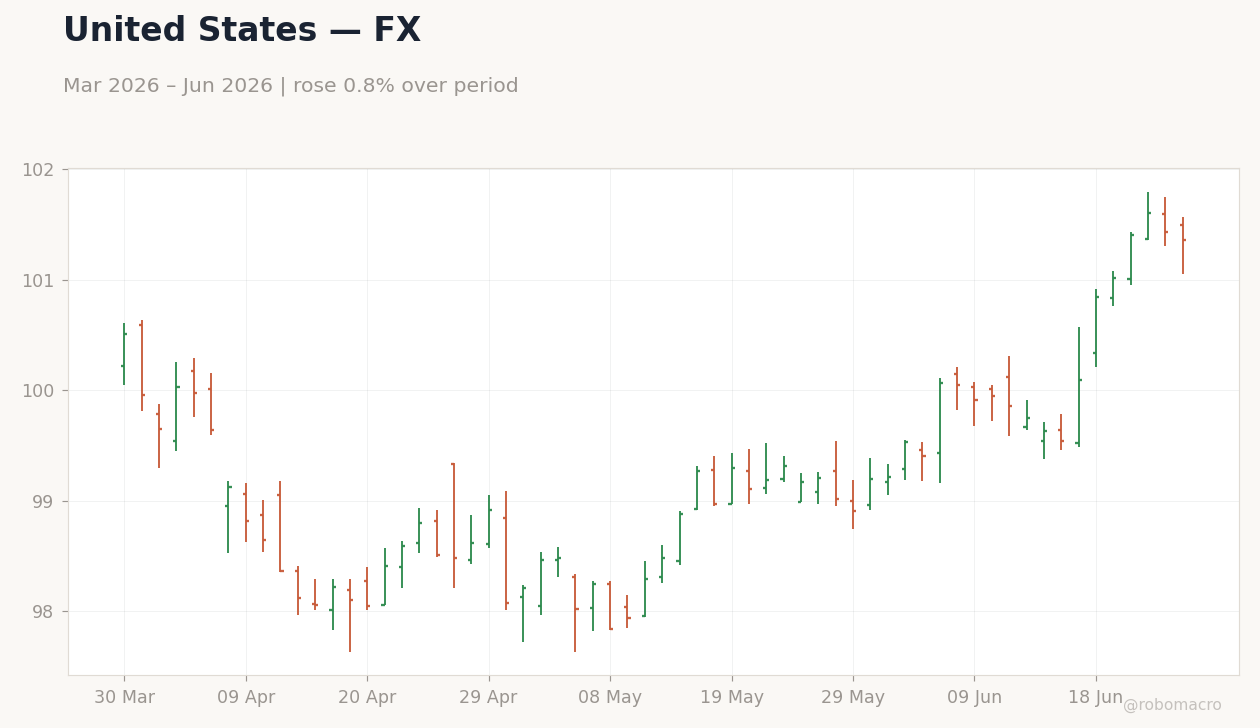
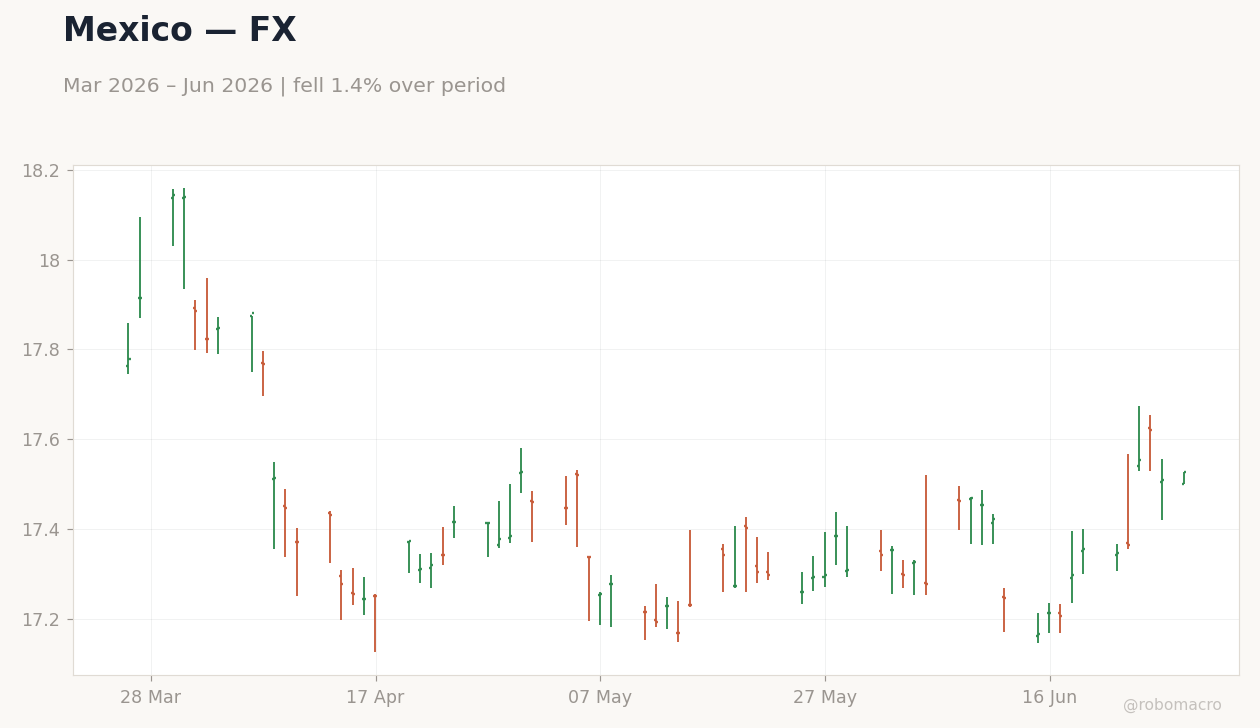
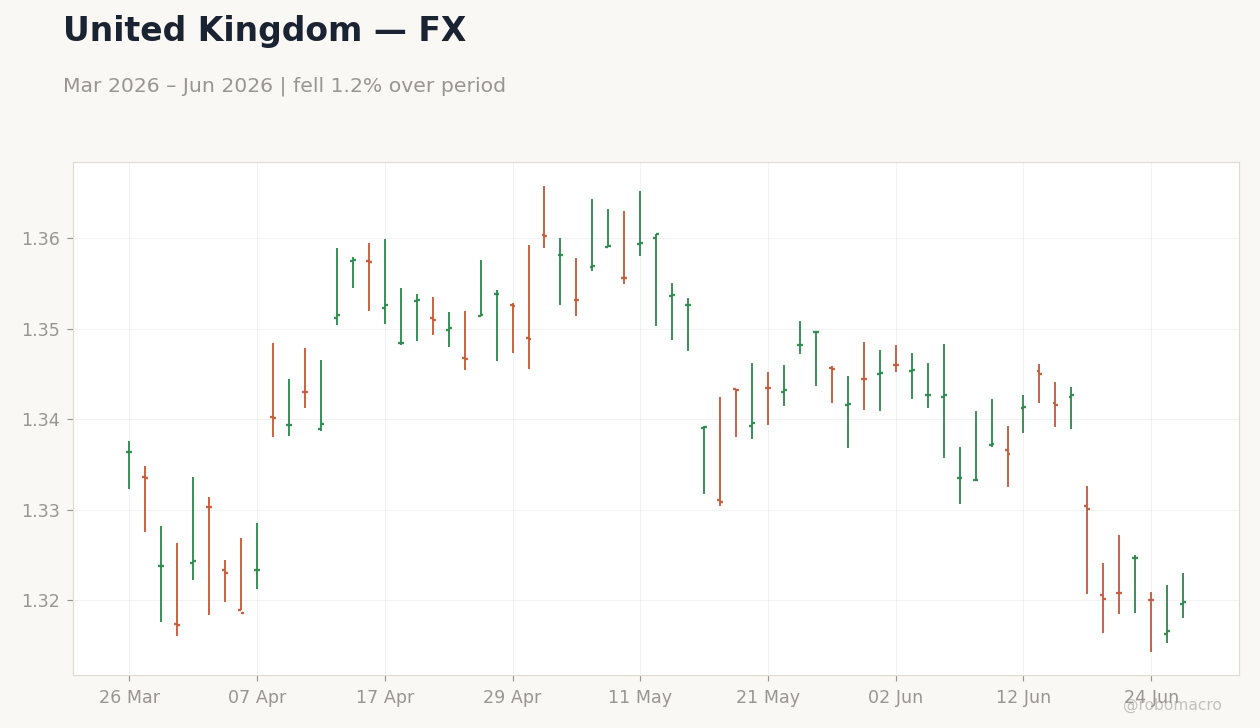
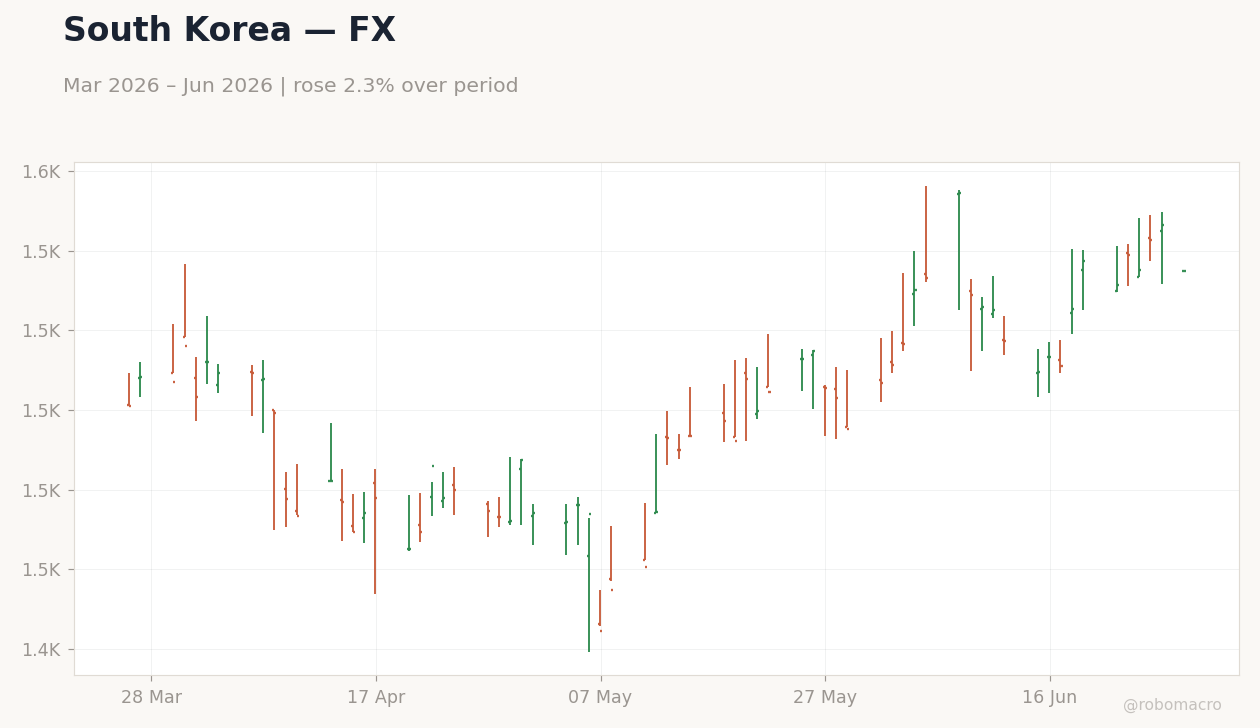
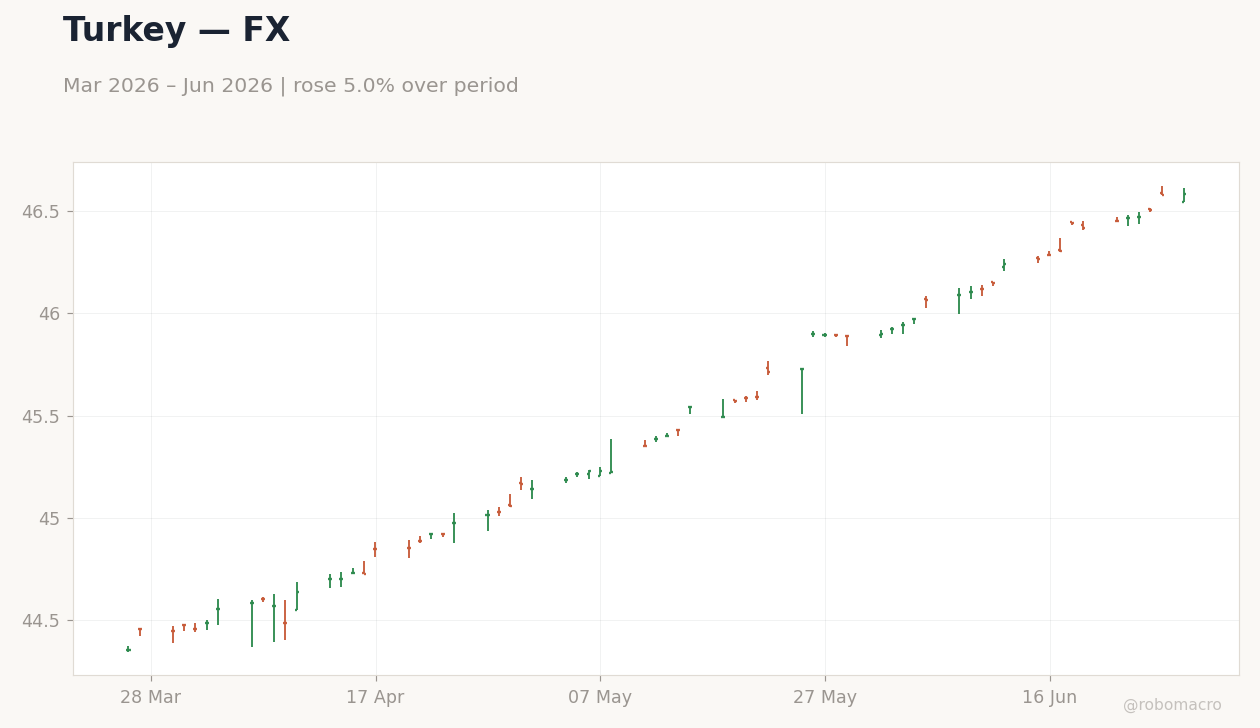
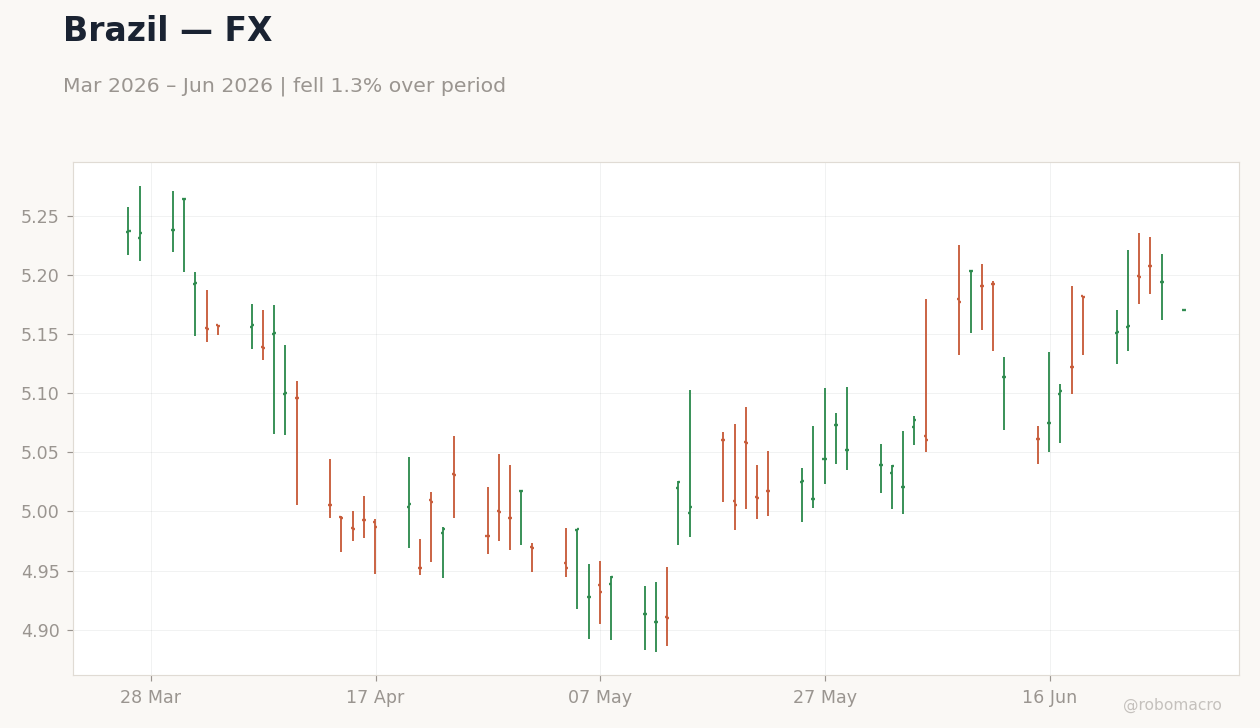
The DXY rose 0.5% this week to close at 101.36. It climbed from 101 on Tuesday to 102 on Wednesday before returning to 101 on both Thursday and Friday. EUR/USD fell 0.6% to 1.1390, sliding from 1.1463 on Monday to 1.1354 on Thursday before a modest recovery to close at 1.1390 on Friday. GBP/USD ended unchanged at 1.3198 while USD/JPY rose 0.2% to 161.73, trading at 162 on Tuesday through Friday after opening the period at 161 on Monday. Across EM, USD/MXN gained 1.0% to 17.53, USD/BRL rose 0.4% to 5.1704, USD/CNY increased 0.4% to 6.7975, USD/TRY edged higher by 0.3% to 46.59, and USD/ZAR was flat at 16.45.

Dollar & G10

DXY resilience reflected rate differentials that favored the dollar as US yields declined by less than those across the UK, Germany, and other European markets while Japanese yields showed mixed moves with the 2-year rising. This environment kept pressure on the euro and pound. EUR/USD closed at 1.1390 after a 0.6% weekly decline. GBP/USD finished at 1.3198 with a 0.0% weekly change. USD/JPY advanced 0.2% to 161.73 and remained anchored near 162 for the balance of the week.

EM FX

EM FX moves were led higher by USD/MXN which rose 1.0% to 17.53 amid commodity price softness and yield differentials that kept Mexican rates elevated relative to the US. USD/BRL gained 0.4% to 5.1704 while USD/CNY rose 0.4% to 6.7975 as regional capital flows remained selective. USD/TRY advanced 0.3% to 46.59 and USD/ZAR was unchanged at 16.45. These shifts occurred against a backdrop of varied bond yield movements across Brazil, Mexico, Turkey, China, and South Africa that continued to influence currency positioning without producing uniform directional momentum.

Bitcoin & Crypto

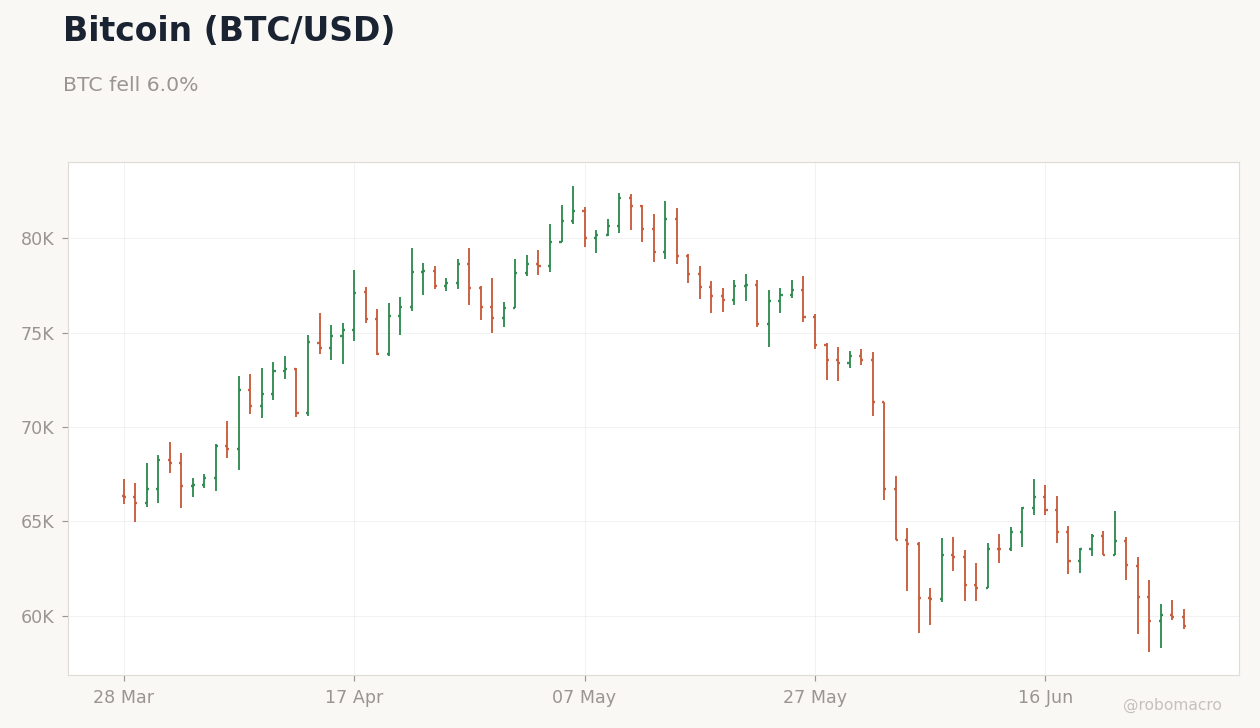
Bitcoin fell 6.0% to $59,445. It dropped from 60,995 on Wednesday to 59,722 on Thursday, recovered modestly to 60,016 on Friday, and closed the week at 59,940 on Saturday. Ethereum declined 8.2% to $1,564. Solana fell 2.5% to $71 while XRP dropped 7.2% to $1. Risk sentiment weighed on the entire digital asset complex as broader equity rotation and commodity weakness extended into crypto markets.

Week Ahead

The calendar is light with no major central bank rate decisions scheduled. Trade balance data from select EM countries could still sway FX positioning through impacts on rate differentials. For digital assets any regulatory updates or on-chain activity tied to real world asset adoption will draw attention even in the absence of specific ETF deadlines. Overall the period should remain driven by ongoing data dependence rather than singular scheduled releases.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewCommodities
Commodities Chart 1
Commodities Chart 2
Commodities Chart 3
Commodities Chart 4

Week in Review

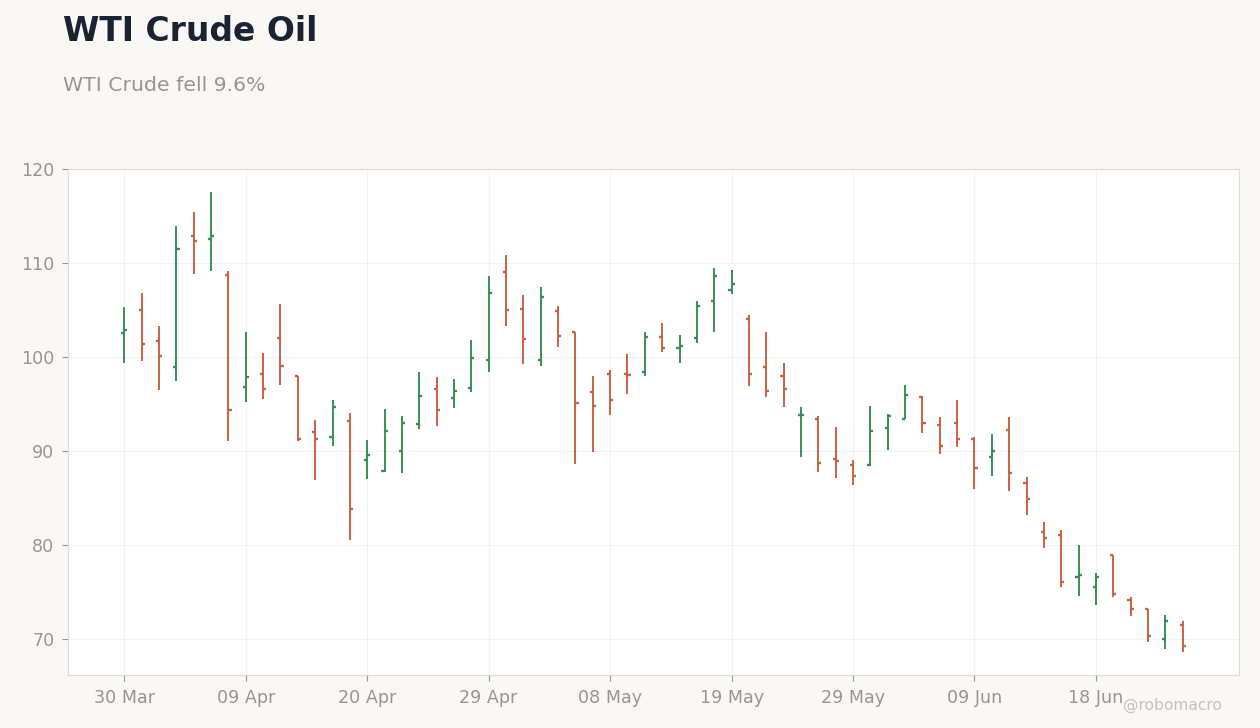
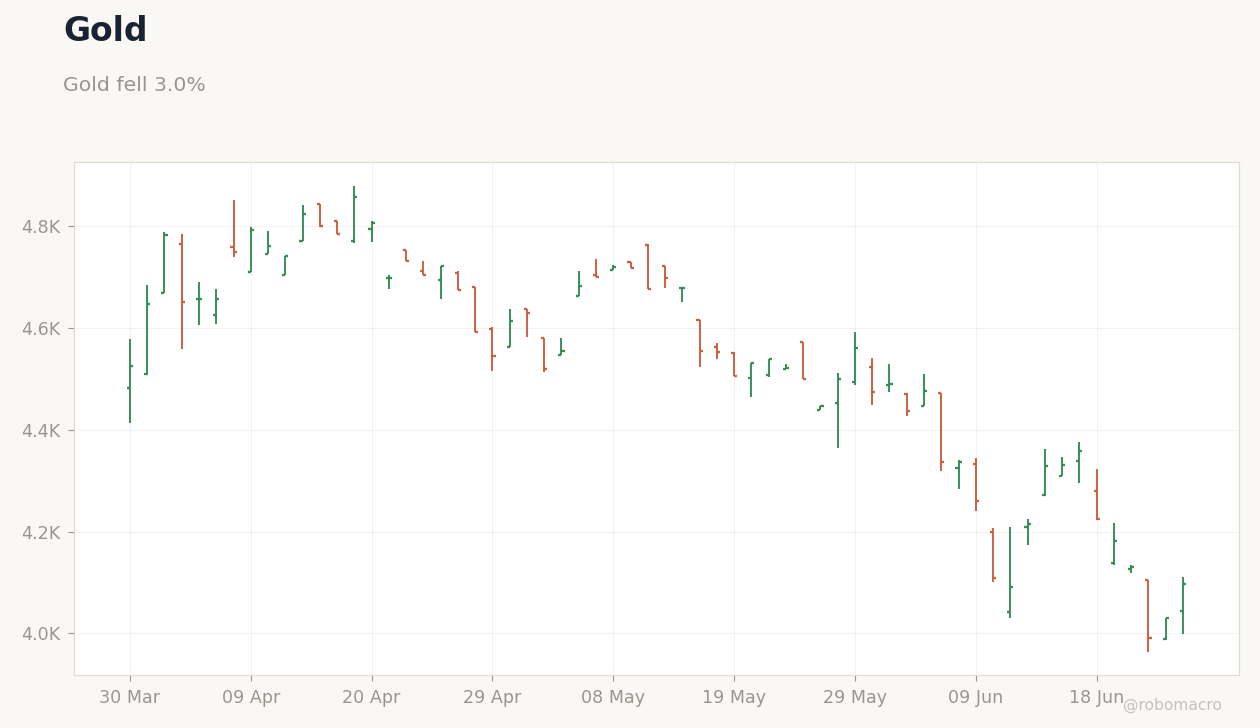
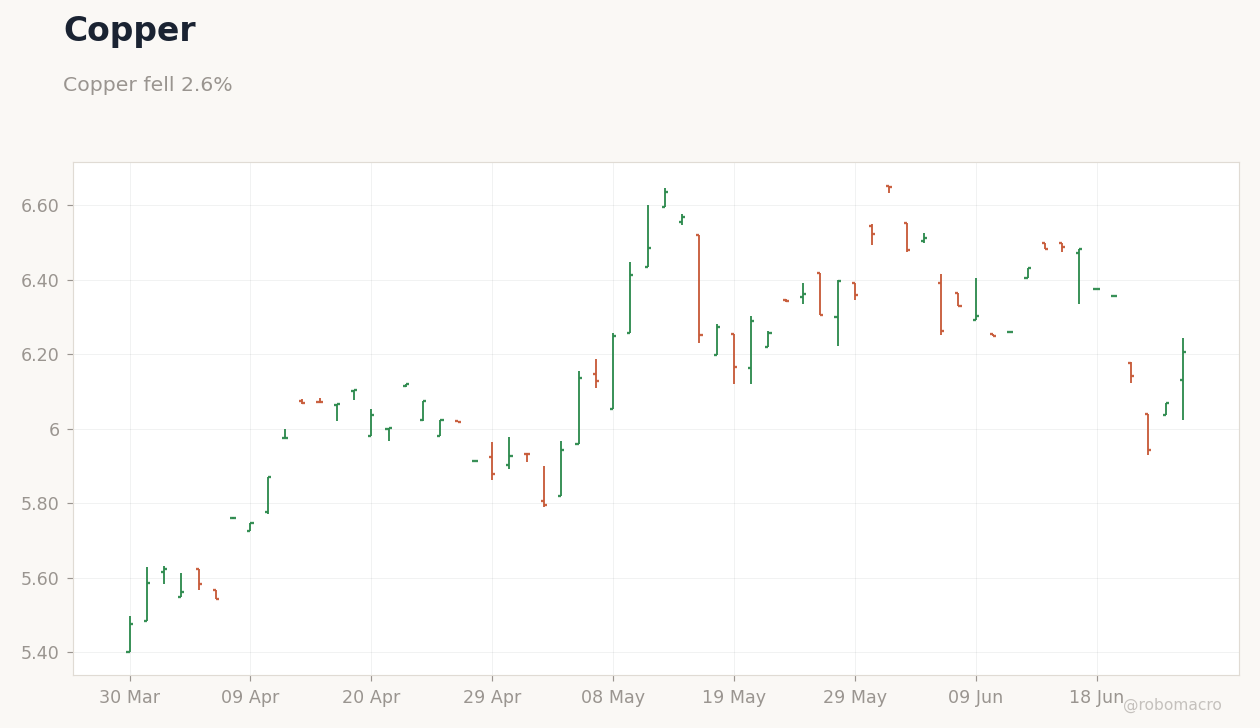
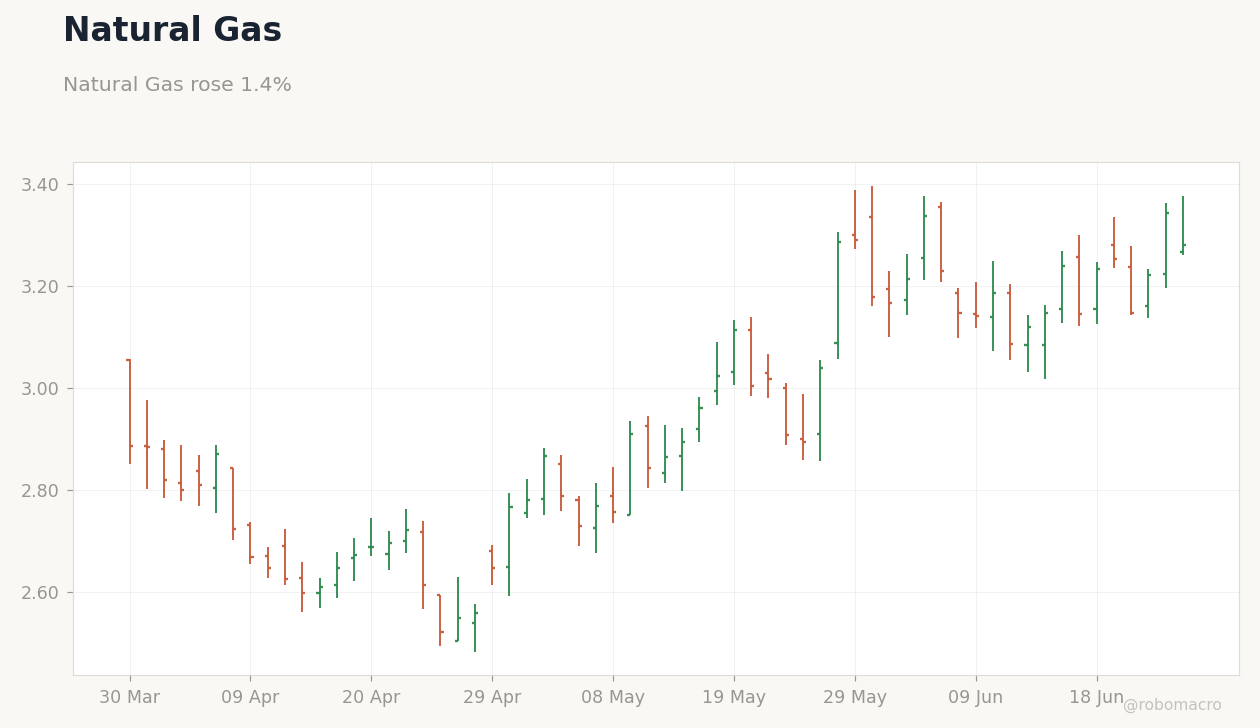
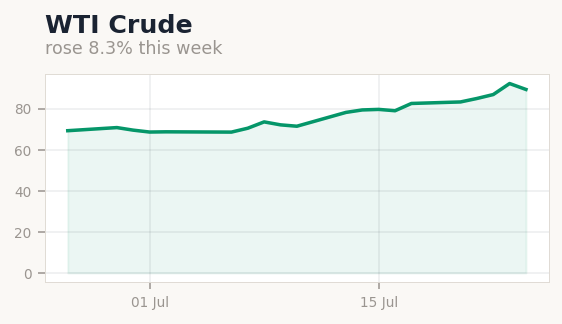
Silver recorded the largest weekly move, falling 9.9%. WTI Crude dropped 9.6% to 69.23 while Brent Crude fell 9.1% to 72.60. WTI Crude traded at 73.2 on Tuesday, declined to 70.3 on Wednesday, rebounded to 71.9 on Thursday and closed the week at 69.2 on Friday. Gold decreased 3.0% to 4096.30, copper eased 2.6% to 6.21 and wheat declined 2.6% to 589.75. Natural gas bucked the broader trend, rising 1.4% to 3.28. These moves left the complex mixed, with energy and precious metals under pressure while agriculture showed only modest declines.

Energy Complex

WTI Crude settled at 69.23 after a 9.6% weekly decline while Brent Crude closed at 72.60, down 9.1%. Natural gas advanced 1.4% to 3.28, providing a measure of relative resilience within the complex. Tankers exiting the Strait of Hormuz eased supply concerns even after a cargo vessel was hit near Oman, contributing to the softer tone. The US-Iran truce further steadied oil markets and reduced near-term disruption premia. Selective diplomatic progress on sanctions relief added to the cautious sentiment across crude benchmarks.

Metals & Ags

Gold closed at 4096.30 after a 3.0% weekly decline while silver fell 9.9% to 59.67. The gold-silver ratio widened as silver underperformed. Copper declined 2.6% to 6.21, signaling softening industrial demand and acting as a cautious growth indicator. Wheat fell 2.6% to 589.75, reflecting limited moves across agricultural commodities. Overall, precious metals faced headwinds from a firmer dollar while base metals and grains remained range-bound amid mixed global growth signals.

Week Ahead

The economic calendar for next week contains no commodity-relevant events. There are no scheduled EIA crude or gas inventory releases, OPEC meetings, China PMI or industrial production data, US CPI prints, or central-bank decisions affecting commodity currencies such as the CAD, AUD or BRL. Participants will therefore focus on non-calendar risks including geopolitical developments around the Strait of Hormuz and US-Iran relations, weather patterns that could influence natural gas demand or wheat yields, and any OPEC diplomacy regarding production policy. These factors are likely to dominate positioning ahead of the subsequent data-heavy week.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Markets in ReviewFX, Commodities & Crypto
Foreign Exchange
PairLevelWoWMTDYTD
DXY101.36+0.5%+2.2%+3.0%
EUR/USD1.1390-0.6%-2.2%-3.1%
GBP/USD1.3198-0.0%-1.9%-2.0%
USD/JPY161.75+0.2%+1.5%+3.2%
AUD/USD0.6901-1.4%-3.9%+3.3%
NZD/USD0.5643-1.6%-5.7%-2.0%
USD/CAD1.4192+0.1%+2.9%+3.5%
USD/CHF0.80800.0%+3.3%+2.0%
USD/CNY6.7975+0.4%+0.5%-2.8%
USD/BRL5.1704+0.4%+2.6%-6.3%
USD/MXN17.53+1.0%+1.1%-2.5%
USD/INR94.39+0.1%-0.7%+4.9%
USD/ZAR16.45-0.0%+1.4%-0.6%
USD/TRY46.59+0.3%+1.5%+8.3%
Commodities
CommodityLevelWoWMTDYTD
WTI Crude69.23-9.6%-24.9%+20.8%
Brent Crude72.60-9.1%-23.6%+19.5%
Gold4096.30-3.0%-8.5%-5.1%
Silver59.67-9.9%-20.4%-15.4%
Copper6.21-2.6%-4.9%+10.1%
Natural Gas3.28+1.4%+3.1%-9.4%
Wheat589.75-2.6%-3.1%+16.4%
Iron Ore100.33-0.8%-4.5%-6.4%
Crypto Assets
AssetLevelWoWMTDYTD
Bitcoin$59,481-5.9%-16.6%-33.0%
Ethereum$1,566-8.2%-21.8%-47.8%
Solana$71-2.4%-12.8%-44.2%
XRP$1-7.1%-19.4%-44.4%

DXY rose 0.5% to 101.36 amid broad USD strength. EUR/USD fell 0.6% to 1.1390 while GBP/USD held steady at 1.3198. AUD/USD dropped 1.4% to 0.6901 and NZD/USD declined 1.6% to 0.5643, underperforming peers. USD/MXN advanced 1.0% to 17.53, leading EM gains, as USD/CNY edged up 0.4% to 6.7975. USD/JPY ticked higher 0.2% to 161.73 despite limited JPY movement. Divergences emerged with commodity currencies lagging versus Asian FX resilience in INR and TRY. Policy signals and flow dynamics likely shaped the week's price action. Next week, focus turns to upcoming central bank decisions and inflation prints.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
United States
Market Scorecard
AssetLevelWoW
S&P 5007354.02-1.6%
Nasdaq 10029118.24-4.0%
Dow Jones51876.11+0.3%
Russell 20003010.08+0.2%
USD/JPY161.72+0.2%
EUR/USD1.14-0.6%
GBP/USD1.32-0.1%
Gold4096.3-2.0%
WTI Crude69.23-7.5%
Bitcoin59406.84-6.1%
Chart 1
Chart 2
Chart 3
Chart 4
  • S&P Global Manufacturing PMI Flash rose and beat consensus, confirming activity resilience that reinforced higher-for-longer pricing with the first Fed cut still seen no earlier than mid-2027.
  • New Home Sales declined against expectations, extending the month-over-month contraction and highlighting housing sensitivity to elevated mortgage rates.
  • Fed Governor Waller delivered no new policy signals while Core PCE matched consensus, leaving Fed OIS curves anchored to the prevailing funds rate through the summer.
  • WTI Crude and the Nasdaq 100 declined as sanctions relief on Iranian oil and growth rotation pressured both energy and tech valuations.

Week in Review

Activity indicators surprised to the upside. S&P Global Manufacturing PMI Flash rose on June 23 and beat consensus, while the services reading exceeded expectations and the composite index climbed. ADP Employment Change lifted the prior figure and signaled continued labor demand into late June. These prints aligned with the mid-expansion narrative carried forward from the prior week, where US outperformance had already shifted terminal rate expectations higher.

Housing data delivered a clear downside surprise. New Home Sales dropped on June 24 versus consensus and prior, producing a month-over-month contraction that extended the prior decline. The current account deficit widened against consensus, reflecting firmer domestic demand that absorbed higher borrowing costs without immediate contraction. Mortgage rates eased only modestly, leaving affordability constrained.

Policy and inflation signals remained steady. Core PCE Price Index Month-over-Month matched consensus on June 25 after the prior print, while Durable Goods Orders contracted in line with expectations following the earlier surge. Fed Governor Waller’s June 22 remarks offered no fresh forward guidance, preserving the data-dependent stance. Equity markets digested the mixed releases with selective rotation, as the S&P 500 closed the week lower while the Dow Jones edged up.

Energy prices extended their disinflationary impulse. WTI Crude fell amid US sanctions relief on Iranian exports and larger-than-expected inventory draws, adding to the external price relief already visible in recent weeks. This configuration left the expansion intact but tilted financial conditions tighter through the dollar channel, with USD/JPY holding near the recent level.

Fed Watch

Fed Governor Waller’s June 22 speech provided no new policy signals, leaving markets focused on incoming data rather than shifts in forward guidance. Core PCE matching consensus reinforced the view that inflation remains on a gradual path consistent with the prevailing funds rate. Large banks passed the June 24 stress test, confirming capital buffers sufficient for severe scenarios and reducing near-term regulatory pressure on lending.

The combination of strong PMI prints and contained PCE left Fed OIS curves showing limited repricing for cuts before mid-2027, extending the higher-for-longer stance established after the prior week. ADP employment strength further supported the labor-market resilience narrative that has kept policy expectations anchored. No additional speakers were scheduled through midweek, keeping the data-dependent framework intact. Market pricing therefore continues to reflect tolerance for above-target inflation prints to sustain the expansion.

Data Review

S&P Global Manufacturing PMI Flash reached a level exceeding consensus and the prior reading, pointing to continued expansion in factory activity. The services component printed above expectations, lifting the composite and confirming broad-based momentum that supports above-trend growth. ADP Employment Change surpassed the prior reading, reinforcing labor-market resilience consistent with recent prints.

New Home Sales missed consensus and fell from the prior reading, producing a month-over-month drop that signals housing demand remains sensitive to elevated mortgage rates. The current account deficit widened against forecast, illustrating that domestic absorption continues to outpace external balances. Core PCE Month-over-Month held at consensus, matching the prior print and leaving the year-over-year path aligned with recent inflation levels.

Durable Goods Orders contracted in line with expectations after the prior gain, tempering the capital-spending signal without derailing the overall cycle view. GDP final estimates and personal spending data released on June 25 remained consistent with the prior quarter-over-quarter pace, indicating no abrupt shift in the mid-expansion trajectory. These outcomes collectively point to a labor- and manufacturing-supported expansion that tolerates above-target inflation prints, keeping Fed OIS curves priced for policy stability rather than near-term easing.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Speech by Fed's Waller---
3-Month Treasury Bill Auctio3.6-3.7
6-Month Treasury Bill Auctio3.7-3.8
ADP Employment Change Weekly26K-31K
Redbook Retail Sales Year-ov9.4-10.0
S&P Global Composite PMI Fla51.5-52.2
S&P Global Manufacturing PMI55.154.855.7
S&P Global Services PMI Flas50.751.051.3
Richmond Fed Manufacturing I13.09.04.0
Richmond Fed Manufacturing S16.0-3.0
Richmond Fed Services Revenu14.0--1.0
6-Week Bill Auction3.6-3.6
2-Year Note Auction4.1-4.2
Money Supply22800.0bn-23050.0bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29Dallas Fed Manufacturing Index0.40-
2026-06-30S&P/Case-Shiller Home Price Year-ov0.80-
2026-06-30Chicago PMI62.760.0
2026-06-30JOLTs Job Openings7.6mn7.3mn
2026-06-30Cb Consumer Confidence93.1-
2026-06-30API Weekly Crude Oil Stocks-765K-
2026-07-01MBA 30-Year Mortgage Rate6.6-
2026-07-01ADP Employment Change122K118K
2026-07-01Fed Chair Warsh Speech--
2026-07-01ISM Manufacturing PMI54.053.7
Chart 5
Chart 6
Chart 7
Chart 8

The Week Ahead

Monday features Japan housing starts and UK BoE Pill speech, with markets watching for any cross-border signals on rate paths. Tuesday brings US ISM Manufacturing PMI and construction spending, both expected to echo recent manufacturing strength. Wednesday includes ADP national employment and EIA crude inventories, providing an early read on labor and energy balances ahead of the holiday.

Thursday highlights initial jobless claims and factory orders, which will test whether the durable goods contraction extends. Friday delivers the employment situation report with consensus unemployment near recent levels and nonfarm payrolls in focus, alongside personal income and spending data. Any deviation from the recent Core PCE pace could shift OIS curves. Central bank speakers remain light, keeping attention on US data dependence.

Risks & Themes

Stronger-than-expected PMIs raise the possibility that growth momentum could keep inflation above target longer, pushing terminal rate expectations even higher than the mid-2027 cut already priced. Housing weakness introduces downside risk if mortgage rates remain elevated, potentially feeding into consumption softness later in the quarter. Oil’s drop adds disinflationary impulse that could eventually ease policy pressure, yet markets appear to be underweighting this channel relative to activity data.

Positioning shows modest long equity exposure in small-caps while the Nasdaq 100 underperformed, hinting at crowded growth trades that could unwind further on any labor-market surprise. Volatility remains contained but could rise around the employment report if payrolls deviate from the resilient ADP print. Upside growth scenarios support dollar strength, while downside housing data could steepen the Treasury curve modestly.

Cross-Asset

The S&P 500 declined 1.59 percent to 7354.02 while the Nasdaq 100 fell 4.05 percent to 29118.24, reflecting rotation away from growth stocks amid lower energy prices and steady inflation data. The Dow Jones rose 0.32 percent to 51876.11 and the Russell 2000 gained 0.19 percent to 3010.08, showing relative strength in value and small-cap segments. US 2-year yields closed at 4.09 percent after trading as high as 4.24 percent midweek, and 10-year yields settled at 4.40 percent following a peak near 4.51 percent.

EUR/USD fell 0.64 percent to 1.14 and GBP/USD declined 0.08 percent to 1.32 as the dollar held firm against the backdrop of resilient US activity. USD/JPY rose 0.18 percent to 161.72, extending the prior week’s modest advance. WTI Crude dropped 7.47 percent to 69.23 while gold declined 2.05 percent to 4096.30, both pressured by sanctions relief and risk-on flows into equities. Bitcoin fell 6.06 percent to 59406.84, tracking the broader risk-asset pullback.

Global Context

US sanctions relief on Iranian oil exports contributed to the WTI decline, easing supply concerns that had previously supported higher energy prices in prior weeks. Cross-border spillovers from resilient US activity continued to tighten financial conditions via the dollar, with EUR/USD falling. Geopolitical tensions between the United States and Iran remained elevated but contained within the recent truce framework, limiting broader risk-off flows. Trade dynamics showed the US current account deficit widening, reflecting domestic demand strength that absorbs external imbalances without immediate global contraction signals.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Eurozone
Market Scorecard
AssetLevelWoW
Euro Stoxx 506221.55-1.4%
DAX24671.22-1.9%
CAC 408384.87-0.2%
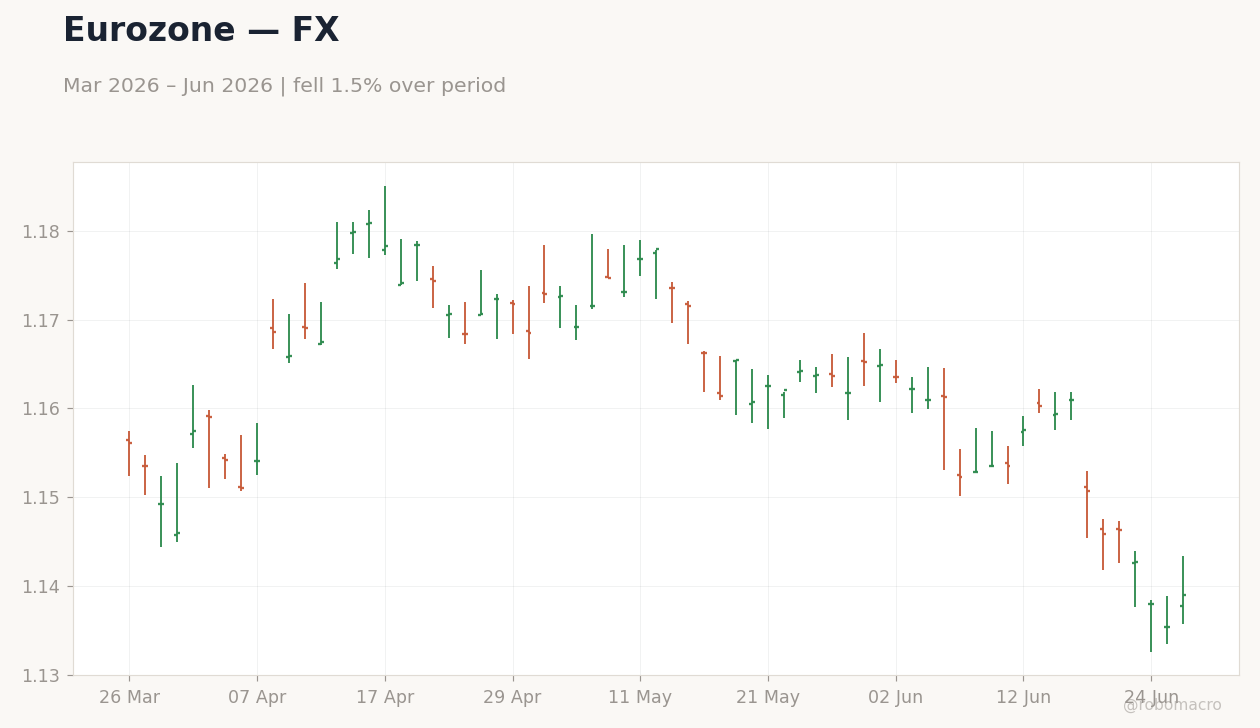
EUR/USD1.14-0.6%
EUR/GBP0.86-0.7%
EUR/JPY184.04-0.5%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Bitcoin59408.01-6.1%
Chart 1
Chart 2
Chart 3
Chart 4
  • French S&P Global Composite PMI Flash rose while German Composite fell, confirming regional divergence.
  • German Ifo Business Climate matched consensus and GfK Consumer Confidence printed softer than forecast, leaving domestic sentiment mixed.
  • German 10-year Bund yields climbed as markets reduced ECB easing probabilities following the data flow.
  • Euro Stoxx 50 declined while Brent Crude fell, tightening external disinflation impulses.

Week in Review

PMI Divergence Highlights Regional Split French flash PMIs delivered clear beats on 23 June while German equivalents missed, establishing the dominant narrative of uneven euro-area momentum. French Composite PMI rose against consensus and Services PMI jumped versus expected. German Manufacturing PMI slipped versus consensus and Composite PMI declined versus forecast. These prints reversed the modest recovery signals seen in the prior week ending 21 June when German ZEW sentiment had improved.

Consumer and Business Sentiment Remains Fragile Dutch Consumer Confidence improved from the prior reading on 22 June, yet German GfK printed softer than consensus on 24 June. French Consumer Confidence edged up versus expected on 24 June while Italian Consumer Confidence missed forecast. German Ifo Business Climate held steady at the consensus level on 24 June, providing the only clear match among high-impact releases.

Markets Reprice Policy Path Amid Data Dependence German 10-year Bund yields rose over the week as swap curves trimmed near-term ECB cut pricing. EUR/USD closed the week lower while Euro Stoxx 50 fell. Brent Crude’s decline reinforced external price relief that has yet to translate into synchronized domestic easing expectations. The week therefore left the euro-area expansion intact but data-dependent, with OIS curves showing only limited repricing relative to the US-driven global cycle described in prior reports.

ECB Watch

No Governing Council members spoke during the week, leaving markets to interpret data through the lens of existing forward guidance. German 10-year Bund yields rising prompted OIS curves to price fewer Deposit Rate cuts by year-end relative to the prior week. French PMI beats and German misses together reinforced the data-dependent stance articulated in recent ECB communications, with the Deposit Rate remaining the anchor. The Ifo match and GfK miss left medium-term growth and inflation projections broadly unchanged from the Bundesbank’s earlier upward revision to 2026 inflation. External oil-price relief via Brent’s decline further supports the view that above-target inflation will persist, keeping the first cut timing beyond the next several meetings. Overall, this week’s releases validated the ECB’s tolerance for selective resilience without altering the higher-for-longer rate path signaled in prior weeks.

Data Review

French S&P Global Manufacturing PMI Flash printed above consensus on 23 June, extending the modest expansion signal first visible in May. French Services PMI rose against expected, lifting the Composite and confirming broadening momentum in the largest euro-area economy. German Manufacturing PMI Flash missed consensus on the same day, while German Services PMI fell against expected and Composite PMI declined versus forecast. These German misses reversed the ZEW improvement recorded in the week ending 21 June. German Ifo Business Climate matched consensus exactly on 24 June, yet GfK Consumer Confidence disappointed versus expected, pointing to persistent household caution. French Consumer Confidence beat consensus while Italian Business Confidence met expectations and Consumer Confidence missed. Spanish Trade Balance widened. The combined releases indicate the euro area remains in mid-expansion with above-target inflation risks still dominant, supporting a higher-for-longer ECB Deposit Rate path and limiting near-term OIS repricing.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Consumer Confidence Index-46.0--39.0
Consumer Confidence Index-10.0--7.0
Wholesale Prices Month-over-0.20-0.90
Wholesale Prices Year-over-Y1.4-1.6
Bundesbank President Nagel S---
12-Month BTF Auction2.6-2.6
3-Month BTF Auction2.4-2.4
6-Month BTF Auction2.5-2.5
Business Confidence Index102101100
Business Climate Indicator93.095.094.0
S&P Global Composite PMI Fla44.946.047.6
S&P Global Manufacturing PMI49.750.050.7
S&P Global Services PMI Flas44.345.547.4
S&P Global Manufacturing PMI50.150.550.0
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29Inflation Rate Month-over-Month Pre0.10-
2026-06-29Inflation Rate Year-over-Year Preli3.23.2
2026-06-29Business Confidence Index-3.7-
2026-06-30Retail Sales Month-over-Month-0.300
2026-06-30Retail Sales Year-over-Year-0.300
2026-06-30Inflation Rate Year-over-Year Preli2.4-
2026-06-30Inflation Rate Month-over-Month Pre0.100
2026-06-30Headline Unemployment Rate6.36.4
2026-06-30Unemployed Persons Level3.0mn-
2026-06-30Unemployment Level Change-12K8000

The Week Ahead

Monday brings Finnish Business and Consumer Confidence indices alongside Japanese housing starts data that may influence external demand views. Tuesday features UK BoE Pill speech that could spill into euro-area rate expectations through sterling and gilt channels. Wednesday includes euro-area unemployment and German retail sales prints expected to test consumption resilience after the mixed GfK outcome. Thursday highlights Italian industrial production and French industrial production, both viewed as cycle indicators following the divergent PMI prints. Friday closes the period with Spanish and Italian PMI final releases that will confirm or revise the flash readings. Markets will also monitor any additional ECB speakers for clues on the medium-term Deposit Rate trajectory. The calendar contains no high-impact central-bank decisions, leaving data dependence as the dominant theme.

Risks & Themes

The week’s PMI divergence raises the probability of a more prolonged higher-for-longer ECB stance if German weakness fails to broaden. Upside risks center on further French services strength lifting the euro-area composite while downside risks stem from continued German services contraction. Market positioning shows limited OIS repricing relative to US curves, suggesting potential for volatility if next week’s retail sales or industrial production surprise to the downside. Brent’s decline reduces imported inflation risks yet may delay the ECB’s willingness to ease if core prints remain sticky. Flow data from prior weeks indicate continued preference for Bunds over peripheral debt, keeping 2s10s spreads vulnerable to steepening. Overall, the data shift tilts the balance toward cautious positioning ahead of the July releases.

Cross-Asset

Euro Stoxx 50 closed the week at 6,221.55 after a 1.42 percent decline, with daily moves including a 1.28 percent drop on 23 June and a 0.85 percent gain on 25 June. DAX fell 1.86 percent to 24,671.22 while CAC 40 declined 0.18 percent to 8,384.87. German 10-year Bund yields rose, pushing the 2s10s spread wider amid reduced easing odds. EUR/USD ended at 1.14 for a 0.64 percent weekly loss, EUR/GBP fell 0.72 percent to 0.86, and EUR/JPY declined 0.54 percent to 184.04. Brent Crude dropped 6.8 percent to 72.60 on successive daily declines of 1.05 percent, 4.33 percent, and 3.53 percent. Gold fell 2.05 percent to 4,096.30 while Bitcoin declined 6.06 percent to 59,408.01. Equity-bond divergence reflected data-driven repricing of ECB policy while commodity weakness added external disinflation support.

Global Context

US data resilience described in the week ending 21 June continued to anchor global rate expectations higher, limiting ECB easing scope through the dollar channel. Brent Crude’s further decline extended the disinflationary impulse visible since early June while supporting euro-area external balances. EUR/USD weakness mirrored the broader USD strength that followed the FOMC’s upward 2026 inflation revisions. Trade-balance widening in Spain highlighted ongoing external demand pressures amid the global mid-expansion phase. No new geopolitical developments altered the euro-area outlook in the last seven days, leaving cross-border spillovers centered on commodity prices and US policy spillovers.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Japan
Market Scorecard
AssetLevelWoW
Nikkei 22569360.88-4.1%
USD/JPY161.72+0.2%
EUR/JPY184.04-0.5%
GBP/JPY213.68+0.2%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Bitcoin59406.84-6.1%
Chart 1
Chart 2
Chart 4
  • Flash PMIs delivered clear beats, confirming private-sector momentum into the second half.
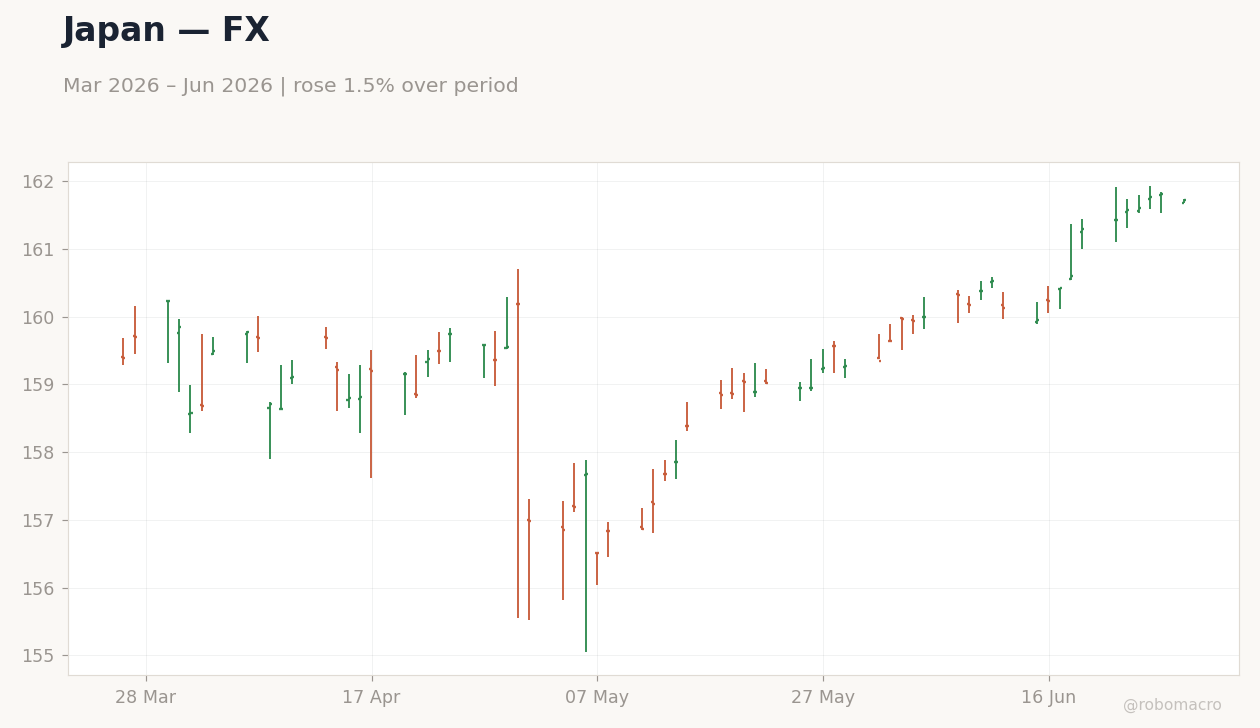
  • USD/JPY held near 161.72 while the Nikkei 225 closed the week at 69,360.88 after a 4.14 percent decline.
  • BoJ communications reinforced expectations for further tightening, lifting the 10-year JGB yield and keeping OIS pricing tilted toward additional policy adjustment.

Week in Review

PMI Strength Signals Resilience Japan’s June S&P Global flash PMIs exceeded expectations. Manufacturing and services both rose, reinforcing steady domestic demand even as external price pressures eased. The data aligned with prior export growth trends and narrowed the gap between activity expectations and realized outcomes.

Policy Signals Accelerate Repricing The BoJ Summary of Opinions revealed multiple members calling for further rate increases amid persistent inflation risks. Board member remarks flagged a higher neutral rate, well above the current policy setting. This language shifted market focus toward faster normalization and lifted the 10-year JGB yield.

Yen and Equity Divergence Persists USD/JPY remained anchored near 161.72. The Nikkei 225 posted a net 4.14 percent weekly decline to 69,360.88. Yen crosses showed limited follow-through after Ministry of Finance warnings, highlighting the dominance of US-Japan rate differentials.

Retail Sales and Fiscal Backdrop Markets awaited the retail sales release. The government’s draft long-term blueprint emphasized BoJ support for private demand while urging measured policy adjustments. These elements kept the growth-inflation trade-off in focus without altering near-term data dependence.

Cross-Asset Flows Reflect Carry Pressure Brent crude declined 6.8 percent to 72.60 and gold declined 2.05 percent to 4,096.30, removing safe-haven support for the yen. Bitcoin dropped 6.06 percent to 59,406.84 amid broader risk reduction. The configuration left BoJ OIS curves pricing a higher terminal rate path relative to the prior week.

BoJ Watch

The BoJ Summary of Opinions and successive speeches collectively reinforced the case for additional tightening. Communications moved the 10-year JGB yield higher while the 2-year yield stayed steady. BoJ OIS pricing shifted higher for the next meeting, reflecting reduced odds of a prolonged pause. Record intervention outlays failed to alter the rate-differential narrative sustaining USD/JPY near 161.72. The data flow leaves the Bank of Japan on a gradual but data-dependent path toward further normalization.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
S&P Global Manufacturing PMI54.554.554.9
S&P Global Services PMI Flas50.0-51.8
S&P Global Composite PMI Fla51.1-52.5
5-Year JGB Auction2.0-1.9
BoJ Summary of Opinions--""
BoJ Himino Speech---
BOJ Gov Ueda Speech---
Foreign Bond Investment Leve382.5bn-199.7bn
Foreign Stock Investment Lev-785.2bn-479.4bn
BOJ Tamura Speech---
20-Year JGB Auction3.7-3.5
Coincident Index Final117-118
Leading Economic Index Final115116116
Tokyo CPI Ex Food and Energy1.6-1.9
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29Housing Starts Year-over-Year11.431.8
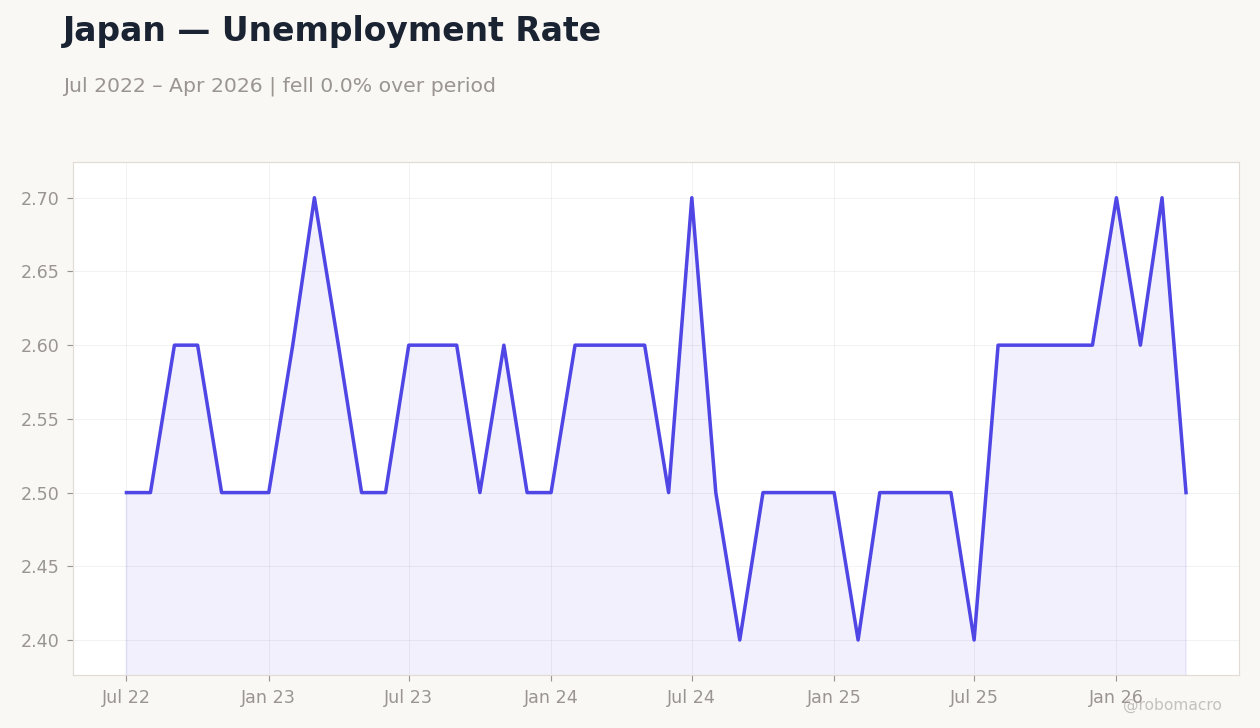
2026-06-29Headline Unemployment Rate2.52.5
2026-06-29Industrial Production Month-over-Mo0.501.1
2026-06-30Tankan Large Manufacturers Index17.016.0
2026-07-01Consumer Confidence Index33.634.0

The Week Ahead

Housing starts and construction orders on Monday will provide the first read on investment momentum ahead of the next BoJ decision. Retail sales year-over-year carry medium impact and will test whether consumer demand is keeping pace with PMI strength. Any follow-up comments from remaining BoJ speakers could refine guidance on the timing of the subsequent move. Markets will also monitor Ministry of Finance statements on intervention effectiveness. The combination should clarify whether recent activity resilience supports a faster pace of policy adjustment. OIS curves currently embed limited near-term repricing, leaving room for data surprises to shift terminal-rate expectations. Broader fiscal coordination signals from the government blueprint may influence perceptions of BoJ independence in coming quarters.

Risks & Themes

Persistent yen weakness near 161.72 risks further carry-trade unwinds that could spill into JGB and US asset markets. Upside surprises in retail sales or housing data would reinforce the case for accelerated hikes, while downside prints could delay the next move. Markets appear to underprice the speed of normalization implied by neutral-rate discussion. Intervention fatigue raises the possibility of sharper volatility if verbal warnings lose credibility. The data dependence shared with other DM central banks leaves Japan exposed to any renewed US inflation resilience that widens rate differentials further.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Canada
Market Scorecard
AssetLevelWoW
S&P/TSX34980.0-0.1%
USD/CAD1.42+0.1%
EUR/CAD1.61-0.6%
WTI Crude69.23-7.5%
Natural Gas3.28+0.8%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Bitcoin59391.7-6.1%
Chart 1
Chart 2
  • May CPI rose more than expected on both a year-over-year and month-over-month basis, lifting the headline to a multi-month high.
  • The Bank of Canada held the policy rate unchanged with no shift in forward guidance after the print, leaving OIS-implied easing limited by year-end.
  • Governor Macklem and Deputy Governor Rogers speeches reinforced data dependence without altering the reaction function despite the inflation overshoot.

Week in Review

Inflation overshoot dominates the narrative. May CPI rose more than consensus on a year-over-year basis and posted a larger month-over-month increase than expected. Core CPI also moved higher. The data confirmed energy-driven price pressures rather than broad-based demand strength.

Policy signals remain unchanged. The Bank of Canada kept the policy rate unchanged through the period, with both Governor Macklem and Deputy Governor Rogers delivering speeches that stressed ongoing data dependence. Markets absorbed the hotter prints without repricing near-term cuts.

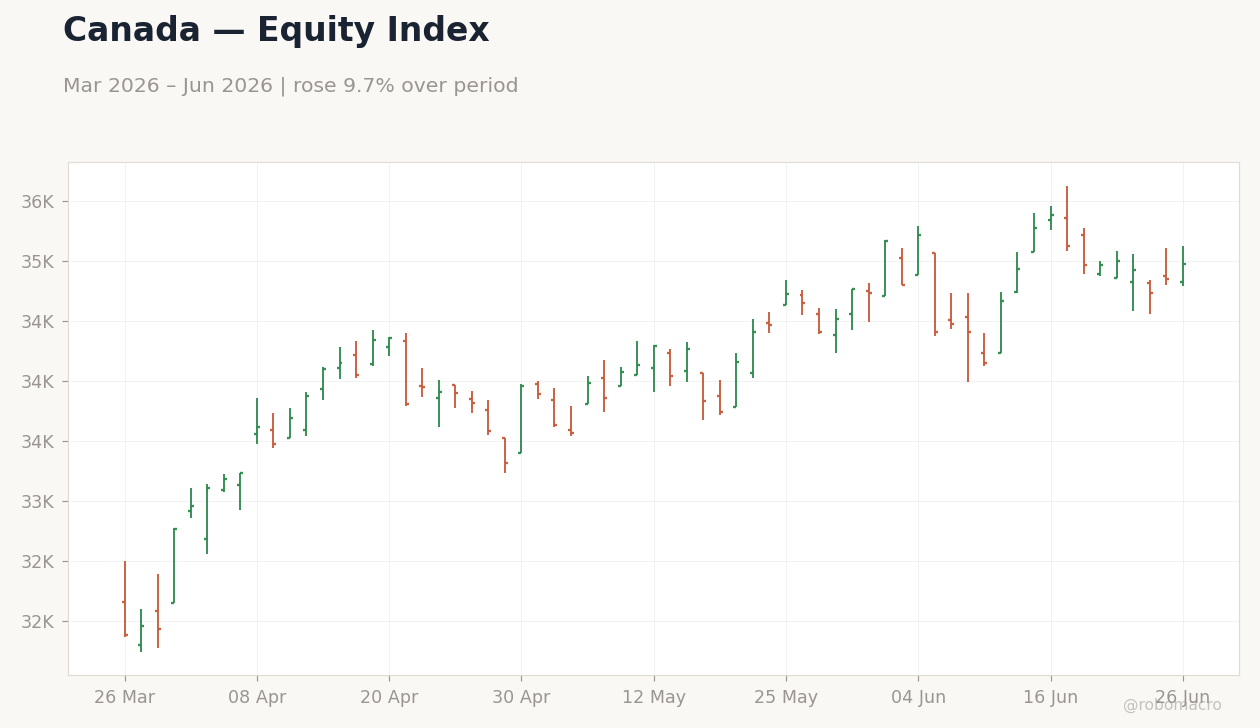
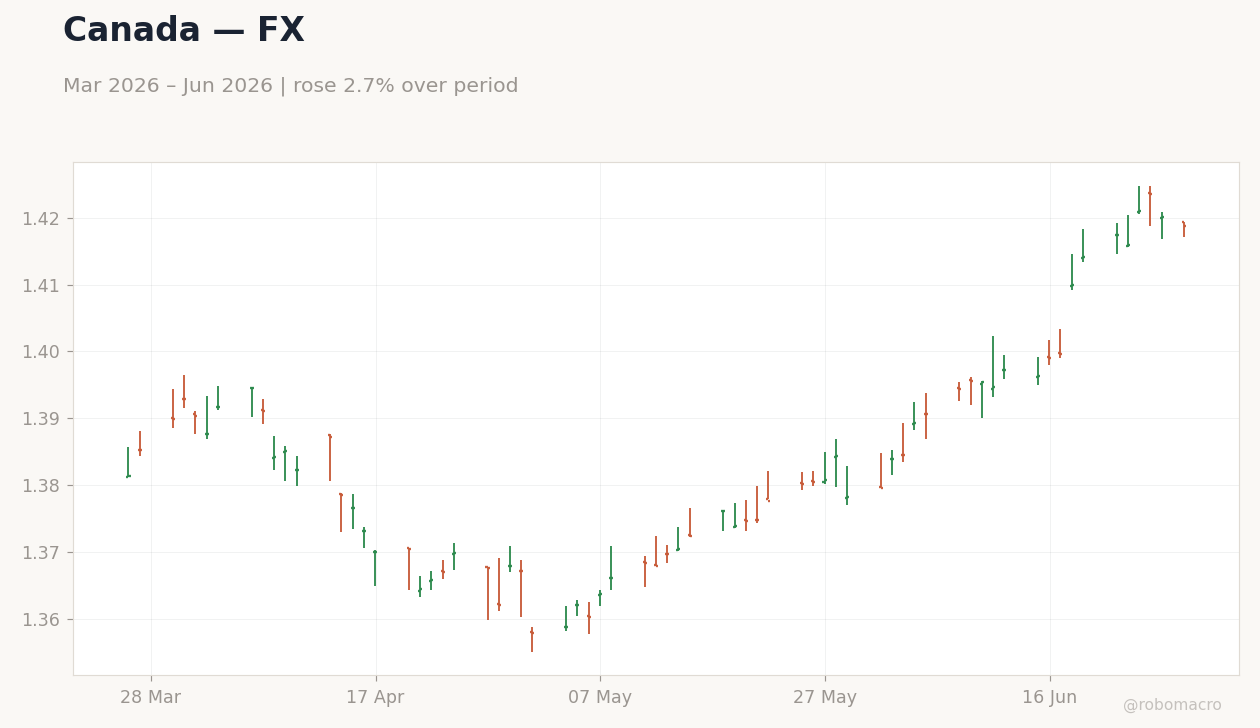
Asset prices reflected the mixed backdrop. The S&P/TSX closed the week at 34,980.00 after a net 0.06% decline, while USD/CAD held near 1.42 amid a 0.10% weekly rise. WTI Crude fell 7.47% to 69.23, extending the commodity pressure on the currency. Canada 2-year yields stayed steady and the 10-year yield held its ground.

Growth concerns persist alongside the inflation print. Prior-week context of subdued domestic demand and downward revisions to the medium-term growth outlook continued to frame the expansion as moderate. Retail and housing indicators remained soft, yet officials avoided recession language. The combination left the Bank of Canada on hold while external USD strength tightened financial conditions through the exchange-rate channel.

BoC Watch

The Bank of Canada maintained the policy rate after the May CPI overshoot, with Governor Macklem noting moderate growth ahead and warning of potential external imbalances. Deputy Governor Rogers’ speech provided no fresh forward guidance on the timing of easing. BoC OIS curves showed only modest shifts, retaining limited cuts priced by year-end despite the higher headline. The data reinforced a higher-for-longer stance relative to earlier expectations, consistent with the multi-week pattern of tolerating above-target prints to support activity. Speeches emphasized reaction-function stability rather than any imminent policy pivot.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Inflation Rate Year-over-Yea2.83.03.2
Core Inflation Rate Year-ove2.1-2.2
Inflation Rate Month-over-Mo0.400.801.0
CPI Common Year-over-Year2.52.52.7
CPI Median Year-over-Year2.12.12.1
CPI Trimmed-Mean Year-over-Y2.02.02.0
Core Inflation Rate Month-ov0.20-0.60
10-Year Bond Auction3.5-3.5
BoC Gov Macklem Speech---
BoC Rogers Speech---
Manufacturing Sales Month-ov4.2-1.1
BoC Summary of Deliberations--""
Average Weekly Earnings Year3.5-3.8
2-Year Bond Auction3.0-2.8
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-30GDP Month-over-Month-0.100.40
2026-06-30GDP Month-over-Month Prel0.40-
2026-07-01BoC Gov Macklem Speech--
2026-07-02S&P Global Manufacturing PMI Index--

The Week Ahead

The domestic calendar carries no high-impact releases, shifting focus to external data and any follow-up Governing Council commentary. Japan housing starts and construction orders on Monday will provide indirect signals on global demand that could influence commodity-linked CAD crosses. UK BoE Pill speech on the same day may affect rate-differential pricing versus the Bank of Canada. Mid-week euro-area and US activity prints will test whether resilience elsewhere continues to anchor global financial conditions tighter through the dollar. Markets will monitor energy prices for any reversal that could ease imported inflation pressures ahead of the next Bank of Canada decision. Overall, the absence of Canadian data keeps the rate path dependent on incoming global prints and any evolution in OIS-implied probabilities.

Risks & Themes

Hotter CPI raises the risk that inflation persistence delays easing more than current BoC OIS pricing reflects, particularly if gasoline effects prove sticky. Downside growth scenarios remain live given prior GDP contraction and demographic headwinds that continue to weigh on household formation. A sharper WTI decline could further pressure CAD and widen USD/CAD, tightening conditions without any BoC action. Markets appear to underprice the tension between above-target inflation and subdued domestic demand, leaving room for curve steepening if the next decision window approaches without fresh disinflation evidence.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Mexico
Market Scorecard
AssetLevelWoW
IPC Bolsa67226.01+0.1%
USD/MXN17.53+1.0%
EUR/MXN19.96+0.4%
WTI Crude69.23-7.5%
Silver59.67-8.9%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Bitcoin59402.01-6.1%
Chart 1
Chart 2
  • Banxico held the policy rate steady after Mexico inflation eased more than expected, leaving OIS curves pricing only limited near-term cuts.
  • The May trade balance missed consensus and narrowed relative to the prior surplus.
  • IPC Bolsa closed the week higher while USD/MXN rose amid a sharp drop in WTI crude.

Week in Review

Policy Hold Reinforced by Disinflation Mexican markets absorbed a steady Banxico decision that left the policy rate unchanged, consistent with the prior setting and market expectations. The move followed an inflation print that surprised to the downside, reinforcing the case for patience at the next meeting. The yield curve steepened, pricing only gradual easing ahead.

External Balances Weaken The May trade balance delivered a clear consensus miss and narrowed the surplus relative to the prior reading. This outcome occurred alongside continued nearshoring inflows and record remittances that had previously supported the current account. The data highlighted softening external momentum even as USMCA-related investment flows remained intact.

Equity and FX Divergence IPC Bolsa posted a modest weekly gain to close at 67226.01 after daily moves that included a rebound on June 25 and a subsequent decline. USD/MXN advanced 1.03 percent to 17.53 over the same period. EUR/MXN rose 0.38 percent to 19.96, reflecting peso underperformance against both the dollar and euro.

Commodity Channel Tightens Conditions WTI crude fell 7.47 percent to 69.23 while Brent declined 6.8 percent to 72.60, extending the disinflationary impulse visible in prior weeks. Silver dropped 8.93 percent and gold eased 2.05 percent, weighing on related equity sectors. These moves occurred against a backdrop of resilient US data that kept global rate expectations anchored higher.

Positioning Ahead of Quiet Close Markets entered the final trading day with light positioning after the Banxico announcement and trade balance release, leaving volatility contained. The combination of softer inflation, a policy hold, and external price relief supported a soft-landing narrative even as the peso absorbed dollar strength.

Banxico Watch

Banco de Mexico left the policy rate unchanged on June 25, aligning with consensus and the prior decision while markets parsed the statement for any adjustment in inflation guidance. The softer-than-expected inflation outcome broadened the window for maintaining the restrictive stance without immediate growth risks. Banxico OIS curves showed only modest repricing for cuts at the next meeting, consistent with the observed steepening in the yield structure. Data dependence remains the dominant theme, with the central bank tolerating above-target prints to support the expansion. Forward guidance continued to emphasize inflation convergence, leaving the terminal rate path data-dependent rather than pre-committed.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Economic Activity Month-over0.40-1.2
Economic Activity Year-over-1.41.92.3
Retail Sales Month-over-Mont0.10-0.80
Retail Sales Year-over-Year2.9-4.4
Mid-month Core Inflation Rat0.130.200.19
Mid-month Core Inflation Rat4.24.14.1
Mid-month Inflation Rate Mon-0.160.10-0.11
Mid-month Inflation Rate Yea4.13.83.5
Headline Unemployment Rate2.52.62.8
Central Bank Interest Rate D6.56.56.5
Trade Balance4.5bn4.6bn2.3bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-07-01Business Confidence Index47.5-
2026-07-03Consumer Confidence Index43.5-

The Week Ahead

The coming week features a light domestic calendar that leaves attention on external data and any USMCA-related commentary. Monday brings limited releases, keeping focus on how the prior trade balance miss informs external demand views. Mid-week updates on global growth indicators will matter for the peso and Mbono yields ahead of the next Banxico decision. Markets will monitor any signals on nearshoring momentum and remittances that could offset the recent surplus narrowing. The data flow should clarify whether the disinflationary impulse from lower commodity prices persists into coming quarters. OIS pricing for the upcoming decision is expected to remain stable absent large surprises, preserving the measured easing trajectory. Overall, the period reinforces data dependence that balances inflation convergence against growth support.

Risks & Themes

The sharp decline in WTI crude introduces downside risks to Pemex-linked revenues and fiscal accounts even as it aids near-term disinflation. Upside scenarios center on continued nearshoring FDI that could offset the trade balance shortfall and support the peso. Markets appear to underprice the persistence of US data resilience that keeps Banxico OIS curves from shifting aggressively toward cuts. Trade tensions around Chinese vehicles produced in Mexico add a layer of uncertainty to USMCA dynamics without immediate tariff triggers. The combination tilts the balance toward selective resilience rather than outright contraction, with the rate path remaining conditional on incoming inflation and activity prints.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Brazil
Market Scorecard
AssetLevelWoW
Bovespa173295.0+1.7%
USD/BRL5.17+0.4%
EUR/BRL5.88-0.2%
Vale15.07-4.1%
Petrobras16.29-4.2%
WTI Crude69.23-7.5%
Gold4096.3-2.0%
Bitcoin59406.83-6.1%
Chart 1
Chart 2
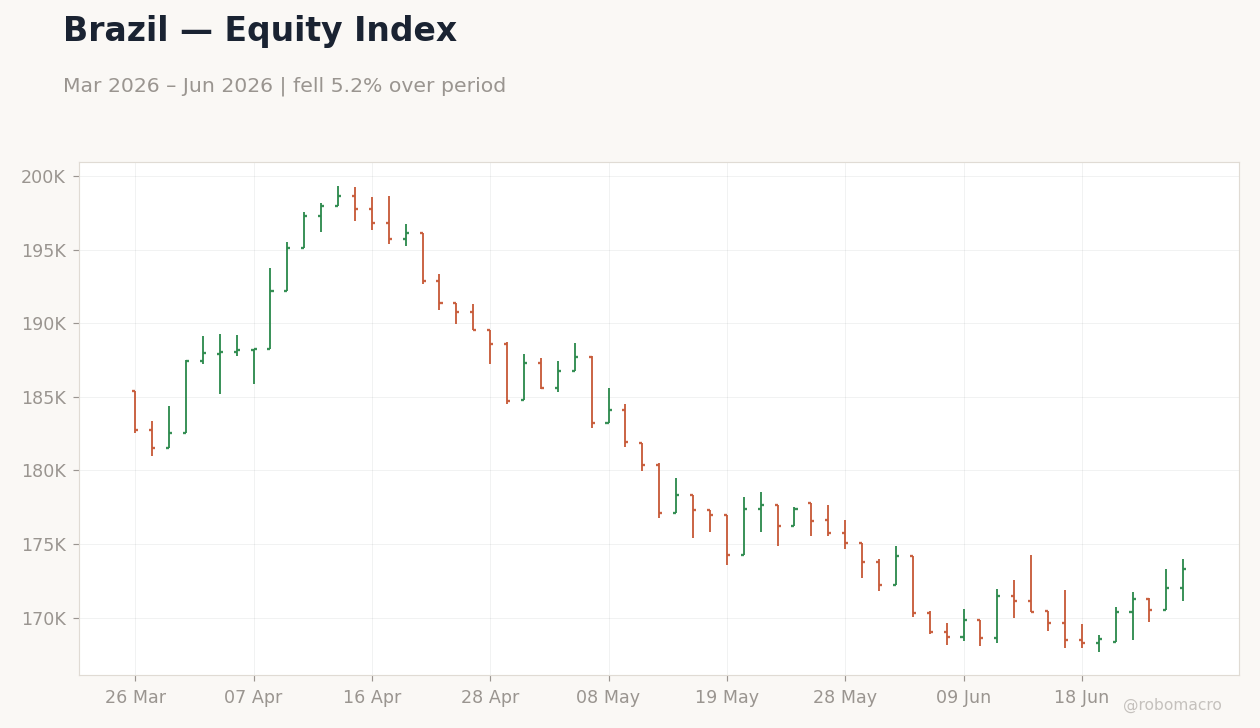
  • Bovespa rose 1.72 percent week-over-week while WTI Crude fell 7.47 percent, driving selective equity gains amid commodity weakness.
  • BCB OIS curves showed limited further easing priced for the next meeting amid external price moves.
  • No high-impact domestic data releases occurred during the week.

Week in Review

Labor Market Data Absent No employment figures were released. Markets instead responded to external commodity prices.

Policy Communication Remains Cautious Copom minutes published June 23-24 stressed that future adjustments will depend strictly on incoming inflation and activity data rather than a pre-set pace. Markets interpreted the language as hawkish relative to earlier expectations of faster easing, keeping BCB OIS forward pricing anchored near current levels.

Commodity-Driven Asset Rotation Equity and currency markets reflected external price moves more than domestic data. Bovespa advanced 1.72 percent across the week while Vale declined 4.07 percent and Petrobras fell 4.23 percent as WTI Crude dropped 7.47 percent. USD/BRL edged 0.37 percent higher despite the absence of offsetting domestic releases, illustrating the dominance of global oil and iron-ore flows.

Fiscal and External Pressures Persist Export volumes to the United States remained at multi-year lows following tariff changes.

Through-Line Across the Five Days The arc moved from post-decision volatility on June 22-23 to measured moves after external data. Commodity weakness offset the lack of domestic releases, leaving the real little changed on net and BCB OIS curves stable.

BCB Watch

Copom minutes released June 23-24 clarified that the committee reviewed multiple Selic paths before settling on the latest reduction and will calibrate future steps solely on inflation convergence and activity prints. The language explicitly flagged persistent services price pressures, tempering expectations for rapid further easing at the next meeting. BCB OIS curves shifted only modestly, with markets continuing to price limited cuts through year-end. External dollar strength and softer commodity revenues add upside risks to the inflation outlook, keeping the easing cycle measured.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
BCB Focus Market Readout--""
BCB Copom Meeting Minutes---
FGV Consumer Confidence88.8-88.7
IPCA mid-month CPI Month-ove0.620.440.41
IPCA mid-month CPI Year-over4.64.84.8
Current Account Balance-1.8bn-4.2bn-3.2bn
Foreign Direct Investment Fl8.9bn5.8bn8.0bn
Headline Unemployment Rate5.85.65.6
Week Ahead: Key Releases
DateReleasePriorCons.
2026-07-02Industrial Production Month-over-Mo0.70-
2026-07-03S&P Global Services PMI--

The Week Ahead

Attention centers on external data releases that will shape the inflation and growth backdrop for the next Copom decision. US activity and inflation prints scheduled early in the week will influence dollar and commodity trajectories, directly feeding into BRL volatility and fiscal revenue projections. Japan housing starts and UK BoE speeches on June 29 may affect global risk sentiment and OIS curves. Brazil faces no high-impact domestic releases through July 3, leaving markets to monitor iron-ore and oil price swings for signals on export earnings and trade balance momentum. Any follow-up Copom member comments will be parsed for confirmation that the data-dependent framework remains intact. The combination should keep BCB OIS pricing stable ahead of the upcoming decision, with downside risks to growth from weaker commodities balanced against contained labor-market readings.

Risks & Themes

Weaker-than-expected global commodity prices represent the dominant downside scenario for BRL and fiscal accounts, as evidenced by the 7.47 percent WTI decline this week. Upside risks center on continued labor-market strength that could delay further easing and support the real through domestic demand channels. Markets appear to underprice the persistence of services inflation flagged in the minutes, leaving BCB OIS curves vulnerable to upward repricing if core prints remain firm. Fiscal debt projections add duration pressure on longer-dated yields should external financing conditions tighten further. The data-dependent stance reduces the probability of a pre-committed easing path, limiting the scope for sharp front-end rallies even if activity data soften.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Argentina
Market Scorecard
AssetLevelWoW
MERVAL3123411.0-4.7%
USD/ARS1477.0+1.8%
EUR/ARS1681.52+4.2%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Soybean1156.25+3.6%
Bitcoin59402.01-6.1%
Chart 1
Chart 2
  • Q1 GDP growth surpassed consensus forecasts, confirming underlying resilience in agriculture and services despite rising unemployment.
  • Argentina secured new multilateral loans, directly supporting net international reserves ahead of upcoming obligations.
  • Soybean futures advanced while the S&P Merval declined week-over-week, highlighting commodity support offsetting equity pressure under the crawling peg.

Week in Review

Equity and FX Dynamics The S&P Merval closed the week lower after declining from the prior Friday, with the sharpest daily drop occurring on June 24 following MSCI’s confirmation of no change in market classification. USD/ARS rose over the seven days to finish at 1,477.00, extending the managed depreciation path at roughly the 1% monthly pace. EUR/ARS advanced, reflecting parallel moves in cross rates.

Growth and Fiscal Developments Argentina’s Q1 GDP print exceeded consensus expectations even as unemployment rose and real wages lagged, with the outperformance concentrated in agriculture and services. The government authorized new multilateral borrowing, explicitly aimed at strengthening reserves and lowering domestic financing costs. Treasury plans to roll over maturing debt via LETRAS and additional issuance supported primary surplus targets under the IMF programme.

Commodity and Reserve Flows Soybean futures climbed on renewed export demand, lifting expected tax collections and export registrations that feed directly into BCRA reserve accumulation. Brent crude fell, providing a modest disinflationary offset while gold moved lower. No INDEC releases occurred during the week, leaving market pricing driven by commodity proceeds and the new facility rather than fresh domestic data surprises.

Policy and Market Positioning The combination of stronger Q1 growth and multilateral inflows reinforced the view that fiscal consolidation remains on track, even as persistent recession pressures continue to weigh on household finances. Bitcoin declined, adding a mild risk-off tone that aligned with the equity sell-off but did not alter peso depreciation dynamics.

BCRA Watch

The BCRA maintained the crawling peg without adjustment, allowing USD/ARS to advance while soybean-driven export proceeds supported reserve rebuilding. No monetary policy meetings or forward guidance updates occurred, leaving OIS curves anchored to the existing 1% monthly pace. The new multilateral facility reduces immediate pressure on domestic issuance and preserves room for the BCRA to prioritize net international reserve targets ahead of the next IMF review. Weekly monetary aggregate releases due next week will provide the first read on liquidity conditions following the loan authorization. Market participants continue to monitor blue-chip swap levels for any signs of month-end demand that could test the peg’s credibility.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Headline Unemployment Rate7.5-7.8
GDP Growth Quarter-over-Quar0.60-0.70
GDP Growth Year-over-Year2.11.72.3
Current Account Balance2.3bn--1.7bn

The Week Ahead

Attention centers on the Treasury’s inflation-linked CER bond and dual-currency auctions scheduled for the opening session, targeting the rollover of maturing debt. Weekly BCRA reserve and monetary aggregate updates will offer the first post-loan read on net international reserves and liquidity. Soybean export registration data will be watched closely for signs of accelerated sales ahead of the harvest peak. No INDEC releases are listed through the period, shifting focus to fiscal cash-flow prints and any supplementary budget execution signals. Markets will assess whether the new facility alters near-term BCRA OIS pricing for the subsequent policy path. Global commodity moves, particularly soybean and Brent, remain key external drivers of reserve accumulation and peso stability into the following decision window.

Risks & Themes

The equity sell-off after the MSCI decision highlights downside risk to local asset prices if classification concerns persist, even as soybean strength provides an offset. Faster-than-expected reserve accumulation from the new loans could reduce devaluation pressure on the crawling peg, yet any slippage in primary surplus execution would reprice BCRA OIS curves higher. Upside scenarios center on sustained export-tax receipts supporting the current account, while downside risks include renewed Brent weakness that could widen the trade gap. Markets appear to be underpricing the durability of multilateral support relative to domestic recession signals, leaving room for repricing if Q2 activity data disappoint.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Colombia, Chile and Peru
Market Scorecard
AssetLevelWoW
MSCI Chile39.53-3.2%
MSCI Peru83.4-4.8%
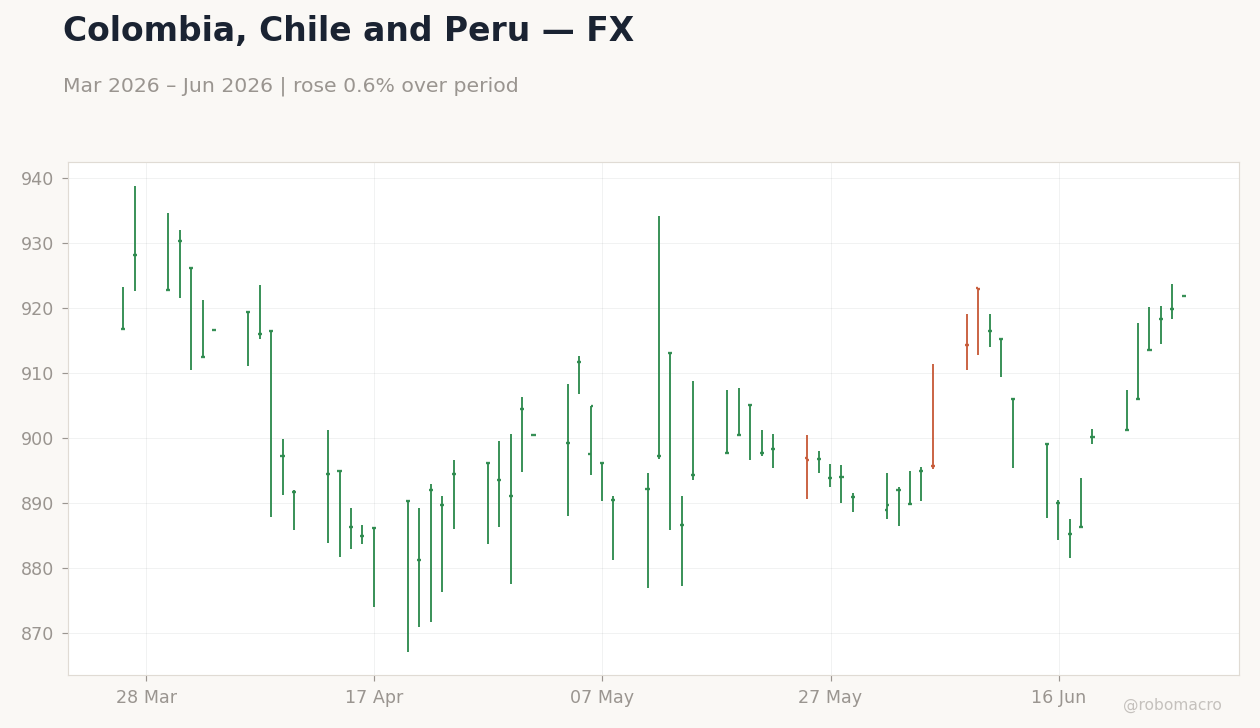
USD/COP3450.94+0.2%
USD/CLP921.85+2.3%
USD/PEN3.41+2.9%
Copper6.21-2.4%
Gold4096.3-2.0%
Brent Crude72.6-6.8%
Bitcoin59410.14-6.0%
Chart 1
Chart 2
  • Colombia’s presidential runoff delivered a narrow victory for Abelardo de la Espriella, driving USD/COP to 3,450.94 with only a 0.17 percent weekly gain while regional peers weakened more sharply.
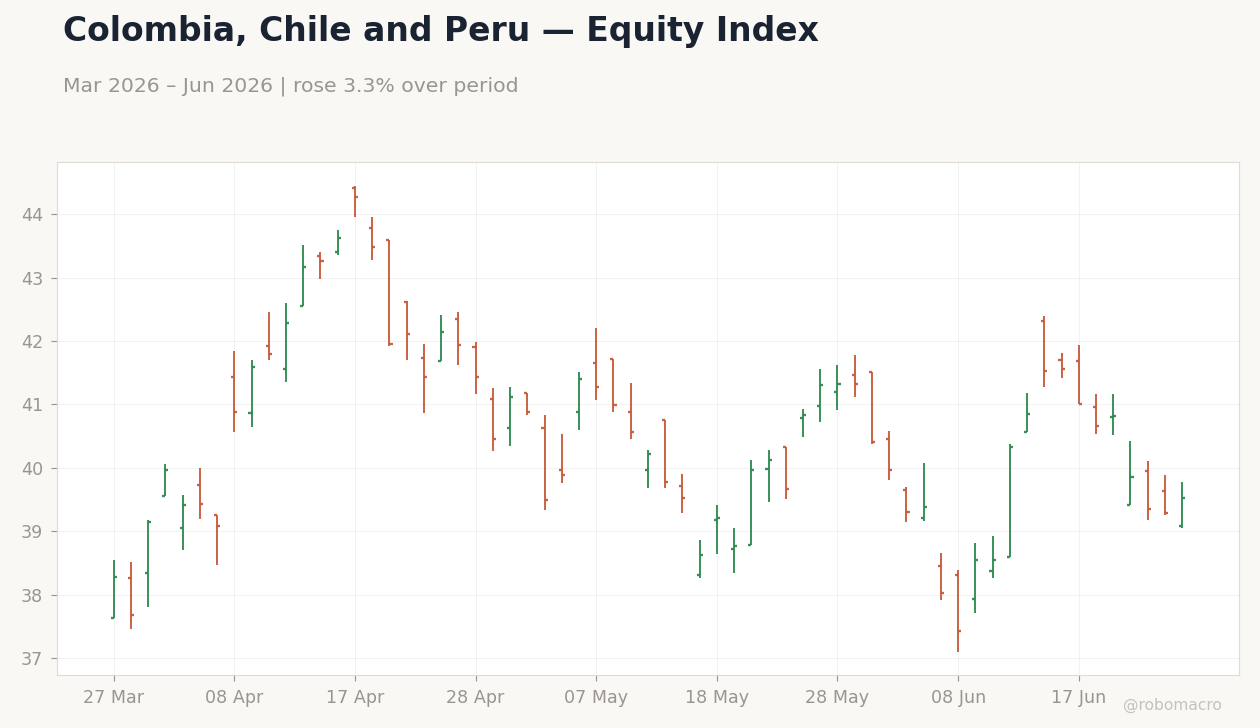
  • Copper fell 2.35 percent to 6.21 and Brent crude declined 6.8 percent to 72.60, producing MSCI Chile and MSCI Peru weekly losses of 3.16 percent and 4.81 percent respectively.
  • BCCh held the short-term rate unchanged with no BanRep or BCRP meetings or speeches recorded, leaving BanRep/BCCh/BCRP OIS curves little changed.

Week in Review

Election Outcome Reshapes Colombian Asset Pricing Colombia’s June 22 presidential runoff produced a narrow win for conservative Abelardo de la Espriella, triggering immediate repricing that left MSCI Colombia unchanged while USD/COP posted only a 0.17 percent weekly rise to 3,450.94. The outcome contrasted with prior weeks’ political uncertainty and reduced near-term external financing premia for Colombian assets.

Commodity Weakness Pressures Chile and Peru Copper’s 2.35 percent decline to 6.21 and Brent’s 6.8 percent drop to 72.60 weighed directly on mining-exposed equities, sending MSCI Chile down 3.16 percent to 39.53 and MSCI Peru lower by 4.81 percent to 83.40. USD/CLP rose 2.29 percent to 921.85 and USD/PEN advanced 2.85 percent to 3.41, widening the performance gap versus the more stable COP.

Absence of Domestic Data Leaves External Drivers Dominant No Tier-1 releases occurred in Colombia, Chile or Peru during the seven-day window, confirming the week’s narrative was driven entirely by commodity prices and the Colombian political result. Daily equity moves remained modest after the initial election reaction, with MSCI Chile posting successive daily declines before a modest rebound.

Fiscal and External Account Implications Emerge Lower Brent levels near 72.60 trimmed Colombia’s oil-linked fiscal buffer while copper at 6.21 reduced projected royalty inflows for both Chile and Peru. The peso’s relative outperformance narrowed Colombia’s current-account gap compared with CLP and PEN depreciation.

Risk Sentiment Spillovers Remain Contained Bitcoin’s 6.05 percent weekly decline to 59,410.14 added peripheral pressure but produced negligible direct read-through to Andean equities. Gold’s 2.05 percent fall to 4,096.30 offered limited offset for Peruvian and Colombian mining revenues.

Through-Line Centers on Selective Political Relief The data arc shows Colombian assets decoupling from regional commodity beta after the June 22 result, while Chile and Peru remained fully exposed to the 2.35 percent copper and 6.8 percent Brent declines. No consensus misses materialized because no domestic prints were scheduled.

Andean Central Banks Watch

BanRep, BCCh and BCRP maintained unchanged policy settings with the Chile short-term rate fixed and no meetings or forward-guidance updates recorded. The absence of inflation or activity surprises left BanRep/BCCh/BCRP OIS curves anchored, pricing no near-term shifts ahead of the next decisions. Commodity-driven currency moves widened external financing differentials but did not alter central-bank reaction functions given stable domestic data. Markets therefore continue to price measured easing paths contingent on future inflation moderation rather than immediate responses to copper or Brent volatility.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Imports Year-over-Year11.1-15.8
Trade Balance-840.0mn--2.1bn
Producer Price Index Year-ov17.7-20.5

The Week Ahead

The coming session features no scheduled releases for Colombia, Chile or Peru, keeping attention on external commodity prices and any early signals from the incoming Colombian administration. Copper and Brent price action will continue to drive daily CLP and COP moves while PEN remains range-bound near 3.41. Investors will monitor global risk sentiment for potential effects on Andean equity beta ahead of the next BanRep, BCCh and BCRP decisions. Any certification updates on the Colombian vote could produce limited sovereign-spread tightening. External demand indicators from major trading partners will shape expectations for coming-quarters current-account balances and royalty revenues. OIS pricing is expected to stay stable absent fresh domestic data that could alter rate-path probabilities.

Risks & Themes

Copper’s further decline risks widening Chile’s and Peru’s current-account gaps beyond levels already implied by the 2.35 percent weekly drop, while Brent near 72.60 caps Colombia’s fiscal surplus. The market may be under-pricing the durability of the Colombian political shift if early policy signals disappoint, reopening external financing premia. Upside scenarios center on copper stabilization supporting royalty inflows and narrowing CLP/PEN depreciation; downside cases involve additional commodity weakness that forces faster BanRep/BCCh/BCRP OIS repricing. The week’s data shift reinforces a higher-for-longer regional rate outlook until inflation prints confirm sustained moderation.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
United Kingdom
Market Scorecard
AssetLevelWoW
FTSE 10010508.0+0.7%
FTSE 25023147.2-0.2%
GBP/USD1.32-0.1%
GBP/EUR1.16+0.7%
GBP/JPY213.7+0.2%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
UK Nat Gas3.28+0.8%
Bitcoin59428.9-6.0%
Chart 1
Chart 2
Chart 3
  • Flash PMIs delivered the clearest downside surprise of the week as services contracted while manufacturing eased.
  • FTSE 100 closed the week at 10508.0, up 0.67 percent, while 10-year gilt yields rose after reduced near-term easing bets.
  • Multiple BoE speakers including Breeden, Taylor, Dhingra and Pill offered no material shift in guidance, leaving OIS curves anchored.
  • Brent crude fell 6.8 percent to 72.6, reinforcing external disinflation while GBP/USD ended at 1.32 with only modest weekly net change.

Week in Review

PMIs signal services contraction. The week opened with S&P Global flash prints that missed across both sectors, confirming a sharper slowdown in services activity than markets had priced. Manufacturing PMI eased while services fell, marking the first contraction reading in several quarters. These outcomes followed the prior week’s contained inflation prints and reinforced the view that domestic demand is cooling faster than the Bank of England’s latest projection.

CBI surveys confirm industrial weakness. CBI Industrial Trends Orders deteriorated versus consensus, extending the prior reading and highlighting softening order books. The subsequent CBI Distributive Trades release also missed, pointing to further contraction in consumer-facing demand. Together these releases shifted the narrative from selective resilience to broad-based softening within the domestic cycle.

Political noise and BoE communications. Political developments added a layer of uncertainty that weighed on sterling crosses early in the week. Multiple Bank of England speakers delivered remarks without altering the gradual easing bias. Markets responded by trimming cut probabilities, lifting 10-year gilt yields.

Cross-asset repricing. Equities recovered modestly into month-end while Brent crude extended its decline, providing an external disinflationary impulse. Sterling posted limited net movement against the dollar at 1.32, reflecting the balance between softer domestic data and firmer global risk sentiment. The week therefore closed with clearer evidence that UK growth momentum is fading while inflation remains above target.

BoE Watch

Bank of England speakers Breeden, Taylor, Dhingra and Pill addressed markets across the week without shifting the committee’s gradual easing bias. Remarks focused on inflation persistence and the need to monitor services activity after the PMI contraction. No fresh forward guidance altered market pricing for the next policy decision. The softer flash PMIs and CBI prints reinforce the view that growth risks have tilted lower, yet above-target inflation continues to limit the pace of any easing cycle. OIS curves therefore show only modest repricing for near-term moves. The Bank’s analysis that Brexit reduced output continues to weigh on medium-term potential growth estimates. Overall the communications kept policy expectations anchored while data dependence remains the dominant theme.

Data Review

The S&P Global Manufacturing PMI Flash missed consensus, indicating a modest loss of momentum in the factory sector. The Services PMI Flash delivered a larger downside surprise, confirming contraction for the first time in several quarters. These prints together suggest the services-led expansion that supported earlier growth is now reversing. The CBI Industrial Trends Orders balance fell versus consensus, underscoring weaker industrial demand. CBI Distributive Trades then missed expectations, pointing to further deterioration in retail and wholesale activity. Taken together the data releases indicate the UK economy is moving into a softer patch of the cycle with growth below the Bank of England’s latest forecast. Inflation and unemployment continue to constrain the scope for aggressive easing. The combination leaves the BoE OIS curve pricing only gradual cuts over the medium term.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Prime Minister Starmer Speec---
S&P Global Manufacturing PMI53.953.853.1
S&P Global Services PMI Flas49.350.548.7
S&P Global Composite PMI Fla49.750.649.4
BoE Breeden Speech---
CBI Industrial Trends Orders-41.0-35.0-45.0
BoE Taylor Speech---
BoE Dhingra Speech---
Treasury Gilt 2031 Auction4.7-4.3
BoE Breeden Speech---
BoE Dhingra Speech---
BoE Pill Speech---
Car Production Year-over-Yea-0.70-3.2
Treasury Gilt 2029 Auction4.4-4.1
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29BoE Pill Speech--
2026-06-29BoE Consumer Credit1.9bn-
2026-06-29Mortgage Approvals66K63K
2026-06-29Mortgage Lending Level4.4bn-
2026-06-30Current Account Balance-18.4bn-18.5bn
2026-06-30Nationwide Housing Prices Month-ove-0.600
2026-06-30Nationwide Housing Prices Year-over1.7-
2026-06-30BoE Breeden Speech--
2026-07-01BoE Gov Bailey Speech--
2026-07-02BoE Mann Speech--
Chart 6
Chart 7

The Week Ahead

Monday brings BoE Pill speech at 01:00, which markets will parse for any update on the inflation outlook after the PMI weakness. No high-impact data releases are scheduled through mid-week, leaving sterling and gilt futures sensitive to further MPC member comments. Thursday offers limited UK-specific indicators while attention turns to month-end positioning. Consensus expectations for any follow-up surveys remain subdued given the recent contraction signals. The releases matter because they will update the growth and inflation backdrop ahead of the next Bank of England meeting. Central bank speakers carry elevated weight in the absence of fresh hard data. Overall the week is expected to remain data-light but policy-sensitive.

Risks & Themes

The PMI and CBI misses shift the outlook toward downside growth risks while above-target inflation keeps upside inflation risks in focus. Markets appear to have underpriced the speed of services contraction, creating potential for further gilt yield volatility. Positioning in sterling crosses remains light after the limited weekly move in GBP/USD to 1.32. An upside scenario would require stronger-than-expected distributive trades or hawkish BoE comments that re-anchor rate expectations higher. A downside scenario centers on further services weakness feeding into softer Q2 GDP prints and earlier BoE OIS repricing. Flow considerations favor defensive positioning into the holiday-shortened week ahead.

Cross-Asset

The FTSE 100 ended the week at 10508.0, up 0.67 percent, after closing Monday at 10428.9 and recovering through Thursday’s 10529.9 print. The FTSE 250 finished at 23147.2, down 0.21 percent week-over-week. The 10-year gilt yield rose on reduced easing expectations. GBP/USD closed at 1.32 with a weekly net change of -0.08 percent, while GBP/EUR rose 0.70 percent to 1.16. Brent crude declined 6.8 percent to 72.6, extending the prior week’s move lower, while gold fell 2.05 percent to 4096.3. Bitcoin dropped 6.02 percent to 59428.9 amid broader risk-off flows. Daily moves showed the sharpest equity pressure on Monday and Tuesday before modest stabilization into month-end.

Global Context

US data resilience continues to shape global rate paths, with the dollar channel transmitting tighter financial conditions to the United Kingdom. Brent crude’s 6.8 percent weekly decline to 72.6 adds an external disinflationary impulse that partially offsets domestic inflation persistence. European officials stressed unity on trade policy, indirectly supporting UK export sentiment amid ongoing EU-UK sanitary and phytosanitary discussions. Geopolitical developments including fresh US-Iran tensions added to risk-off flows that pressured gold and bitcoin. Overall the last seven days reinforced selective DM resilience alongside shared data dependence across central banks.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Sweden, Norway, Denmark and Finland
Market Scorecard
AssetLevelWoW
OMX Stockholm 303153.55-1.2%
Oslo Bors1900.57-2.4%
OMX Copenhagen 251800.88+0.5%
OMX Helsinki 256143.93-2.9%
USD/SEK9.73+1.5%
USD/NOK9.91+2.2%
EUR/SEK11.09+0.9%
EUR/NOK11.32+1.8%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
Bitcoin59412.97-6.0%
Chart 1
Chart 2
  • Brent crude fell 6.8 percent to 72.6 over the week, driving Oslo Bors down 2.37 percent to 1,900.57 and USD/NOK higher by 2.21 percent to 9.91.
  • OMX Helsinki 25 declined 2.87 percent to 6,143.93 while OMX Copenhagen 25 rose 0.51 percent to 1,800.88, highlighting equity divergence tied to euro-area sentiment and energy exposure.
  • Riksbank June minutes revealed internal divisions on easing pace amid higher Swedish producer prices, leaving Riksbank OIS curves with limited near-term repricing.

Week in Review

Equity and Currency Divergence Under Oil Pressure Nordic equity markets closed the week with clear splits as Brent crude declined 6.8 percent to 72.6, weighing most heavily on energy-linked names. Oslo Bors fell 2.37 percent to 1,900.57 while OMX Helsinki 25 dropped 2.87 percent to 6,143.93; OMX Stockholm 30 ended 1.16 percent lower at 3,153.55. OMX Copenhagen 25 provided the sole advance, rising 0.51 percent to 1,800.88. The Norwegian krone and Swedish krona both weakened, with USD/NOK rising 2.21 percent to 9.91 and USD/SEK climbing 1.52 percent to 9.73. EUR/NOK advanced 1.81 percent to 11.32. These moves occurred against a backdrop of no Tier-1 Nordic data releases, leaving external oil and risk sentiment as the dominant drivers.

Policy Signals and Yield Stability Riksbank June minutes released mid-week pointed to board divisions on the speed of future easing, consistent with higher Swedish producer prices. Sweden and Norway 10-year yields held steady. Norges Bank maintained its prior hold stance, with no fresh speeches altering the path. Danish and Finnish markets tracked euro-area developments closely, reflecting the currency peg and ECB transmission. The absence of domestic releases kept focus on global flows and Brent’s 6.8 percent weekly decline.

Growth and External Demand Context Export-oriented sectors in Sweden and Denmark faced mixed external signals amid softer euro-area sentiment. Norwegian fiscal balances stayed supported by Brent near 72.6 despite the weekly drop. Finnish retail sales and housing data offered limited new signals, aligning with the broader mid-expansion narrative from prior weeks. Barclays noted modest consolidation potential in both SEK and NOK on any improvement in growth prints. Overall activity showed resilience without synchronized easing signals across the four economies.

Nordic Central Banks Watch

Riksbank June minutes highlighted internal splits on easing pace, with hotter producer prices supporting arguments for caution. Norges Bank held policy steady, leaving Norges Bank OIS curves showing only modest shifts toward later cuts as Brent fell to 72.6. Danmarks Nationalbank maintained its peg to the euro without fresh intervention data. Bank of Finland followed ECB signals, with the deposit rate unchanged and limited OIS repricing across the region. The data reinforced data dependence rather than near-term policy changes.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Consumer Confidence Index-19.8--14.0
Loan Growth Year-over-Year4.4-4.5
Business Confidence Index93.5-90.8
265-Day T-Bill Auction--2.0
Export Prices Year-over-Year3.7-6.4
Headline Unemployment Rate11.6-12.7
Import Prices Year-over-Year6.7-8.2
Producer Price Index Year-ov4.6-7.4
Retail Sales Month-over-Mont-1.8-1.0
Retail Sales Year-over-Year1.4-3.8
Headline Unemployment Rate4.6-4.4
Monetary Policy Meeting Minu---
06/2036 NGB Auction4.4-4.3
10/2042 Ngb Auction--4.3

The Week Ahead

Monday brings Finland Business Confidence Index and Consumer Confidence Index alongside UK BoE Pill speech. Tuesday features limited Nordic releases, keeping attention on any Riksbank or Norges Bank follow-up comments. Wednesday includes potential Norway oil production figures that could influence NOK flows. Thursday may see Danish and Finnish markets track euro-area PMI prints for ECB rate-path implications. Friday closes the period with month-end positioning and any final speeches ahead of upcoming decisions. Markets will assess whether Brent stabilization near 72.6 alters Norges Bank OIS pricing or supports SEK rebound. The releases matter for confirming whether external demand resilience persists into coming quarters without forcing earlier policy adjustments.

Risks & Themes

Brent’s 6.8 percent drop raises downside risks for Norwegian fiscal flows and NOK stability if energy prices extend lower. Riksbank policy divisions could produce volatility in SEK if minutes are read as signaling faster easing than priced. Upside scenarios center on any growth-print improvement that supports krona and krone consolidation per Barclays forecasts. Markets appear to underprice the persistence of above-target inflation prints across DM economies, leaving OIS curves vulnerable to further repricing higher if US data resilience continues. Selective equity outperformance in Copenhagen suggests rotation potential if euro-area sentiment stabilizes.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Poland, Czech Republic, Hungary, Romania and Turkey
Market Scorecard
AssetLevelWoW
BIST 10014274.0-3.1%
iShares Poland38.27-2.8%
EUR/PLN4.28+0.7%
EUR/HUF353.37+0.8%
EUR/CZK24.23+0.2%
USD/TRY46.59+0.3%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
Bitcoin59419.08-6.0%
Chart 2
  • Turkey’s Consumer Confidence Index rose in June from the prior reading, beating expectations and marking the first gain in three months.
  • Poland’s headline unemployment rate improved modestly while matching consensus. Hungary’s central bank delivered a modest rate cut.
  • BIST 100 fell 3.09 percent to 14,274.00 week-over-week and iShares Poland declined 2.77 percent to 38.27 amid Brent crude’s 6.8 percent drop to 72.60.
  • EUR/PLN rose 0.7 percent to 4.28 and EUR/HUF advanced 0.83 percent to 353.37 as regional central banks navigated divergent inflation and growth signals.

Week in Review

Labor market shows resilience Poland’s unemployment rate improved modestly, matching the consensus forecast. The print reinforced steady labor demand despite manufacturing caution flagged in business sentiment indices. Turkey’s consumer confidence climbed, the first sequential gain since March, pointing to household adaptation amid still-elevated inflation.

Policy divergence emerges in Hungary Hungary’s central bank reduced its key rate, citing forint appreciation and cooling price pressures. The move contrasted with the broader global tightening tilt visible in US rate expectations. Hungary’s 10-year yield fell following the decision and debt-management changes.

Equity and commodity pressure weighs on sentiment BIST 100 closed the week at 14,274.00 after a 3.09 percent decline, while iShares Poland slipped 2.77 percent to 38.27. Brent crude’s 6.8 percent drop to 72.60 added downside pressure to energy importers across the five economies. EUR/PLN advanced 0.7 percent to 4.28 and EUR/HUF rose 0.83 percent to 353.37 on positioning ahead of the Polish labor print.

ECB convergence gaps remain wide The ECB’s latest assessment showed Poland, Czech Republic, Hungary and Romania still miss euro-adoption criteria on price stability, fiscal metrics and legal compatibility. Regional equity and FX moves reflected thin summer liquidity and limited follow-through from the report. Overall, the week reinforced selective domestic resilience offset by external commodity and dollar-driven headwinds.

Emerging Europe Central Banks Watch

Hungary’s central bank delivered the widely expected modest reduction, highlighting forint stability and subdued inflation as the rationale for further easing room. NBP held policy steady with no new signals during the week, consistent with the unemployment print matching consensus. CNB, BNR and CBRT also refrained from fresh moves or explicit forward guidance.

The ECB convergence report underscored persistent gaps in price stability and legal compatibility for the four EU members, limiting near-term euro-adoption momentum. Hungary’s rate cut diverges from the higher-for-longer tilt visible in US OIS curves, reflecting domestic forint appreciation. Data releases this week therefore tilt the medium-term path toward measured easing in Hungary while leaving NBP, CNB and BNR on hold. CBRT continues to monitor USD/TRY stability near 46.59 for any intervention signals.

Data Review

Turkey’s Consumer Confidence Index printed at 87.9 versus the prior 85.8 reading, exceeding the modest sequential improvement markets had anticipated. The beat signaled household resilience even as inflation pressures persist. Poland’s headline unemployment rate came in in line with consensus and below the prior month.

The labor-market stability aligns with earlier NBP communications that growth remains supported by domestic demand. No other high-impact releases occurred across Czech Republic, Hungary or Romania during the week. Hungary’s central bank delivered a modest rate cut as expected and was framed around forint gains rather than outright growth concerns.

Brent’s 6.8 percent decline to 72.60 eased imported-energy costs, supporting the disinflation narrative visible in Hungary’s policy decision. The combination of contained unemployment and rising Turkish confidence points to a mid-cycle expansion that remains intact but vulnerable to external price shocks. Data dependence therefore continues to dominate rate-path expectations for NBP, CNB, MNB, BNR and CBRT.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Business Confidence Index-4.1--6.0
Corporate Sector Wages Year-5.46.05.8
Employment Growth Year-over--0.90-0.90-0.90
Producer Price Index Year-ov2.12.52.4
Retail Sales Year-over-Year1.33.83.0
External Debt234.4bn-238.1bn
3-Month Dtb Auction5.5-5.5
Central Bank Interest Rate D6.26.06.0
Deposit Interest Rate5.25.05.0
M3 Money Supply Year-over-Ye11.311.411.0
Business Confidence Index99.0-99.8
Consumer Confidence Index103-106
Headline Unemployment Rate6.05.95.9
Headline Unemployment Rate4.5-4.3
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-30Inflation Rate Year-over-Year Preli3.1-

The Week Ahead

No high-impact data releases are scheduled for Poland, Czech Republic, Hungary, Romania or Turkey between June 29 and July 3. Markets will instead focus on central-bank speakers and any follow-through from the ECB convergence assessment. Monday features low-impact producer-price and business-confidence prints in Malaysia and Finland that carry limited regional read-through.

Tuesday brings Japanese housing starts and UK BoE Pill speech, both of which may influence global rate expectations and spill into CEE FX. Wednesday includes potential comments from MNB Governor Varga on the scope for additional cuts. Thursday and Friday remain quiet on the data calendar, leaving positioning in EUR/PLN and EUR/HUF sensitive to euro-area developments. Traders will also monitor any CBRT signals on intervention amid USD/TRY stability near 46.59. The quiet week should keep volatility contained unless external commodity or dollar moves accelerate.

Risks & Themes

The week’s data shift the outlook toward selective easing in Hungary while reinforcing data dependence elsewhere. Upside risks center on further Turkish confidence gains and Polish labor-market stability that could support domestic demand. Downside risks stem from Brent’s continued decline and any renewed dollar strength that tightens financial conditions through the FX channel.

Market positioning appears light ahead of the holiday period, with limited OIS repricing visible in NBP or CNB curves. Mispricing signals are most evident in Hungarian yields, which fell sharply after the central bank cut despite still-elevated regional inflation prints. Volatility remains subdued but could rise quickly on any ECB or Fed speaker surprises that alter global rate expectations.

Cross-Asset

Equities closed lower across the region, with BIST 100 falling 3.09 percent to 14,274.00 and iShares Poland declining 2.77 percent to 38.27.

Bonds showed divergence: Poland’s 10-year yield rose while Hungary’s 10-year yield fell after the central bank decision. FX markets saw EUR/PLN advance 0.7 percent to 4.28 and EUR/HUF climb 0.83 percent to 353.37. EUR/CZK edged up 0.22 percent to 24.23 and USD/TRY rose 0.29 percent to 46.59.

Commodities delivered the clearest downside move as Brent crude dropped 6.8 percent to 72.60, while gold fell 2.05 percent to 4,096.30. Bitcoin declined 6.04 percent to 59,419.08. The cross-asset configuration reflected risk-off flows and commodity relief rather than synchronized regional stress.

Global Context

US data resilience continues to anchor global rate expectations higher, with the first Fed cut now priced no earlier than mid-2027. Brent’s 6.8 percent drop to 72.60 extended the disinflationary impulse visible across energy importers in CEE and Turkey. Euro-area sentiment indicators showed modest improvement but have not yet translated into synchronized easing signals from the ECB.

Trade linkages remain tight, leaving Poland and Czech Republic exposed to any further German wholesale-price contraction. Geopolitical tensions between Poland and Ukraine showed limited market impact this week but continue to shape longer-term fiscal priorities. Overall, external commodity relief and dollar stability provided the dominant cross-border spillover for the five economies.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
South Africa
Market Scorecard
AssetLevelWoW
JSE Top 4058.99-2.2%
USD/ZAR16.45-0.0%
EUR/ZAR4096.3-2.0%
Platinum18.72-0.7%
Gold59429.11-6.0%
Brent Crude72.6-6.8%
Naspers79953.0-2.4%
Bitcoin59429.11-6.0%
Chart 1
Chart 2
  • JSE Top 40 fell 2.24 percent week-over-week to close at 58.99 amid sustained commodity price weakness, with platinum declining to 18.72 and Brent crude reaching 72.6.
  • USD/ZAR held near 16.45 after touching a one-month low of 16.55, reflecting broad dollar strength against emerging-market currencies and limited domestic data support.
  • SARB commentary emphasized that sustained lower inflation combined with credible fiscal consolidation offers the clearest path to reduced borrowing costs.

Week in Review

Equity and commodity pressure dominates flows. South African equities closed the week lower as the JSE Top 40 declined 2.24 percent to 58.99. Resource names faced direct headwinds from platinum falling to 18.72 and Brent crude settling at 72.6, both posting weekly declines exceeding 6 percent. The absence of any Stats SA releases left price action driven entirely by external flows rather than domestic surprises.

Rand resilience tested by dollar strength. USD/ZAR closed at 16.45 after reaching 16.55 mid-week, marking the weakest level in over a month and producing a net weekly change near zero. EUR/ZAR moved lower. This configuration shows limited SARB OIS repricing despite the currency move.

Yield curve steepening signals fiscal focus. The long-term rate climbed, widening the spread versus the short-term rate and aligning with SARB statements that lower inflation plus fiscal reform are prerequisites for cheaper borrowing. Naspers closed at 79953.0 after a 2.39 percent weekly decline, providing only partial offset to the broader index.

Data vacuum reinforces external dependence. With zero South African economic events recorded across the five trading days, markets priced global dollar direction and commodity swings directly into local assets. Gold moved to 59429.11 while Bitcoin fell to 59429.11, mirroring the risk-off tone seen across emerging markets.

Policy signals remain consistent with prior weeks. The SARB’s repeated focus on inflation within the 3-6 percent band and offshore payment scrutiny kept near-term rate expectations stable, consistent with the trimming of hike probabilities noted after the earlier below-consensus CPI print. Overall, the week confirmed that South African assets continue to trade as a function of US policy spillovers and commodity cycles rather than domestic catalysts.

SARB Watch

The SARB highlighted that sustained lower inflation together with credible fiscal consolidation remains essential to cut borrowing costs, leaving the policy rate steady. No MPC speakers appeared and no minutes were released, so markets took direction from the central bank’s emphasis on offshore payment rules aimed at curbing money laundering. SARB OIS curves showed only marginal shifts, with the data vacuum preventing any material repricing of the next decision. The combination of stable short-term rates and a higher long-term yield suggests markets continue to price a gradual path that tolerates external volatility provided domestic inflation stays contained.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
182-Day T-Bill Auction7.5-7.5
273-Day T-Bill Auction7.8-7.7
364-Day T-Bill Auction7.8-7.8
91-Day T-Bill Auction7.3-7.2
Leading Business Cycle Indic1.5--1.8
Consumer Confidence Index-7.0--19.0
2033 Bond Auction8.2-8.1
2039 Bond Auction9.1-8.8
2042 Bond Auction9.3-9.0
Producer Price Index Month-o3.0-2.6
Producer Price Index Year-ov4.86.77.8
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-30Trade Balance15.2bn-

The Week Ahead

Attention will center on any SARB commentary around the next meeting, with markets watching for further signals on how fiscal consolidation and inflation outcomes will shape the rate path. Leading business indicator data and consumer confidence prints are expected to provide the first domestic read-through on household and corporate sentiment after recent fuel-price pressure. Global risk sentiment and US dollar moves will likely dictate rand flows ahead of upcoming decisions, given the empty domestic calendar. Commodity price rebounds could support mining equities and ease pressure on export earnings, while any escalation in regional diplomatic tensions may weigh on capital inflows. OIS pricing will respond to whether incoming data confirm or challenge the SARB’s current forward guidance on inflation within the target band over coming quarters.

Risks & Themes

The week’s external-driven moves highlight downside risks to growth if commodity weakness persists and the dollar remains elevated, potentially widening the current-account gap in coming quarters. Upside scenarios hinge on a softer US policy signal that could ease rand pressure and allow the SARB to maintain its measured stance. Markets appear to underprice fiscal slippage risks given the steepening yield curve and ongoing expenditure concerns, which could force faster consolidation than currently embedded in OIS curves. Xenophobic tensions and related regional frictions add a further layer of uncertainty to investment flows that the data do not yet capture.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Australia and New Zealand
Market Scorecard
AssetLevelWoW
ASX 2008764.2-0.6%
NZX 5013495.24+0.4%
AUD/USD0.69-1.4%
NZD/USD0.56-1.6%
AUD/NZD1.22+0.1%
BHP58.99-2.2%
Gold18.72-0.7%
Brent Crude72.6-6.8%
Bitcoin72.6-6.8%
Chart 1
Chart 2
  • Australian employment rebounded while the unemployment rate held steady, offsetting a headline CPI miss and reinforcing RBA data dependence.
  • Core trimmed-mean CPI rose, keeping the cash rate under review for possible further adjustment despite softer headline prints.
  • AUD/USD fell 1.45 percent week-over-week to 0.69 amid broad USD strength and limited RBNZ signals, with ASX 200 closing 0.59 percent lower at 8764.2.

Week in Review

Activity indicators firm while inflation shows mixed signals. Australian S&P Global manufacturing and services PMIs both exceeded prior readings and pointed to modest expansion. These prints aligned with a sharp labor-market rebound that added jobs and full-time positions, leaving the unemployment rate unchanged. The data arc therefore showed activity resilience that tempered earlier concerns about cooling momentum.

Inflation trends produced a split outcome. Headline CPI declined month-over-month and year-over-year, both below consensus, yet RBA trimmed-mean measures lifted. The combination left underlying price pressures elevated and supported the RBA’s decision to hold the cash rate with the door open to further tightening. Commodity price weakness, including Brent crude falling 6.8 percent to 72.6, added external disinflation but did not alter the core trajectory.

Markets reflected the policy repricing. The ASX 200 ended the week 0.59 percent lower at 8764.2 while AUD/USD declined 1.45 percent to 0.69, driven by Fed rate expectations and limited RBNZ commentary. NZX 50 posted a modest 0.37 percent gain to 13495.24 with no major domestic releases. Overall, the week confirmed selective resilience in Australia that challenges near-term easing bets while New Zealand data remained quiet.

Cross-asset moves reinforced the higher-for-longer narrative. Australian 10-year yields stayed elevated and BHP shares fell 2.24 percent to 58.99 amid softer iron-ore sentiment. The through-line across the four days was therefore one of labor-market strength and core inflation persistence overriding headline softness.

ANZ Central Banks Watch

The RBA held the cash rate with hawkish forward guidance intact after trimmed-mean CPI rose. Governor Bullock’s speech reinforced data dependence without shifting the bias, while Assistant Governor Hauser highlighted labor-market resilience. RBA OIS pricing showed only modest adjustment for near-term cuts, leaving the next decision path anchored to upcoming inflation and activity prints. RBNZ remained silent, producing no material shift in NZ OIS curves and preserving the divergence narrative versus the RBA. The week’s core inflation outcome therefore tilted the balance toward a later rather than earlier easing cycle for both banks.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
S&P Global Manufacturing PMI50.7-51.2
S&P Global Services PMI Flas48.7-49.9
S&P Global Composite PMI Fla48.7-49.8
1-Year Bill Auction3.0-3.0
3-Month Treasury Bill Auctio2.5-2.6
6-Month Treasury Bill Auctio2.7-2.7
Inflation Rate Month-over-Mo0.40-0.30-0.70
Inflation Rate Year-over-Yea4.24.44.0
RBA Trimmed Mean CPI Month-o0.300.300.40
RBA Trimmed Mean CPI Year-ov3.43.53.6
Consumer Price Index103-102
RBA Weighted Median CPI Mont0.30-0.40
RBA Weighted Median CPI Year3.4-3.6
RBA Hauser Speech---
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29RBA Kent Speech--
2026-06-29ANZ Business Confidence10.0-
2026-06-29RBA Meeting Minutes--
2026-06-30Ai Group Industry Index-26.5-
2026-06-30Building Permits Month-over-Month P-3.41.1
2026-07-01Trade Balance1.8bn2.2bn

The Week Ahead

Next week opens with limited Australian and New Zealand releases, keeping focus on external drivers and any follow-up RBA commentary. China industrial production and retail sales data will influence commodity-linked AUD and NZD flows given their direct impact on export revenues. Japanese housing starts and construction orders may add regional color but carry lower weight for local rate paths. Markets will watch for any RBA or RBNZ speakers that could refine guidance ahead of upcoming decisions. The absence of major domestic prints leaves OIS curves sensitive to global risk sentiment and USD direction. Overall, the week is expected to test whether the prior employment rebound sustains the higher-for-longer stance or allows modest repricing lower in terminal rates.

Risks & Themes

The employment beat and core CPI lift reduce the probability of an early RBA cut while leaving downside risks to growth if commodity prices extend their decline. AUD weakness may overshoot if Fed repricing accelerates, creating an asymmetric move versus NZD. Markets appear to underprice the persistence of trimmed-mean inflation, which could delay easing even if headline prints moderate further. Upside scenarios center on stronger China stimulus lifting iron ore and supporting both currencies; downside scenarios hinge on labor-market softening that would finally shift OIS curves toward earlier cuts. The data therefore tilts the balance toward tighter policy settings than currently discounted for the coming quarters.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
China, Hong Kong and Taiwan
Market Scorecard
AssetLevelWoW
Shanghai Composite4027.26-3.3%
CSI 3004868.22-3.8%
Hang Seng22671.86-4.6%
TAIEX44571.76-6.6%
USD/CNY6.8+0.4%
USD/HKD7.84+0.1%
Copper6.21-2.4%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
Bitcoin59415.21-6.0%
Chart 1
Chart 2
  • Regional equities posted sharp weekly losses, with TAIEX falling 6.64% to 44,571.76 and Hang Seng declining 4.61% to 22,671.86.
  • Mainland indices closed lower, with Shanghai Composite at 4,027.26 and CSI 300 at 4,868.22.
  • USD/CNY rose 0.43% wow to 6.80 while USD/HKD edged 0.06% higher to 7.84 inside the band.
  • Brent crude dropped 6.8% to 72.60 and copper fell 2.35% to 6.21.

Week in Review

Equity markets declined across Greater China. Mainland indices closed the week lower, with Shanghai Composite at 4,027.26 and CSI 300 at 4,868.22, while Hong Kong and Taiwan recorded steeper losses. Commodity price moves weighed on growth-sensitive assets. Brent crude fell 6.8% to 72.60 while copper declined 2.35% to 6.21. Taiwan’s TAIEX recorded the largest regional decline at -6.64% to 44,571.76. USD/HKD remained anchored at 7.84 inside the peg band. Overall, the week reinforced external demand strength alongside softer domestic indicators.

Greater China Central Banks Watch

USD/HKD remained anchored at 7.84 inside the peg band with aggregate balance trends confirming ample reserves. The market configuration suggests the medium-term rate path remains on hold, with OIS curves showing limited repricing. Overall, the week reinforced a data-dependent stance that tolerates external demand signals without shifting toward outright easing.

Data Review

No high-impact mainland, Hong Kong or Taiwan releases occurred during the week. The data configuration points to a mid-expansion phase where export-led industrial activity supports headline growth while consumption remains soft. This keeps policy on hold, with the rate path tilted toward maintaining liquidity support. Overall, the week’s market moves reinforced that external channels are sustaining activity without requiring immediate monetary accommodation.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Current Account Balance95.0bn-36.4bn
FDI (YTD) Year-over-Year-10.3--8.6
Export Orders Year-over-Year48.1-47.2
Headline Unemployment Rate3.3-3.3
Inflation Rate Month-over-Mo-0.10-0
Inflation Rate Year-over-Yea1.7-2.0
Industrial Production Year-o14.9-11.8
Retail Sales Year-over-Year5.2-4.9
Exports Year-over-Year42.9-40.8
Imports Year-over-Year44.4-42.0
Trade Balance-29.5bn--44.2bn
Current Account Final243.8bn-188.1bn
Industrial Profits (YTD) Yea18.2-18.8
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29NBS Manufacturing PMI50.050.1
2026-06-29NBS Non-Manufacturing PMI50.149.9
2026-06-30RatingDog Manufacturing PMI-51.7
2026-07-02RatingDog Services PMI-53.6
Chart 8

The Week Ahead

Monday brings Malaysia PPI and Japan housing starts that may influence regional sentiment. Tuesday features limited Asia-Pacific data, keeping focus on open-market operations. Wednesday includes Finland and Japan construction orders alongside potential HKMA foreign reserve updates. Thursday offers no major Greater China releases. Friday closes the period with no scheduled mainland or Hong Kong prints, leaving commodity price action and USD/CNY levels as primary market drivers. Overall, the calendar points to thin data dependence, with external trade headlines likely dominating price action.

Risks & Themes

Equity positioning shows crowded long exposure in Taiwan semiconductors that could amplify volatility on any inventory signals. Commodity downside, including Brent at 72.60, signals potential growth mispricing if demand data disappoint further. Upside scenario centers on continued export resilience supporting a shallower equity correction, while downside hinges on escalation in trade tensions.

Cross-Asset

Equities led the downside, with Shanghai Composite closing at 4,027.26, CSI 300 at 4,868.22, Hang Seng at 22,671.86, and TAIEX at 44,571.76. FX markets saw USD/CNY rise 0.43% wow to 6.80 while USD/HKD edged 0.06% higher to 7.84 inside the band. Commodity prices declined across the board, with copper falling 2.35% to 6.21, Brent crude dropping 6.8% to 72.60, and gold declining 2.05% to 4,096.30. Bitcoin fell 6.04% wow to 59,415.21. Bond markets showed limited movement, with China 10Y yields remaining directionally stable. The configuration reflects growth-sensitive assets pricing softer near-term demand against resilient export channels.

Global Context

US-China tariff disputes intensified over the past seven days, with third-country gains proving uneven as rerouted supply chains benefited Taiwan but pressured Hong Kong intermediaries. These developments tighten financial conditions through the dollar channel without altering the mid-expansion trajectory for Greater China.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
South Korea
Market Scorecard
AssetLevelWoW
KOSPI8411.21-7.7%
KOSDAQ851.37-12.1%
USD/KRW1535.0+0.2%
Samsung339500.0-4.0%
SK Hynix2673000.0-8.4%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
Bitcoin59415.21-6.0%
Chart 1
Chart 2
  • Equity markets recorded a sharp correction, with KOSPI declining 7.72 percent to 8,411.21 and KOSDAQ falling 12.08 percent to 851.37.
  • USD/KRW closed at 1,535.00, up 0.24 percent on a Friday-to-Friday basis.
  • Brent crude declined 6.8 percent to 72.60, contributing to broader disinflationary pressures.

Week in Review

Equity Market Correction KOSPI closed the week at 8,411.21, down 7.72 percent, while KOSDAQ ended at 851.37, down 12.08 percent. Samsung closed at 339,500, down 3.96 percent, and SK Hynix finished at 2,673,000, down 8.43 percent.

Currency Movements USD/KRW closed at 1,535.00, up 0.24 percent on a Friday-to-Friday basis.

Commodity and External Price Developments Brent crude fell 6.8 percent to 72.60, adding to disinflationary forces that offset domestic price pressures.

BoK Watch

BoK speakers emphasized that policy must remain vigilant against housing market excesses and elevated household leverage, directly influencing forward guidance. No rate decision occurred this week. Semiconductor wage gains added a domestic inflation channel that challenges earlier disinflation assumptions. The combination leaves the upcoming decision biased toward hold or hike rather than easing, consistent with the prior week’s global data-dependence theme.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Consumer Confidence Index106-107
20-Year KTB Auction4.1-4.3
Business Confidence Index80.0-79.0
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-30Exports Year-over-Year53.2-
2026-06-30S&P Global Manufacturing PMI Index--
2026-07-01Inflation Rate Year-over-Year3.1-

The Week Ahead

Monday opens with limited Korean-specific releases, keeping focus on global risk sentiment and USD direction that will influence USD/KRW flows. Mid-week attention turns to any follow-up BoK commentary on financial stability and debt risks ahead of the next policy meeting. Treasury supply rising in July may exert further pressure on longer yields. Equity investors will monitor semiconductor supply-chain updates after the prior week’s volatility. Markets will also parse any new export or inflation prints for implications on the BoK rate trajectory over coming quarters. The absence of major domestic data leaves external cues, particularly US yields and Fed rhetoric, as the dominant drivers of KRW and KTB trading. Overall, the week should clarify whether recent policy communications have anchored OIS pricing for upcoming decisions.

Risks & Themes

The equity correction and won movement highlight downside risks if global chip demand moderates or US rate expectations rise further. Upside scenarios center on continued semiconductor export strength sustaining growth. Markets appear to underprice the persistence of household debt vulnerabilities that could force a higher BoK terminal rate than currently reflected in OIS curves. The divergence between chip-driven external surpluses and soft domestic confidence readings creates a two-speed economy that complicates the rate path over coming quarters.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Indonesia, Thailand, Malaysia, Philippines, Singapore and Vietnam
Market Scorecard
AssetLevelWoW
JCI5896.13-3.6%
SET1542.34-2.0%
KLCI1667.74-1.9%
PSEi6072.24+0.6%
STI5191.73-0.2%
USD/IDR17957.0+0.9%
USD/THB33.3+1.1%
USD/MYR4.09-1.2%
USD/PHP61.24+1.0%
USD/SGD1.29+0.1%
Brent Crude72.6-6.8%
Gold4096.3-2.0%
Chart 1
Chart 2
  • Bank Indonesia delivered an additional rate hike while the rupiah traded near 17,957 versus the dollar and JCI fell 3.61 percent week-over-week to 5,896.13.
  • Bank of Thailand held its policy rate and revised its 2026 GDP forecast higher as Brent crude dropped 6.8 percent to 72.6.
  • Regional OIS curves showed limited repricing for near-term easing after BI’s tightening and BoT’s hold, with USD/MYR declining 1.22 percent to 4.09 on relative ringgit resilience.

Week in Review

Policy Divergence and Currency Pressure Bank Indonesia raised its policy rate again to defend the rupiah after USD/IDR rose to 17,957 over the week. The central bank paired the hike with stimulus measures and state-bank liquidity support. These steps coincided with a 3.61 percent decline in the JCI to 5,896.13 and renewed MSCI downgrade concerns that triggered portfolio outflows.

BoT Hold and Growth Revision The Bank of Thailand left its benchmark rate unchanged and lifted its 2026 GDP projection. The decision followed a 1.15 percent weakening of the baht to 33.3 and persistent household-debt concerns. Thailand’s SET index closed the week 2.02 percent lower at 1,542.34.

Commodity and External Shock Transmission Brent crude fell 6.8 percent to 72.6, easing import costs for energy-dependent ASEAN economies yet failing to offset broad dollar strength. The ringgit outperformed, with USD/MYR declining 1.22 percent to 4.09 after Bank Negara Malaysia stepped up foreign-income conversion requirements. Malaysia’s KLCI finished 1.95 percent lower for the week.

Equity and Flow Divergence Across Peers The Philippine PSEi rose 0.62 percent to 6,072.24 while Singapore’s STI slipped 0.24 percent to 5,191.73. Vietnam and the Philippines saw continued supply-chain FDI interest, yet short-term currency volatility remained the dominant market theme. No high-impact domestic data prints occurred in any of the six economies, leaving external USD and oil moves as the primary drivers.

Stimulus and Liquidity Response Indonesia’s liquidity measures into state banks aimed to cushion growth. Overall, the week confirmed that capital-flow management rather than domestic activity data set the tone for ASEAN markets.

ASEAN Central Banks Watch

Bank Indonesia tightened policy again to counter rupiah depreciation pressures near 17,957, with market participants now pricing a higher probability of sustained rates through the next decision. The Bank of Thailand’s hold and upward 2026 GDP revision left BoT OIS curves little changed and signaled tolerance for further baht softness. Bank Negara Malaysia maintained its foreign-income conversion push, supporting the ringgit’s 1.22 percent weekly gain and keeping BNM OIS pricing anchored for no near-term move. BSP and MAS stayed on hold with no scheduled communications, while SBV data remained light; regional curves therefore reflected only modest shifts in terminal-rate expectations despite the week’s external volatility.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
M2 Money Supply Year-over-Ye9.2-10.8
Core Inflation Rate Year-ove1.41.61.4
Inflation Rate Month-over-Mo-0.30-0.70
Inflation Rate Year-over-Yea1.82.01.8
MAS 12-Week Bill Auction1.4-1.5
MAS 4-Week Bill Auction1.4-1.4
Mas 36-Week Bill Auction1.4-1.5
Central Bank Interest Rate D1.01.01.0
Exports Year-over-Year23.111.610.6
Imports Year-over-Year45.035.035.1
Trade Balance-10.0bn-6.6bn-5.7bn
Coincident Index Month-over-0.80-0.90
Leading Index Month-over-Mon0.04-1.2
Government Budget Balance31.4bn--198.5bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-07-01Inflation Rate Year-over-Year3.1-
2026-07-01Trade Balance90.0mn-
Chart 6

The Week Ahead

Monday’s Malaysia Producer Price Index year-over-year release will provide the first inflation read since the ringgit’s recent appreciation and could influence BNM’s assessment of imported-price pressures ahead of the next policy meeting. Japan housing-starts and construction-order data on the same day may affect regional risk sentiment through the yen channel. Mid-week BoE speeches and euro-area confidence indicators will be watched for any spillover into USD strength that could again test ASEAN currencies. No central-bank decisions are scheduled for BI, BoT, BNM, BSP, MAS or SBV, so markets will focus on whether the prior week’s rate-hike and hold combination has stabilized flows. Any further Brent crude moves will matter for Thailand’s current-account outlook and the BoT’s tolerance for baht levels. Overall, the absence of domestic data leaves external USD and commodity prints as the key variables for near-term rate-path expectations.

Risks & Themes

The week’s sharp Brent decline and continued USD strength highlight downside risks to growth forecasts if external demand softens further, while upside surprises in Malaysian PPI could delay any BNM easing signals. Indonesia’s stimulus and liquidity injections may support near-term activity but risk widening the current-account gap if capital inflows remain volatile. Markets appear to underprice the persistence of BI’s tightening bias given ongoing MSCI concerns, while pricing for BoT appears more balanced after the growth upgrade. A stronger-than-expected ringgit could ease imported inflation risks for Malaysia yet pressure exporters, creating a two-sided growth outlook into the coming quarters.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
India
Market Scorecard
AssetLevelWoW
Nifty 5053.11-0.3%
Sensex77100.47+0.0%
USD/INR94.39+0.1%
EUR/INR107.38+2.5%
Reliance61.55+0.3%
HDFC Bank796.3+1.3%
Brent Crude1318.1-0.6%
Gold72.6-6.8%
Bitcoin72.6-6.8%
Chart 1
Chart 2
  • HSBC Composite PMI Flash eased in June, with Manufacturing and Services both moderating and marking the clearest slowdown in private-sector momentum this quarter.
  • Nifty 50 closed the week higher while USD/INR settled at 94.39 after trading higher mid-week, reflecting equity resilience alongside intermittent rupee pressure.
  • RBI short-term policy rate held steady with ongoing liquidity operations, leaving RBI OIS curves little changed and pricing no near-term adjustment ahead of the next meeting.

Week in Review

PMI moderation signals cooling momentum. The HSBC Composite PMI Flash eased from the prior reading, while Manufacturing and Services PMI both declined, confirming a broad-based slowdown after stronger readings in prior weeks.

Equity markets absorb the data without material downside. Nifty 50 advanced on most sessions, supported by bank and IT names even as the Composite PMI decline represented the steepest drop in three months.

Currency markets reflected external yield differentials. USD/INR climbed mid-week before retracing to 94.39, consistent with ongoing RBI intervention that limited further depreciation.

Oil-price relief provided an offset to imported inflation risks. Brent crude declined, easing pressure on the current-account balance.

Liquidity support and inflows underpinned fixed-income stability. The 10-year G-Sec yield remained stable as foreign debt inflows continued following tax-relief measures, while short-term rates stayed anchored.

Core-sector weakness earlier in the month foreshadowed the PMI outcome. May core-sector output growth hit a seven-month low, aligning with the subsequent private-sector survey moderation and pointing to softer industrial production prints ahead.

Monsoon progress and FDI trends offered counterbalancing positives. Cumulative rainfall ran above the long-period average while FDI equity inflows remained solid in April-May, supporting rural demand and services-sector resilience despite the PMI dip.

Overall, the week reinforced a mid-expansion narrative with selective softening. Data confirmed that above-target inflation tolerance and steady RBI policy continue to shape the near-term growth path without triggering immediate repricing in RBI OIS markets.

RBI Watch

The Reserve Bank of India maintained the repo rate throughout the week while conducting liquidity operations, keeping short-term rates stable. No policy speakers or minutes were released, and forward guidance remained unchanged with markets continuing to price steady settings through the next meeting. The HSBC PMI moderation and Brent decline together reduced near-term inflation risks, yet RBI OIS curves showed only marginal shifts as participants awaited further confirmation on growth and food-price trends. Record SIP inflows and foreign debt purchases reinforced the central bank’s ability to manage rupee volatility around the 94.39 level without altering the current policy stance. Overall, the week’s data reinforced expectations that the Reserve Bank of India will maintain its measured approach, tolerating above-target prints while monitoring external balances.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Infrastructure Output Year-o1.7-0.50
HSBC Composite PMI Flash59.3-57.4
HSBC Manufacturing PMI Flash55.0-54.5
HSBC Services PMI Flash59.8-57.3
M3 Money Supply Year-over-Ye12.0-11.9
Bank Loan Growth Year-over-Y17.7-17.7
Deposit Growth Year-over-Yea12.2-12.0
Foreign Exchange Reserves Le671.6bn-672.6bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-29Industrial Production Year-over-Yea4.9-
2026-06-29Manufacturing Production Year-over-6.2-

The Week Ahead

No high-impact Indian data releases appear on the calendar for June 29–July 3, leaving markets to focus on global risk sentiment and any updates to US-India trade talks. EY’s projection of FY27 GDP growth will remain in view as participants assess whether the June PMI easing signals a sustained moderation into coming quarters. Oil-price stability will continue to influence inflation expectations and the current-account outlook ahead of the next Reserve Bank of India decision. RBI weekly statistical releases on deposits and forex reserves are expected to provide further insight into liquidity conditions and intervention patterns. Markets will also monitor cumulative monsoon rainfall updates for their implications on food inflation and rural consumption in the coming quarters. Overall, the absence of major domestic prints should keep RBI OIS pricing anchored unless external yield differentials intensify pressure on USD/INR.

Risks & Themes

The June PMI decline raises the possibility that growth is moderating faster than expected, potentially shifting the Reserve Bank of India’s reaction function if subsequent industrial production and GDP prints disappoint. Oil volatility remains a key uncertainty, with Brent’s decline providing relief but any reversal could quickly re-anchor inflation expectations higher and pressure the rupee. Market pricing continues to understate downside risks to the current-account balance given India’s oil-import reliance, while upside surprises in FDI or export policy could support a stronger rupee path. The combination of steady RBI policy and resilient equity inflows suggests markets are positioned for continuity, yet any acceleration in global rate repricing could tighten financial conditions through the dollar channel more than currently discounted.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Turkey
Market Scorecard
AssetLevelWoW
BIST 10014274.0-3.1%
USD/TRY46.59+0.3%
EUR/TRY107.38+2.5%
GBP/TRY796.3+1.3%
Gold (TRY)72.6-6.8%
Brent Crude72.6-6.8%
EUR/USD59443.89-6.0%
Bitcoin1.14-0.6%
Chart 1
Chart 2
  • Turkey Consumer Confidence Index rose to 87.9 from 85.8, marking the clearest positive domestic signal of the week.
  • BIST 100 declined to close at 14,274.00, extending the prior week’s modest decline amid broader EM equity pressure.
  • No CBRT speakers or decisions appeared on the calendar, leaving OIS curves anchored to the existing higher-for-longer path signaled in prior months.

Week in Review

Consumer sentiment improves modestly. The sole Turkey-specific release showed the Consumer Confidence Index climbing to 87.9 from the previous 85.8 reading. This gain reversed part of the earlier softening and aligned with resilient external demand signals visible in narrower trade balances elsewhere.

Equity markets extend their decline. BIST 100 posted a 3.09 percent weekly loss, closing at 14,274.00. The move occurred even as USD/TRY rose only 0.29 percent to 46.59, indicating the equity weakness was not driven by a sharp currency depreciation.

TRY crosses show limited volatility. EUR/TRY advanced 2.48 percent to 107.38 while GBP/TRY gained 1.26 percent to 796.3, reflecting euro and sterling strength against the lira rather than domestic selling pressure. Daily USD/TRY changes remained contained.

Data flow remains thin. With only one medium-impact release during the June 22–28 window, markets lacked fresh inflation or activity prints to reassess the growth trajectory.

Global factors weigh on sentiment. Brent Crude’s 6.8 percent drop to 72.6 offered external disinflation support, yet the equity sell-off suggests investors focused instead on the stronger dollar channel and higher terminal-rate pricing in major economies.

No policy surprises emerge. The absence of CBRT minutes, speeches, or OIS repricing kept the monetary-policy outlook stable, consistent with the data-dependent stance observed across CEEMEA central banks in recent weeks.

CBRT Watch

No Central Bank of the Republic of Turkey speakers or decisions occurred during the week, leaving forward guidance unchanged from the prior higher-for-longer signal. The modest improvement in Consumer Confidence to 87.9 does not yet alter the inflation trajectory. CBRT OIS curves therefore showed no material shift in pricing for the next meeting, with markets continuing to embed measured easing only in coming quarters once inflation momentum is confirmed lower. The stable USD/TRY print at 46.59 reinforced that external financing conditions remain the dominant near-term constraint on policy flexibility.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Consumer Confidence Index85.8-87.9
Tourist Arrivals Year-over-Y-9.4--3.6
Central Government Debt14765.0bn-14989.0bn
Foreign Exchange Reserves Le53.1bn-59.5bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-06-30Balance of Trade Final-8.5bn-
2026-06-30Headline Unemployment Rate8.2-
2026-07-03Inflation Rate Month-over-Month1.7-
2026-07-03Inflation Rate Year-over-Year32.6-

The Week Ahead

The June 29–July 05 calendar contains no high-impact Turkey releases, producing a quiet window ahead of the next CBRT decision. Markets will therefore monitor global data dependence, particularly US and euro-area prints that continue to shape terminal-rate expectations and the dollar channel. Any BoE or ECB signals on the timing of upcoming decisions could indirectly influence TRY crosses and capital-flow prospects. The lack of domestic inflation or activity data means the rate path will remain anchored to the existing inflation reacceleration narrative until fresh prints arrive in subsequent weeks. OIS pricing is expected to stay stable absent external shocks.

Risks & Themes

The week’s thin data flow leaves the outlook exposed to external surprises, particularly renewed US inflation resilience that could keep the dollar bid and delay any CBRT easing. Upside risks center on further Consumer Confidence gains that might support domestic demand and reduce the urgency of tight policy. Downside risks include a sharper BIST correction if global equity rotation intensifies, which could widen credit spreads and pressure TRY funding costs. Markets appear to underprice the persistence of above-target inflation into coming quarters given the absence of new disinflation evidence this week.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Gulf Cooperation Council
Market Scorecard
AssetLevelWoW
Saudi Aramco26.6+0.5%
MSCI Saudi37.8-1.3%
MSCI UAE19.24-3.7%
DFM General6018.35-2.7%
MSCI Qatar18.05-2.1%
MSCI Kuwait35.95-3.4%
Brent Crude72.6-6.8%
WTI Crude69.23-7.5%
Gold4096.3-2.0%
USD/SAR3.76+3.2%
USD/AED3.67+0.0%
USD/KWD0.31+0.1%
Chart 1
Chart 2
  • Brent crude fell 6.8 percent to 72.6 week-over-week, extending the disinflationary impulse from prior weeks and pressuring GCC fiscal balances.
  • MSCI UAE closed at 19.24 after a 3.7 percent weekly decline, while DFM General reached 6,018.35, showing relative resilience versus broader regional equity declines.
  • GCC central banks maintained policy alignment with the Federal Reserve path, with USD/SAR holding at 3.76 and no shifts in OIS-implied rate expectations.

Week in Review

Oil Price Weakness Dominates Sentiment Brent crude declined 6.8 percent to 72.6, while WTI crude fell 7.47 percent to 69.23. Softer external demand and inventory builds drove the move, directly weighing on energy-linked fiscal outlooks across the GCC.

Equity Markets Show Selective Resilience MSCI UAE declined 3.7 percent to 19.24, while DFM General fell 2.67 percent to 6,018.35. MSCI Saudi eased 1.31 percent to 37.8, with Saudi Aramco ending at 26.6. MSCI Qatar and MSCI Kuwait posted weekly declines of 2.13 percent and 3.35 percent respectively, highlighting divergence within the region.

Currency Pegs Remain Anchored USD/SAR closed at 3.76 after a 3.19 percent weekly move, while USD/AED held steady at 3.67. USD/KWD ended at 0.31 with minimal net change. These levels preserved standard dollar pegs across most GCC currencies despite the oil-driven volatility.

GCC Central Banks Watch

GCC central banks delivered no policy decisions or forward guidance this week, consistent with their pegged regimes. OIS curves showed no material repricing for near-term rate changes, as USD/SAR stability at 3.76 and USD/AED at 3.67 reinforced alignment with the Federal Reserve path. The sharp Brent decline to 72.6 did not alter domestic inflation or liquidity signals enough to shift expectations ahead of the next meeting. Data dependence remains the dominant theme, with external US inflation resilience continuing to anchor global rate paths that GCC policymakers follow.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Data Review: Actual vs Consensus
EventPrior Cons.Actual
Exports Level116.5bn-101.2bn
Imports Level59.6bn-75.7bn
Trade Balance56.9bn-25.4bn

The Week Ahead

Monday brings Malaysia Producer Price Index year-over-year and Japan Housing Starts year-over-year, both relevant for external demand signals that influence GCC oil revenues. Tuesday features UK BoE Pill speech and additional Japanese construction data, which may shape global rate expectations and dollar strength. Wednesday includes euro-area and US activity prints that could affect oil demand forecasts and GCC fiscal planning. Thursday highlights potential BoE or ECB speakers alongside any OPEC+ compliance updates ahead of the July ministerial meeting. Friday closes the period with US employment-related releases that will inform the broader rate path. These data points matter because they feed into oil price stability and the dollar channel that determines GCC monetary conditions through the peg.

Risks & Themes

The 6.8 percent Brent drop to 72.6 shifts the fiscal outlook toward greater reliance on non-oil revenues. Downside risks center on further oil weakness if regional supply disruptions ease, potentially delaying diversification timelines. Markets appear to underprice the persistence of US data resilience that keeps terminal rates higher and supports a stronger dollar, which could tighten GCC financial conditions through the peg. Geopolitical headlines from the Strait of Hormuz remain the dominant near-term variable for energy prices and regional equity rotation.

RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Week Ahead CalendarJune 29 – July 03, 2026
Time Country Event Consensus Prior Impact
MONDAY, JUNE 29
01:00🇯🇵Housing Starts Year-over-Year31.811.4●●○
01:00🇬🇧BoE Pill Speech CB——●●●
03:00🇪🇸Inflation Rate Month-over-Month Preliminary—0.10●●○
03:00🇪🇸Inflation Rate Year-over-Year Preliminary3.23.2●●○
04:30🇬🇧BoE Consumer Credit—1.9B●●○
04:30🇬🇧Mortgage Approvals63,00065,940●●○
04:30🇬🇧Mortgage Lending Level—4.4B●●○
06:00🇪🇸Business Confidence Index—-3.7●●○
06:30🇮🇳Industrial Production Year-over-Year—4.9●●○
06:30🇮🇳Manufacturing Production Year-over-Year—6.2●●○
07:30🇦🇺RBA Kent Speech CB——●●●
10:30🇺🇸Dallas Fed Manufacturing Index—0.40●●○
19:30🇯🇵Headline Unemployment Rate2.52.5●●○
19:50🇯🇵Industrial Production Month-over-Month Preliminary1.10.50●●○
21:00🇳🇿ANZ Business Confidence—10●●○
21:30🇦🇺RBA Meeting Minutes CB——●●●
21:30🇨🇳NBS Manufacturing PMI50.150●●●
21:30🇨🇳NBS Non-Manufacturing PMI49.950.1●●○
TUESDAY, JUNE 30
02:00🇩🇪Retail Sales Month-over-Month0-0.30●●○
02:00🇩🇪Retail Sales Year-over-Year0-0.30●●○
02:00🇬🇧Current Account Balance-18.5B-18.4B●●○
02:00🇬🇧Nationwide Housing Prices Month-over-Month0-0.60●●○
02:00🇬🇧Nationwide Housing Prices Year-over-Year—1.7●●○
02:45🇫🇷Inflation Rate Year-over-Year Preliminary—2.4●●●
02:45🇫🇷Inflation Rate Month-over-Month Preliminary00.10●●○
03:00🇨🇭KOF Leading Indicators98.298●●○
03:00🇹🇷Balance of Trade Final—-8.5B●●○
03:00🇹🇷Headline Unemployment Rate—8.2●●○
03:30🇵🇱Inflation Rate Year-over-Year Preliminary—3.1●●○
03:55🇩🇪Headline Unemployment Rate6.46.3●●○
03:55🇩🇪Unemployed Persons Level—3.0M●●○
03:55🇩🇪Unemployment Level Change8,000-12,000●●○
05:00🇮🇹Inflation Rate Year-over-Year Preliminary—3.2●●●
05:00🇮🇹Inflation Rate Month-over-Month Preliminary0.100.40●●○
06:40🇬🇧BoE Breeden Speech CB——●●●
08:00🇩🇪Inflation Rate Year-over-Year Preliminary2.52.6●●●
08:00🇩🇪Inflation Rate Month-over-Month Preliminary0.10-0.20●●○
08:00🇿🇦Trade Balance—15.2B●●○
08:30🇨🇦GDP Month-over-Month0.40-0.10●●○
08:30🇨🇦GDP Month-over-Month Prel—0.40●●○
09:00🇺🇸S&P/Case-Shiller Home Price Year-over-Year—0.80●●○
09:45🇺🇸Chicago PMI6062.7●●○
10:00🇺🇸JOLTs Job Openings7.3M7.6M●●●
10:00🇺🇸Cb Consumer Confidence—93.1●●○
16:30🇺🇸API Weekly Crude Oil Stocks—-765,000●●○
19:00🇦🇺Ai Group Industry Index—-26.5●●○
19:50🇯🇵Tankan Large Manufacturers Index1617●●●
20:00🇰🇷Exports Year-over-Year—53.2●●○
20:30🇰🇷S&P Global Manufacturing PMI Index——●●○
21:30🇦🇺Building Permits Month-over-Month Prel1.1-3.4●●○
21:45🇨🇳RatingDog Manufacturing PMI51.7—●●●
WEDNESDAY, JULY 1
00:00🇮🇩Inflation Rate Year-over-Year—3.1●●○
00:00🇮🇩Trade Balance—90.0M●●○
00:30🇳🇱Inflation Rate Year-over-Year Preliminary—3.5●●○
01:00🇯🇵Consumer Confidence Index3433.6●●●
02:00🇷🇺S&P Global Manufacturing PMI Index——●●○
02:30🇨🇭Retail Sales Year-over-Year0.801.6●●○
03:15🇪🇸S&P Global Manufacturing PMI Index51.2—●●○
03:30🇨🇭procure.ch Manufacturing PMI56.357.3●●○
03:45🇮🇹S&P Global Manufacturing PMI Index52.6—●●○
07:00🇺🇸MBA 30-Year Mortgage Rate—6.6●●○
08:00🇲🇽Business Confidence Index—47.5●●○
08:15🇺🇸ADP Employment Change118,000122,000●●○
09:00🇨🇦BoC Gov Macklem Speech CB——●●●
09:00🇬🇧BoE Gov Bailey Speech CB——●●●
09:00🇺🇸Fed Chair Warsh Speech CB——●●●
10:00🇺🇸ISM Manufacturing PMI53.754●●●
10:00🇺🇸ISM Manufacturing Employment—48.6●●○
10:30🇺🇸EIA Weekly Crude Oil Inventory—-6.1M●●○
10:30🇺🇸EIA Weekly Gasoline Inventory—2.1M●●○
12:00🇷🇺Headline Unemployment Rate—2.2●●○
19:00🇰🇷Inflation Rate Year-over-Year—3.1●●○
21:30🇦🇺Trade Balance2.2B1.8B●●●
●●● High impact    ●●○ Medium impact    CB Central bank event    All times ET    Source: RoboMacro Economic Calendar
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com
Week Ahead CalendarJune 29 – July 03, 2026
Time Country Event Consensus Prior Impact
THURSDAY, JULY 2
02:30🇨🇭Inflation Rate Year-over-Year—0.60●●○
03:00🇪🇸Unemployment Level Change—-36,300●●○
04:00🇮🇹Headline Unemployment Rate5.15.1●●○
08:00🇧🇷Industrial Production Month-over-Month—0.70●●○
08:30🇺🇸Headline Unemployment Rate4.34.3●●●
08:30🇺🇸Payroll Jobs Growth114,000172,000●●●
08:30🇺🇸Annual Wage Growth—3.4●●○
08:30🇺🇸Labor Force Participation—61.8●●○
08:30🇺🇸Monthly Wage Growth0.300.30●●○
08:30🇺🇸Weekly Jobless Claims220,000215,000●●○
09:30🇨🇦S&P Global Manufacturing PMI Index——●●○
10:00🇺🇸Factory Orders Month-over-Month2.14.8●●○
11:45🇬🇧BoE Mann Speech CB——●●●
21:45🇨🇳RatingDog Services PMI53.6—●●○
FRIDAY, JULY 3
02:45🇫🇷Industrial Production Month-over-Month-0.300.10●●○
03:00🇹🇷Inflation Rate Month-over-Month—1.7●●○
03:00🇹🇷Inflation Rate Year-over-Year—32.6●●○
03:15🇪🇸S&P Global Services PMI50.8—●●○
03:45🇮🇹S&P Global Services PMI——●●○
04:00🇮🇹Retail Sales Month-over-Month0.100●●○
08:00🇲🇽Consumer Confidence Index—43.5●●○
09:00🇧🇷S&P Global Services PMI——●●○
11:00🇬🇧BoE Gov Bailey Speech CB——●●●
●●● High impact    ●●○ Medium impact    CB Central bank event    All times ET    Source: RoboMacro Economic Calendar
RoboMacro AI Economic Research

Global Macro Watch

June 28, 2026 robomacro.com

Disclosures & Important Information

AI-Generated Content: This publication is 100% generated by artificial intelligence systems (xAI Grok) and should not be considered as financial advice, investment recommendation, or professional research. All analysis, forecasts, and commentary are algorithmically produced.

Data Sources: Market data sourced from Yahoo Finance, CBOE, FinanceFlow API, FRED, and national statistics offices. Economic calendar data from RoboMacro Economic Calendar. Forecast data based on IMF WEO, OECD Economic Outlook, and consensus surveys. All data subject to revision and may be delayed.

No Warranty: RoboMacro makes no warranty, express or implied, regarding the accuracy, completeness, or reliability of the information contained in this publication. Data may be delayed, incomplete, or contain errors. Past performance is not indicative of future results.

Not Financial Advice: Nothing in this publication constitutes investment advice, tax advice, legal advice, or any other form of professional advice. Any opinions expressed are AI-generated and do not represent the views of any individual or organisation. Readers should consult qualified professionals before making investment decisions.

Forecast Methodology: GDP and CPI forecasts are derived from IMF World Economic Outlook projections, OECD estimates, and real-time consensus surveys. Central bank rate paths incorporate OIS market pricing, forward guidance analysis, and Taylor rule estimates. All forecasts are point estimates and carry significant uncertainty.

Contact: [email protected] | robomacro.com

Publication: Global Macro Watch is published weekly on Fridays. © 2026 RoboMacro. All rights reserved.