ANZ Macro Daily(Beta Mode)
RBA Set to Hike as Inflation Runs Hot
Market Snapshot
| Asset | Level | Change |
|---|---|---|
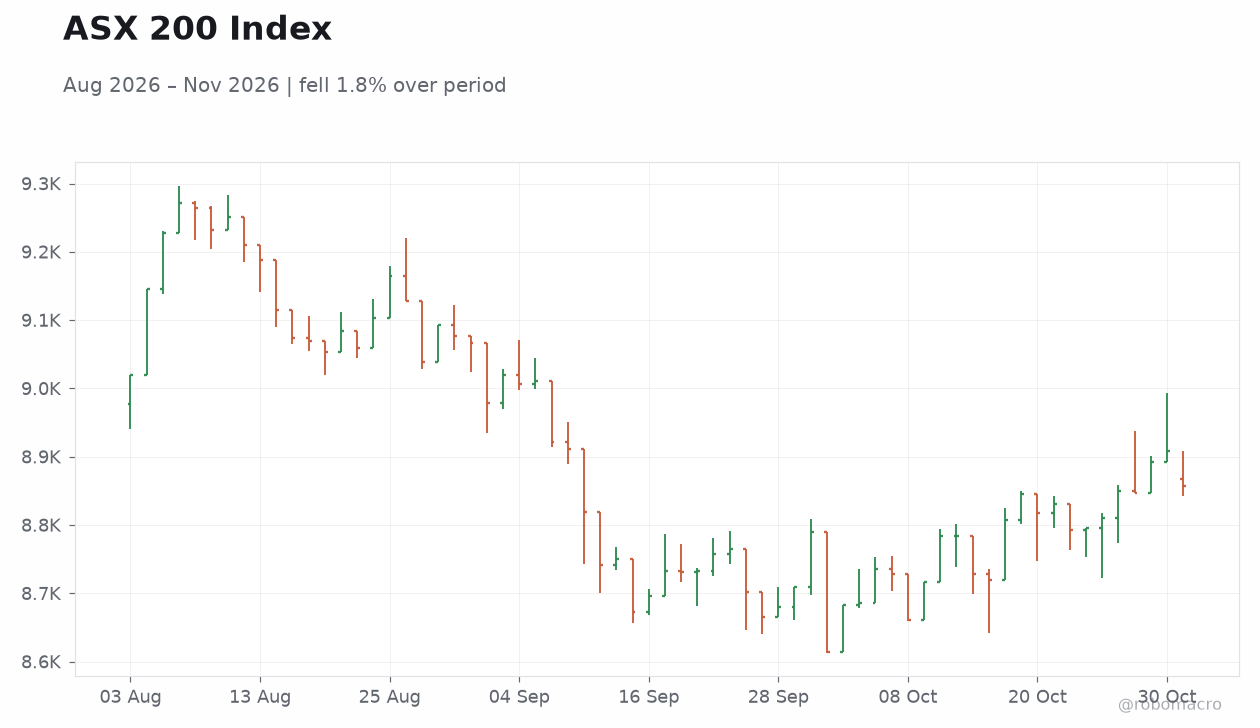
| ASX 200 | 8,856.50 | -0.58% |
| NZX 50 | 13,698.63 | -0.71% |
| AUD/USD | 0.70 | -0.34% |
| NZD/USD | 0.56 | -0.20% |
| AUD/NZD | 1.25 | -0.15% |
| BHP | 57.56 | +0.07% |
| Gold | 3,963.80 | +1.66% |
| Brent Crude | 104.57 | -11.11% |
| Bitcoin | 76,775.42 | -1.88% |
| Australia 2Y Govt Yield | 4.95% | +7 bp |
| Australia 10Y Govt Yield | 5.21% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
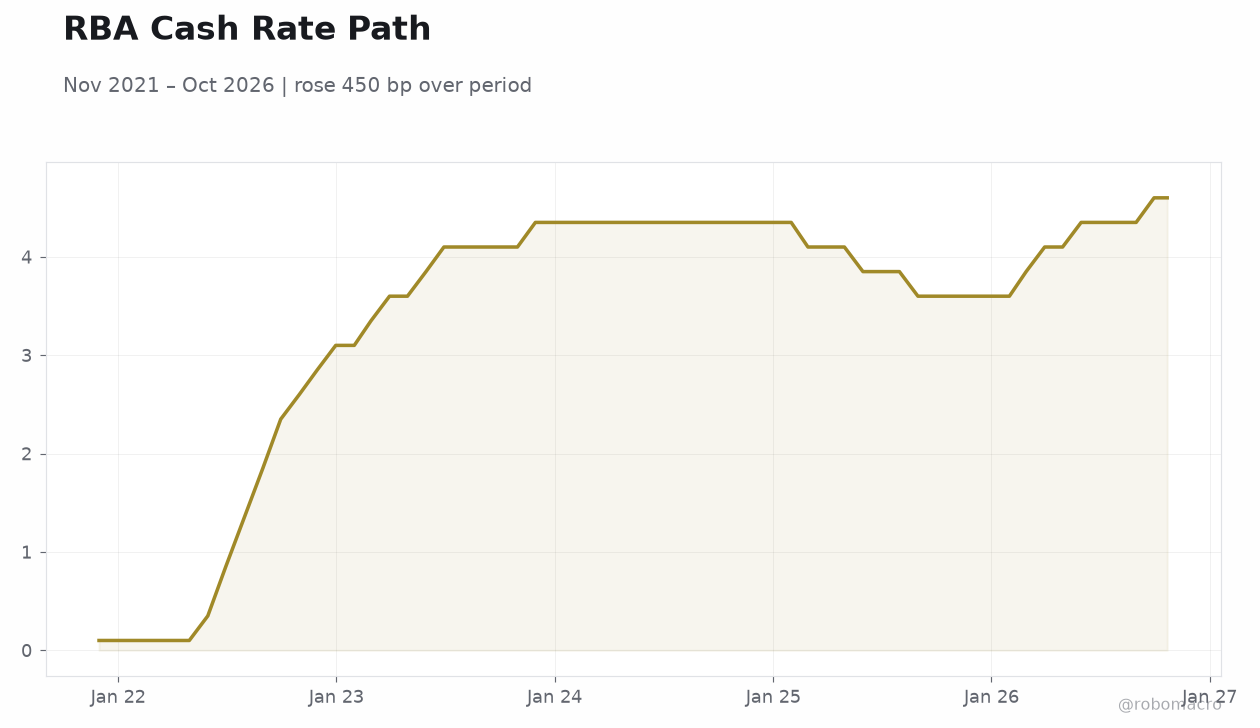 RBA Cash Rate Path | Type: macro_line | Policy Rate (%): 4.6 (2026-10-22) | Range: 0.1–4.6 | Trend(5pt): 0.1,3.35,4.35,3.6,4.6
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| RBA Interest Rate Decision | 4.60 | 4.85 | 22:30 |
| RBA Monetary Policy Statement | - | - | 22:30 |
| RBA Rate Statement | - | - | 22:30 |
| RBA Press Conference | - | - | 23:30 |
- RBA expected to raise the cash rate to 4.85% from 4.60% at today's meeting, with markets pricing renewed tightening after hotter-than-expected CPI
- Australian 2Y and 10Y yields rose 7bp and 6bp respectively, reflecting hawkish rate expectations
- NZ employment data tomorrow expected to show unemployment ticking down to 5.5% from 5.6%, with RBNZ already signalling further hikes
Yesterday's Recap
Australian markets closed weaker on Friday, with the ASX 200 down 0.58% to 8,856.50 and the NZX 50 falling 0.71% to 13,698.63. The AUD/USD slipped 0.34% to 0.70 while NZD/USD eased 0.20% to 0.56, with AUD/NZD down 0.15% at 1.25. Australian bond yields moved higher, with the 2-year yield rising 7bp to 4.95% and the 10-year adding 6bp to 5.21%, reflecting market positioning ahead of today's RBA decision.
BHP was essentially flat at A$57.56 (+0.07%), while gold surged 1.66% to US$3,963.80/oz. Brent crude collapsed 11.11% to US$104.57/bbl, a dramatic move likely reflecting demand concerns or supply dynamics. Bitcoin fell 1.88% to US$76,775.
The Day Ahead
All eyes are on the RBA Interest Rate Decision at 22:30 ET, with consensus expecting a hike to 4.85% from the current 4.60%. The RBA Monetary Policy Statement and Rate Statement will be released simultaneously, followed by the RBA Press Conference at 23:30 ET. Markets will scrutinise the statement language for guidance on the pace of further tightening given CPI running at 3.90% YoY.
Domestically, the Ai Group Industry Index is due at 17:00 ET, with the previous reading at -24.2 suggesting continued weakness in manufacturing conditions. Tomorrow brings New Zealand's Q3 employment data, with consensus expecting unemployment at 5.5% and employment growth of 0.4% q/q.
Other Economic Notes
The RBA's decision comes amid growing concerns about the impact of cumulative rate hikes on Australian households and businesses, with New South Wales warning of potential business closures. Australia's rate hiking cycle has outpaced major economies, raising questions about the appropriate terminal rate. The housing market remains a critical transmission channel, with higher rates weighing on property values and construction activity.
New Zealand's economy faces similar pressures, with the RBNZ's aggressive stance raising concerns about over-tightening. The divergence between RBA and RBNZ policy paths remains a key theme, with markets watching for signs of coordination or divergence.