RoboMacro ResearchAlso todaySee the FX Daily

ASEAN Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

Rupiah Firms on BI Autonomy Pledge; MAS Looms

JCI5,936.15-2.59%
KLCI1,618.01+0.59%
STI5,415.48+0.25%
USD/IDR17,925.00+0.08%

Market Snapshot

AssetLevelChange
JCI5,936.15-2.59%
KLCI1,618.01+0.59%
STI5,415.48+0.25%
USD/IDR17,925.00+0.08%
USD/THB33.52-0.03%
USD/MYR4.08+0.02%
USD/PHP62.73-0.11%
USD/SGD1.28-0.07%
Brent Crude106.36-0.27%
Gold4,184.20-0.15%
Bitcoin83,354.14+1.95%
Indonesia 10Y Govt Yield--
Thailand 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
No events available
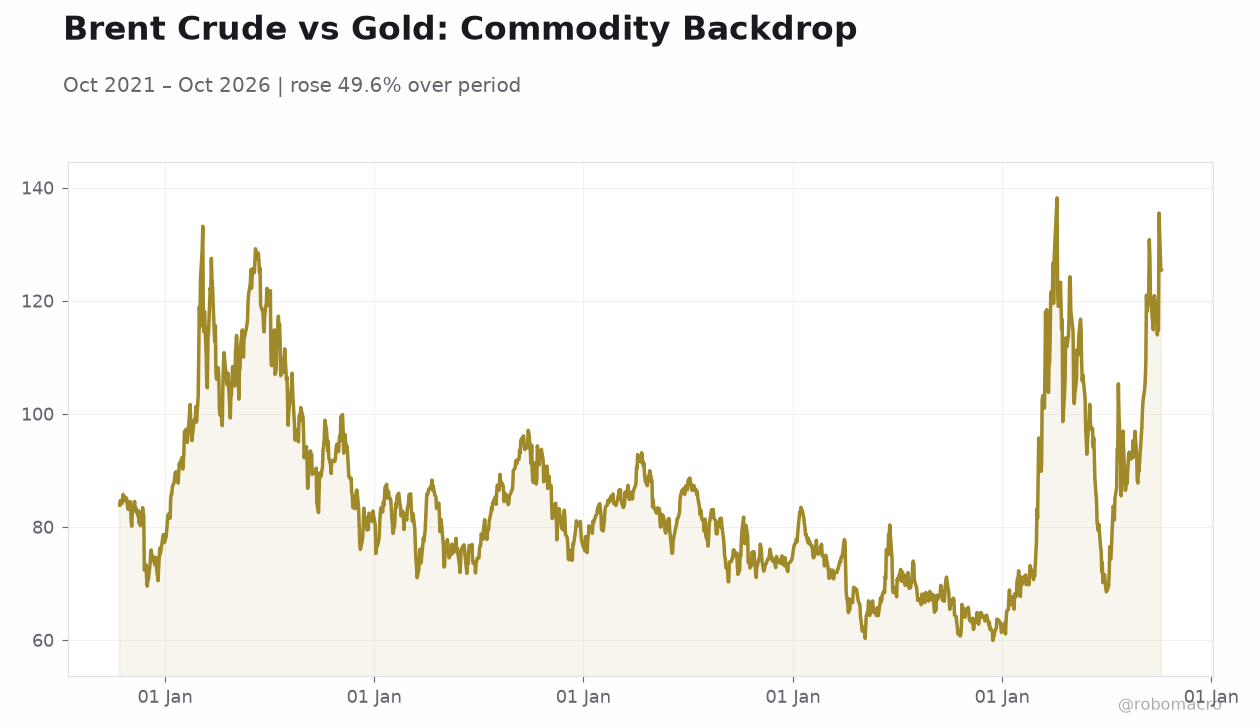
Brent Crude vs Gold: Commodity BackdropBrent Crude vs Gold: Commodity Backdrop | Type: macro_line | Brent Crude (USD/bbl): 125.4 (2026-10-06) | Range: 59.93–138.2 | Trend(6pt): 83.86,82.59,91.49,71.98,125.5,125.4

Today's Economic Events

Data Prior Cons Time
GDP Growth Quarter-over-Quarter Advance Estimate1.400.9020:00
Monetary Policy Statement--20:00
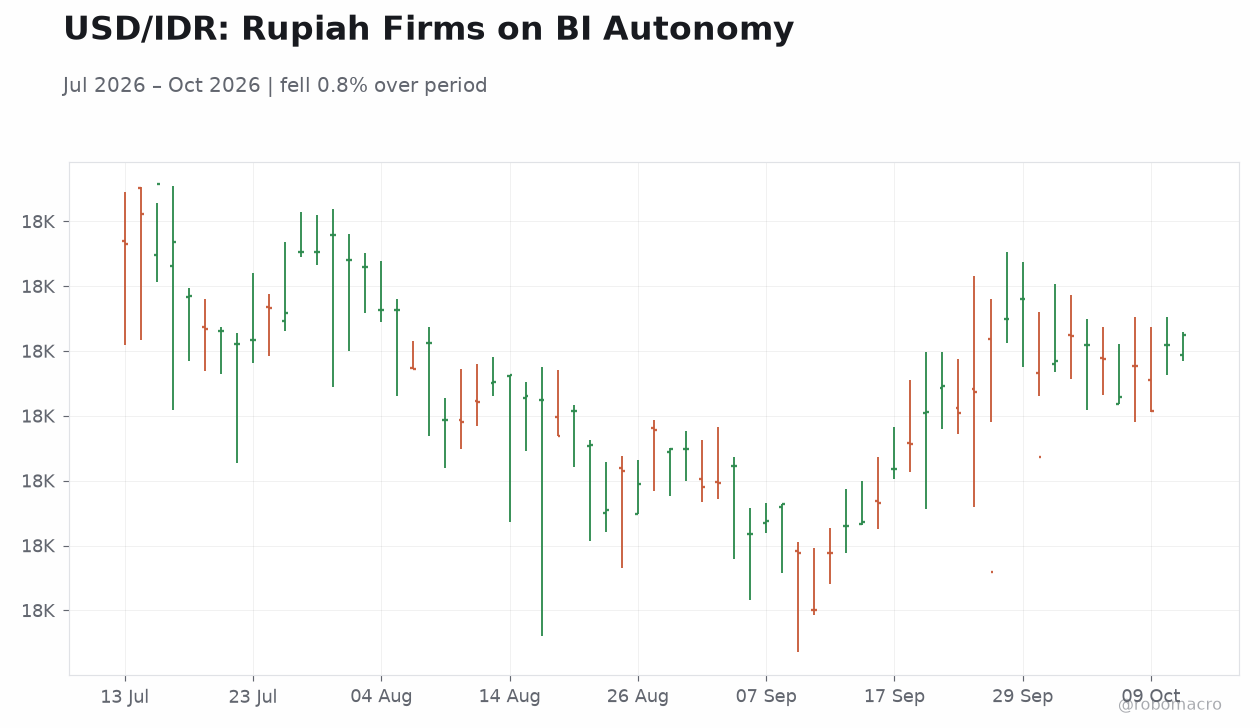
  • Indonesia's rupiah firmed near Rp17,900/USD as new BI Governor Destry Damayanti reaffirmed full central bank autonomy over interest rates, calming policy-uncertainty fears.
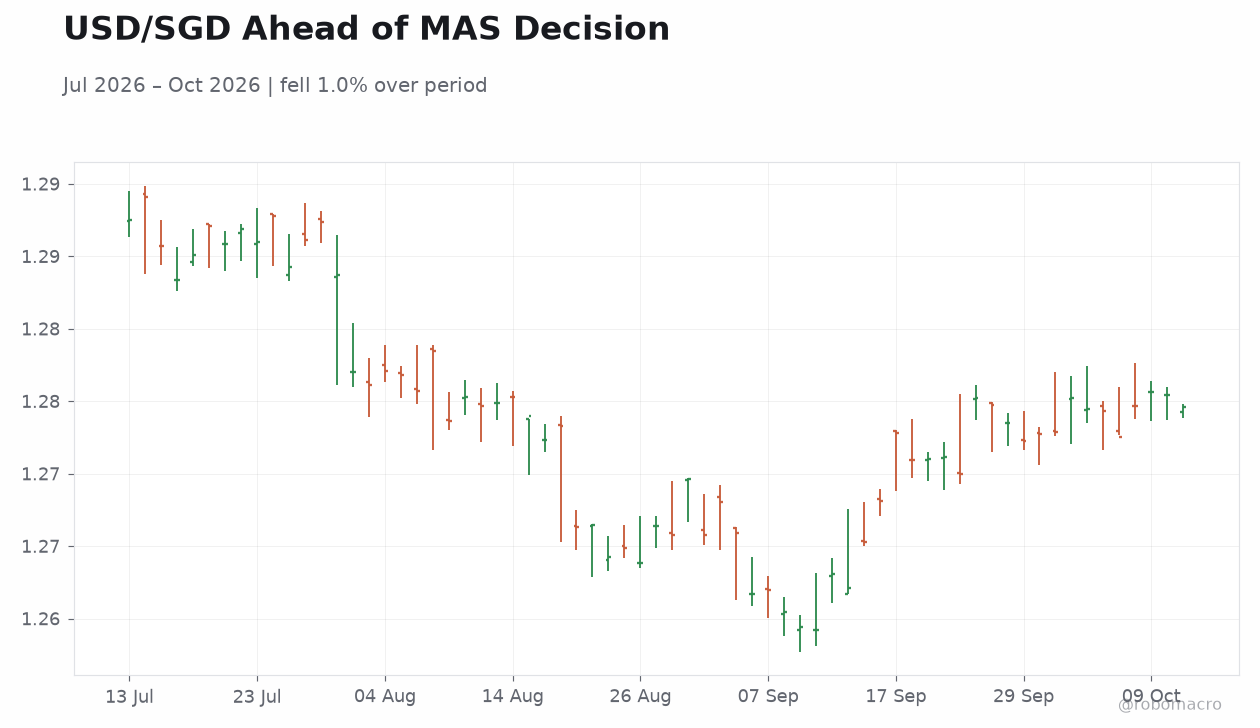
  • Singapore's MAS announces its Monetary Policy Statement today at 20:00 ET alongside advance Q3 GDP, with markets positioned for a "very slight" tightening of the NEER band.
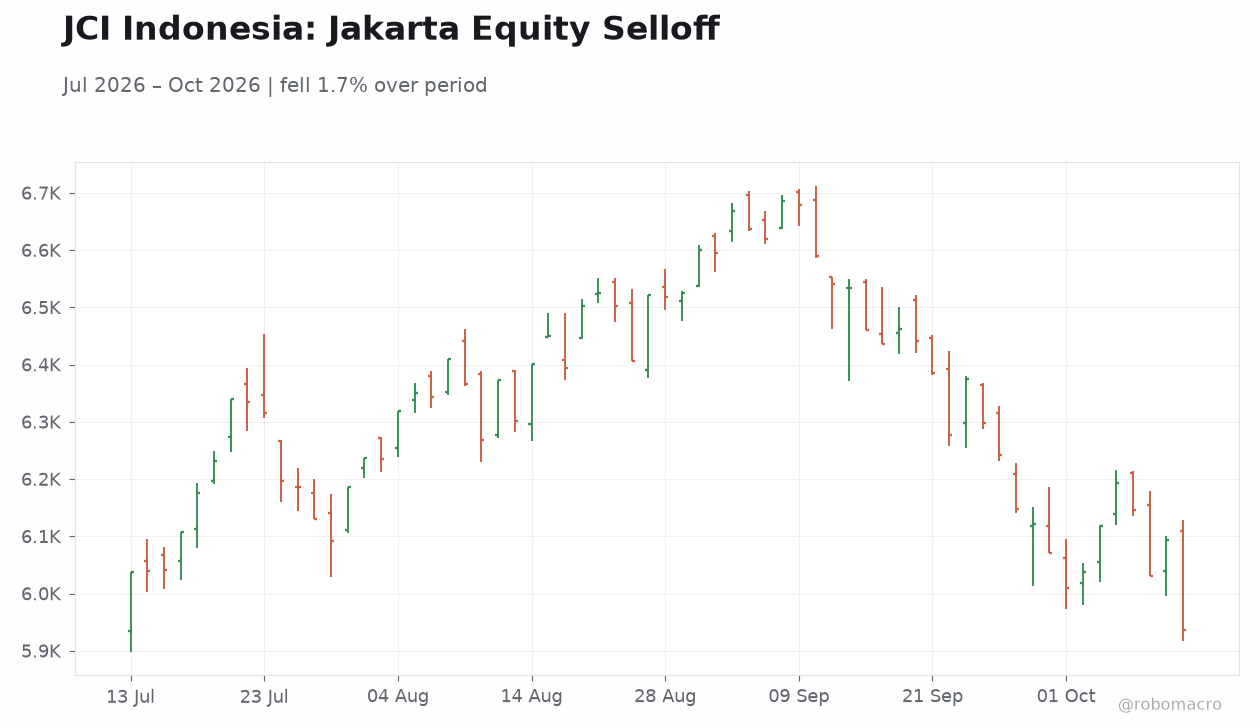
  • Malaysia's ringgit rallied on Budget 2027 fiscal-discipline optimism, while the JCI slumped 2.59% in a broad Jakarta equity selloff.

Yesterday's Recap

Indonesian markets dominated the regional tape on Tuesday, with the rupiah firming to the Rp17,894–17,925/USD range as the dollar index and oil prices eased. The key catalyst was political: incoming BI Governor Destry Damayanti publicly reaffirmed that the central bank retains full autonomy over interest-rate decisions, a statement aimed at quelling speculation of government interference in monetary policy. The reassurance landed well with fixed-income investors, though it did little to lift equities — the JCI fell a sharp 2.59% to 5,936.15, with consumer counters pressured by a softening Indonesian consumer confidence index.

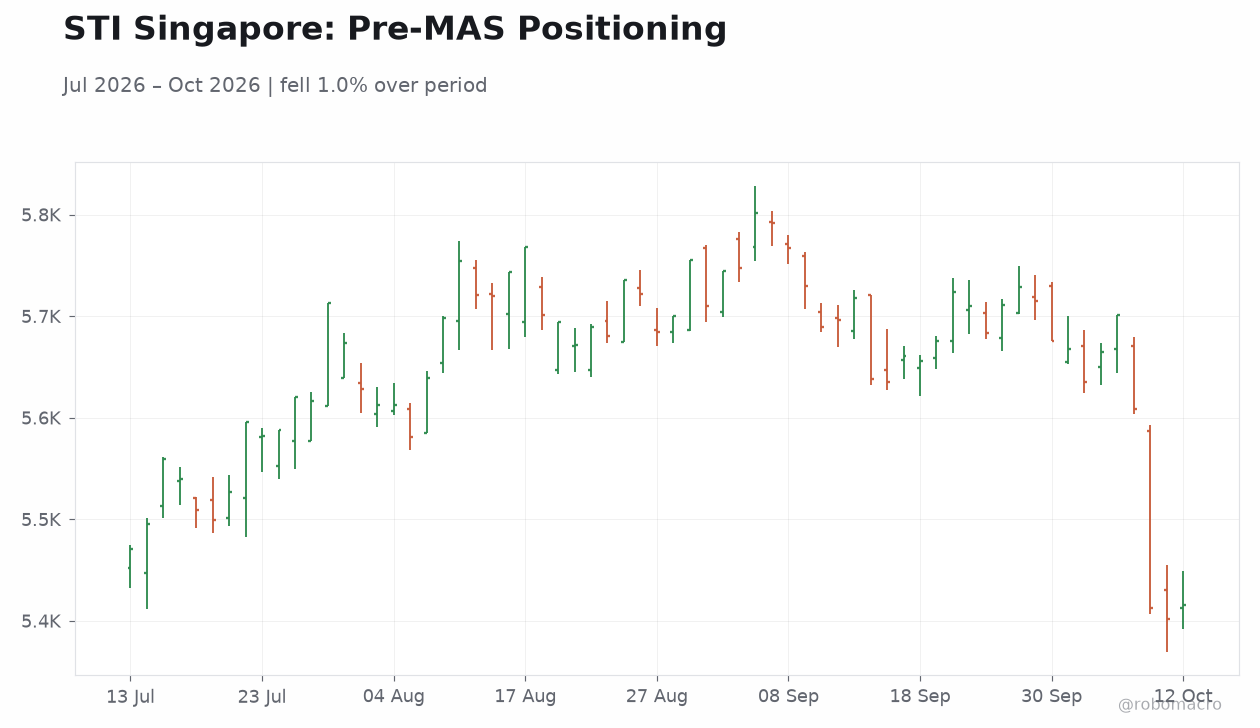
Elsewhere, Malaysia's ringgit closed marginally firmer at 4.08/USD, buoyed by optimism around the Budget 2027 fiscal framework, with the KLCI adding 0.59% to 1,618.01. Singapore's STI edged up 0.25% to 5,415.48 ahead of tonight's policy event, while the Singapore dollar firmed 0.07% to 1.28/USD. The baht was essentially flat at 33.52 and the peso gained 0.11% to 62.73/USD.

Brent crude slipped 0.27% to $106.36, a modest tailwind for the region's net oil importers, while gold eased 0.15% to $4,184/oz and bitcoin rallied 1.95% to $83,354.

The Day Ahead

The focal point is Singapore, where MAS delivers its Monetary Policy Statement at 20:00 ET alongside advance Q3 GDP estimates. The growth print is expected to show quarter-on-quarter expansion slowing to 0.9% from the prior 1.4%, and the policy statement will be scrutinized for any adjustment to the slope, width, or centre of the NEER band. Consensus chatter points to a very slight tightening, with core inflation risks still elevated and the strong Singapore dollar already doing some disinflationary work.

A hold-with-hawkish-guidance outcome cannot be ruled out if the growth slowdown looks sharper than expected. Beyond Singapore, the calendar is quiet, leaving the IMF–World Bank Annual Meetings in Bangkok as the main regional stage for policy commentary. Indonesian officials will also be in focus as markets test the credibility of the new BI leadership's independence pledge in the Rp17,850–17,950 range.
Page 1

ASEAN Macro Daily(Beta Mode)

October 13, 2026 robomacro.com
USD/IDR: Rupiah Firms on BI Autonomy USD/IDR: Rupiah Firms on BI Autonomy | Type: market_hloc | USD/IDR: 1.792e+04 (2026-10-13) | Range: 1.75e+04–1.816e+04 | Trend(6pt): 1.806e+04,1.796e+04,1.77e+04,1.772e+04,1.781e+04,1.792e+04
JCI Indonesia: Jakarta Equity Selloff JCI Indonesia: Jakarta Equity Selloff | Type: market_hloc | JCI Index: 5936 (2026-10-12) | Range: 5936–6686 | Trend(5pt): 6038,6320,6518,6385,5936
USD/SGD Ahead of MAS Decision USD/SGD Ahead of MAS Decision | Type: market_hloc | USD/SGD: 1.28 (2026-10-13) | Range: 1.264–1.294 | Trend(6pt): 1.293,1.282,1.269,1.278,1.281,1.28
STI Singapore: Pre-MAS Positioning STI Singapore: Pre-MAS Positioning | Type: market_hloc | STI Index: 5415 (2026-10-12) | Range: 5402–5802 | Trend(5pt): 5470,5612,5684,5656,5415

Other Economic Notes

Indonesia's finance ministry has moved to curb state spending, a fiscal-consolidation signal that complements, rather than conflicts with, the central bank's independence messaging — a combination investors will welcome after months of fiscal-monetary friction. Jakarta is simultaneously advancing six strategic initiatives to strengthen the sharia economy, part of a longer-term push to deepen Islamic finance and halal-industry value chains. In the Philippines, the IMF projected a growth rebound in 2027 that would outpace regional peers, offering a medium-term anchor for an economy heavily reliant on remittances.

Thailand, hosting the IMF–World Bank gatherings, is being urged to prioritize practical AI adoption to lift productivity and labour-force participation — a structural challenge given its aging demographics and tourism dependence. Malaysia's Genting Berhad slumped to a near two-decade low, a reminder that even in improving macro conditions, idiosyncratic corporate stress persists.

Global Macro News

Global risk sentiment is being shaped by the start of US bank earnings season, with results due Tuesday expected to provide the first hard read on how elevated yields are transmitting through the real economy — a key input for ASEAN rate expectations given the region's sensitivity to the US rate path. The IMF–World Bank Annual Meetings in Bangkok have put energy-market disruption and AI adoption at the top of the global agenda, with the oil-price environment (Brent near $106) a persistent cost pressure for import-dependent ASEAN. ↓ p.3

Sponsored by Arbitrage Search
Page 2

ASEAN Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

Continuation

Global Macro News (continued)

In the UK, MPC member Megan Greene advocated a rate hike, underscoring that developed-market central banks remain inflation-wary — a dynamic that keeps the bar high for aggressive ASEAN easing. Saudi Arabia's contraction warnings amid geopolitical stress add a commodity-supply dimension for Indonesia, a key coal and palm oil exporter. China-linked supply-chain reallocation continues to underpin Vietnam and Malaysia's manufacturing FDI narratives, though no fresh data printed overnight.

ASEAN Central Banks Watch

All eyes are on the MAS tonight, with the market leaning toward a "very slight" tightening of the S$NEER policy band — likely a modest upward slope adjustment — as core inflation proves sticky even as growth cools to a forecast 0.9% q/q. MAS's exchange-rate framework gives it flexibility to fine-tune without the drama of a rate cycle, but a surprise hold would pressure the Singapore dollar. In Indonesia, the new BI leadership's explicit autonomy pledge is the most consequential central-bank story in the region: Destry's comments suggest continuity in the inflation-targeting framework and a willingness to defend the rupiah, which has stabilized near Rp17,900 after recent pressure.

Bank Indonesia's reserve adequacy and FX intervention posture will be watched as the currency tests the narrow 17,850–17,950 band. Malaysia's BNM benefits from the ringgit's Budget 2027-driven strength, giving it room to stay on hold; the fiscal-discipline pledge reduces the risk of a monetary-fiscal clash. The BSP is likely comforted by the IMF's constructive Philippine growth outlook, keeping policy steady into 2027.

Thailand's BoT faces the opposite problem — tepid growth and a flat baht at 33.52 — while Vietnam's SBV continues to balance growth support against dong stability amid sustained manufacturing FDI inflows. The regional picture is one of cautious stability, with Singapore the only near-term policy mover.

Sponsored by Arbitrage Search
Page 3